After your trial, you'll switch to our Free Plan and will not be charged. Stay tuned to your inbox for Bondfish tips and highlights.
Denominated in €, $, £, Fr. Our current spotlight is on the universe of bonds denominated in Euros, US Dollars, British Pounds, and Swiss Francs.
Favorable risk-to-return ratio. In our assessment, the bonds highlighted present tolerable credit risk while offering yields that stand out compared to bank deposits and other bonds.
Accessible Investment Sizes. The bonds are available for trading in smaller, more manageable lots of up to 1,000 EUR or equivalent.
Market Liquidity. We prioritize bonds that are widely accessible through numerous brokers and exhibit active trading with consistent bid and ask quotes.
For each broker we analyse five categories: selection of tradable bonds, trading and custody costs, safety (regulation, capital protection, deposit guarantee), platform experience, and extras such as tax handling, multi-currency accounts or customer service. Within each category we compare brokers on 28 specific criteria and assign a points score; the maximum total is 100 points.
We then convert the overall score into a rating from 0 to 5, where 5.0 represents the maximum possible, using the formula: points awarded / 20 (rounded to one decimal place). This gives the following scale:
| Points awarded | Rating | Test result |
|---|---|---|
| 90 – 100 | 4.5 – 5.0 | Excellent |
| 78 – 89 | 4.0 – 4.4 | Very good |
| 60 – 77 | 3.0 – 3.9 | Good |
| 40 – 59 | 2.0 – 2.9 | Sufficient |
| 20 – 39 | 1.0 – 1.9 | Adequate |
| 0 – 19 | 0 – 0.9 | Poor |
| Category | What it measures | Weight |
|---|---|---|
| Selection | Number and variety of tradable bonds (corporate, sovereign, multi-currency) | 25% |
| Costs | Trading, custody and inactivity fees | 20% |
| Platform | Bond screener, ISIN search, limit orders, usability | 20% |
| Safety | Regulation, banking licence, deposit guarantee | 15% |
| Extras | Tax handling, savings plan, interest on cash, bond ETFs | 20% |
We are currently developing the advanced features of our Professional Plan.
Join our waiting list to get early access and enjoy a free trial when we launch!
By switching to the Basic plan, you will:
Note: You will continue to enjoy Premium features until . You can switch back to the Premium Plan at any time to regain access to all the exclusive features and content.
This page has not been translated into the selected language.
To calculate yield after tax, we need to know your country of tax residence:
This feature is currently supported only for residents of:
If you are a resident of Italy, please update your country in your User Profile settings.
The format we use to display the name of a bond is as follows: “Issuer Name”, “Current Coupon Rate”, “Maturity Date (mm-yyyy)”.
The return you would get if you bought at a given price and held to maturity, expressed on an annualised basis. If the bond has embedded options (i.e. put or call options), the yield is calculated to the worst possible outcome for you.
The difference in before-tax return between an investment in a bond and an investment in a bank deposit, both with the same maturity and in the same currency, assuming the bond is held to maturity. The benchmark deposit rate used for comparison depends on the currency of the bond and is derived from fixed-term deposits available in the following countries:
For the benchmark deposit rate, we use indicative bank deposit rates from central banks. When central bank statistics are significantly delayed, we rely on actual deposit rates from leading banks within the selected country where possible.
The best available clean price at which a bond can be bought.
The term 'firm price' refers to the price that closely approximates the ask price seen from brokers known to us who trade the bond. It is calculated as the average of the best ask prices at market close on the most recent trading day, from the most liquid exchanges where the bond was actively traded. Selecting this option enhances your confidence in matching the price when accessing your broker's application
Proceeds from the bond issue are used to finance environmentally friendly projects, such as reducing carbon emissions or mitigating the effects of climate change
When this option is selected, the screener excludes Subordinated and Senior non-preferred bonds.These bonds rank lower in the repayment order and carry higher risk.
Only Senior and Secured bonds remain visible, which generally have higher priority in case of issuer default.
When this option is selected, the screener excludes bonds that do not pay regular interest. Only bonds with periodic coupon payments remain visible.
Zero-coupon bonds are issued at a discount and repay their full face value at maturity. The investor’s return comes from the difference between the purchase price and the redemption amount.
Example: A 5-year zero-coupon bond bought for €800 and redeemed at €1,000 will generate €200 of income at maturity. This corresponds to an annualized return of approximately 5%: (€1,000 – €800) / €800 / 5
The estimated annualised return if you bought the bond at the current market price and held it to maturity, after applying the applicable tax rate.
Formula:
Yield after tax = Yield × (1 − applicable tax rate)
The tax rate is determined by the country of tax residence selected in your user settings.
In jurisdictions where multiple tax rates apply (e.g. preferential rates for certain bond types), the relevant rate is applied. If a bond benefits from a lower tax rate than the standard base rate, the after-tax yield is highlighted in green.
Important:
This calculation is indicative and based on general assumptions. Individual tax circumstances may differ. Bondfish does not provide tax advice and cannot account for all personal factors. Please consult a qualified tax advisor before making investment decisions.
When enabled, the Yield column displays the estimated yield after tax instead of the gross yield.
Formula:
Yield after tax = Yield × (1 − applicable tax rate)
The applicable tax rate is determined by the country of residence selected in your user settings.
In certain jurisdictions (e.g. Italy), tax rates may vary depending on the bond type. Where relevant, the appropriate rate is applied. If a bond benefits from a tax rate lower than the standard default for that country, the after-tax yield is highlighted in green.
Important:
This calculation is indicative and based on general assumptions. Individual tax circumstances may differ. Bondfish does not provide tax advice and cannot account for all personal factors. Please consult a qualified tax advisor before making investment decisions.
Eligible for 12.5% tax rate:
The time to maturity of a bond from today, expressed in years.
An assessment of a borrower's creditworthiness, or the likelihood that the borrower will pay its debts and not go bankrupt.
Credit risk level is based on the average publicly available credit ratings of the issuer and its bonds assigned by the major rating agencies: S&P, Moody’s, and Fitch.
An assessment of a borrower's creditworthiness, or the likelihood that the borrower will pay its debts and not go bankrupt.
We calculate the average publicly available bond and borrower credit rating assigned by global rating agencies and present it on a five-point scale with the following meaning:
The country in which a borrower's main business is located, either in terms of assets or sources of income.
The high-level type of industry in which the borrower of a bond operates.
Brokers and banks known to us that allow you to trade the bond you are looking at on their platform.
The minimum tradable amount for a bond, expressed in the bond’s currency. This is not relevant if the broker allows you to trade fractions of bonds (Trade Republic is an example).
International Securities Identification Number (ISIN) is a globally recognized unique identifier for a security. Click on it to copy it to the clipboard and look it up with your broker.
We offer two different types of pricing data, both calculated in-house: 'firm price' and 'indicative price'.
The 'firm price' is based on the lowest ask price from the previous day’s trading session taken from the exchanges listed below and adjusted for the liquidity level of the venue specific to the instrument.
Exchanges used to calculate the 'firm price':
The 'indicative price' is generated by our unique pricing model, which aggregates data from multiple sources to estimate a value for the instrument on the last trading day. This model incorporates multi-factor analysis, taking into account aspects such as trading volume at relevant venues, randomised factors and a pre-defined maximum variance.
Please note that the pricing data provided by Bondfish is proprietary and may not be redistributed without explicit permission.
The classification of a bond that indicates the order of priority for repayment in the event of the issuer's bankruptcy:
A bond is considered liquid if, based on data from our partner brokers:
Shows bonds with a purchase price below 100 (below face value).
If you buy a bond below 100 and hold it until maturity, it is usually repaid at 100.
The difference is a capital gain.
Example:
Buy at 95, receive 100 at maturity → +5 capital gain.
In some countries, capital gains can be used to offset previously realized investment losses.
Example:
An investor previously sold shares with a loss of 5.
He buys a bond at 95 and holds it to maturity.
The +5 capital gain can offset the earlier −5 loss, so no tax is paid on the gain.
This improves the net return.
Air France-KLM's bond experienced a significant yield reduction within a week, propelled by the airline's positive strategic initiatives, improved financial outlook, and a notable surge in stock after announcing ambitious profitability goals and successful operational transformations.
The AFFP 1.875 16-JAN-2025 EUR (FR0013477254) bond has witnessed a noteworthy shift in its yield, experiencing a substantial 79 basis points decrease to 4.4% within a week.
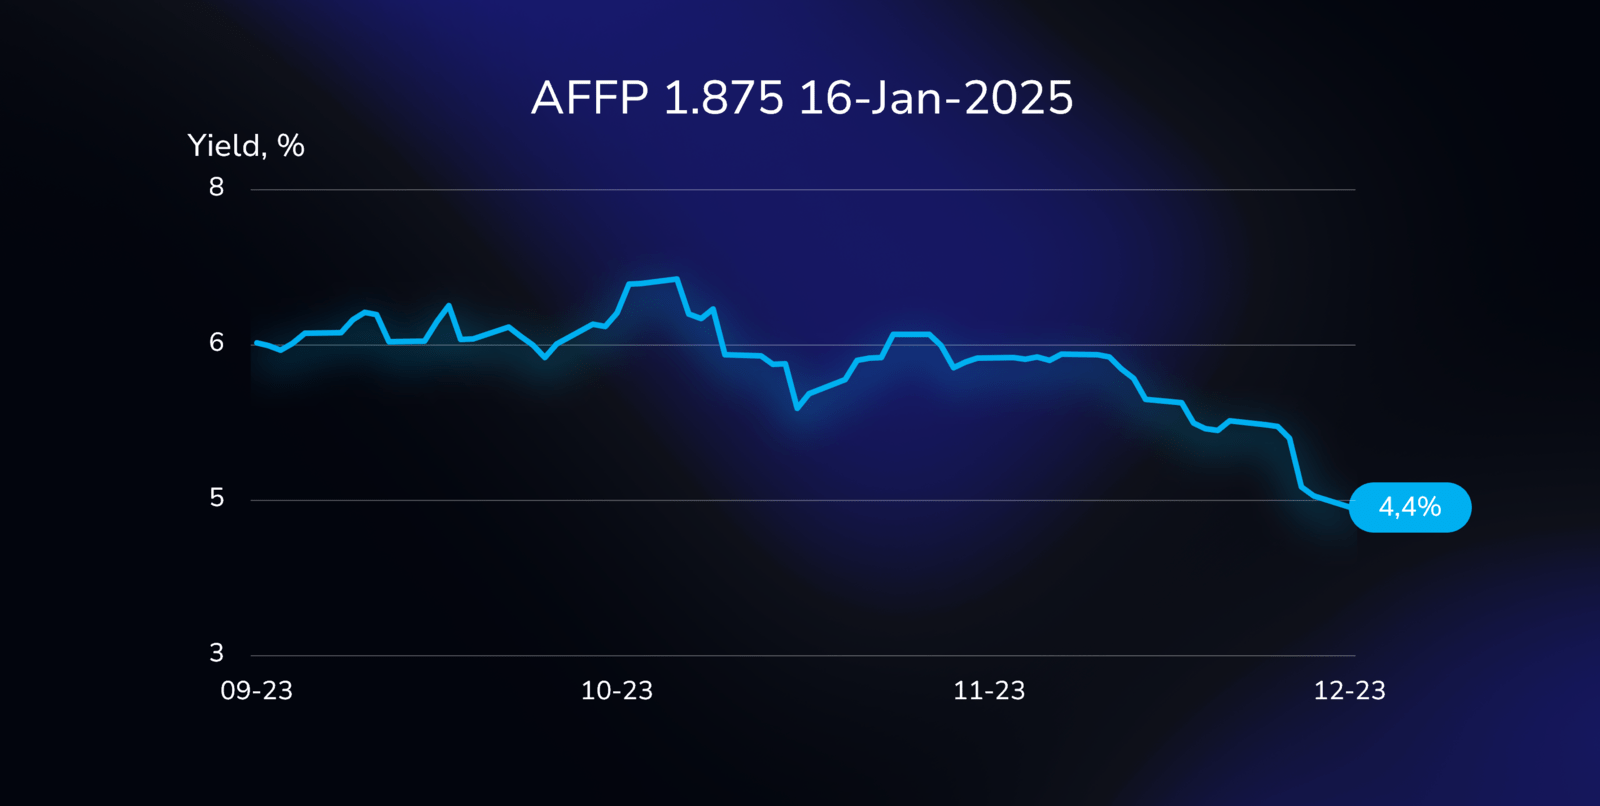
The substantial drop in the bond's yield is intricately linked to Air France-KLM's remarkable strategic moves and improved financial outlook. As of December 14, 2023, Air France-KLM announced a surge in profitability goals, anticipating an operating margin exceeding 8% between 2026 and 2028. This positive development catapulted the airline group's stock, witnessing a 7.9% surge – the highest in nine months.
The surge is attributed to Air France-KLM's successful efforts in transforming its operations since 2019, resulting in solid financial results despite pandemic challenges. CEO Ben Smith's leadership, coupled with initiatives like fleet renewal and strategic alliances, has propelled the airline towards sustained growth. The commitment to eliminating losses at Paris' Orly airport and the ambitious goal of a 2-billion-euro improvement in core profit within five years further fueled investor confidence.
The bond market's favorable response is also influenced by Air France-KLM's prudent financial planning, estimating net capital expenditures and emphasizing partnerships with carriers like Scandinavian Airlines (SAS), Brazilian carrier Gol, and discussions with Avianca. Additionally, the airline's focus on sustainability, evident in securing a third of the required sustainable aviation fuel supply, aligns with market trends.
While Air France-KLM's profitability outlook thrives, challenges such as potential strikes and geopolitical uncertainties linger. However, the airline's proactive approach, including fleet rationalization with Airbus A350 and Boeing 777-300, demonstrates resilience and adaptability.
As of the latest assessments, Air France-KLM has earned an Investment Grade rating of "BBB-" with a Stable Outlook from Fitch and a "BB+" with a Stable Outlook from S&P Global Ratings. This achievement underscores the group's strong operational performance, markedly enhanced financial structure featuring solid liquidity, and a resilient recovery post the challenges posed by the Covid-19 pandemic.
Air France-KLM SA offers air transportation services for passengers and cargo. Its diverse activities encompass cargo, aeronautics maintenance, and various air transport-related services, including catering and charter services. The company operates through segments such as Network, Maintenance, Transavia, and Other. The Network segment includes both passenger and cargo services, while the Maintenance segment provides services globally to other airlines. The Transavia segment focuses on low-cost activities, and the Other segment covers services not included in the mentioned segments. Established on April 23, 1947, the company is headquartered in Paris, France. Air France-KLM SA has a market capitalization of €3.50 billion as of December 15, 2023.