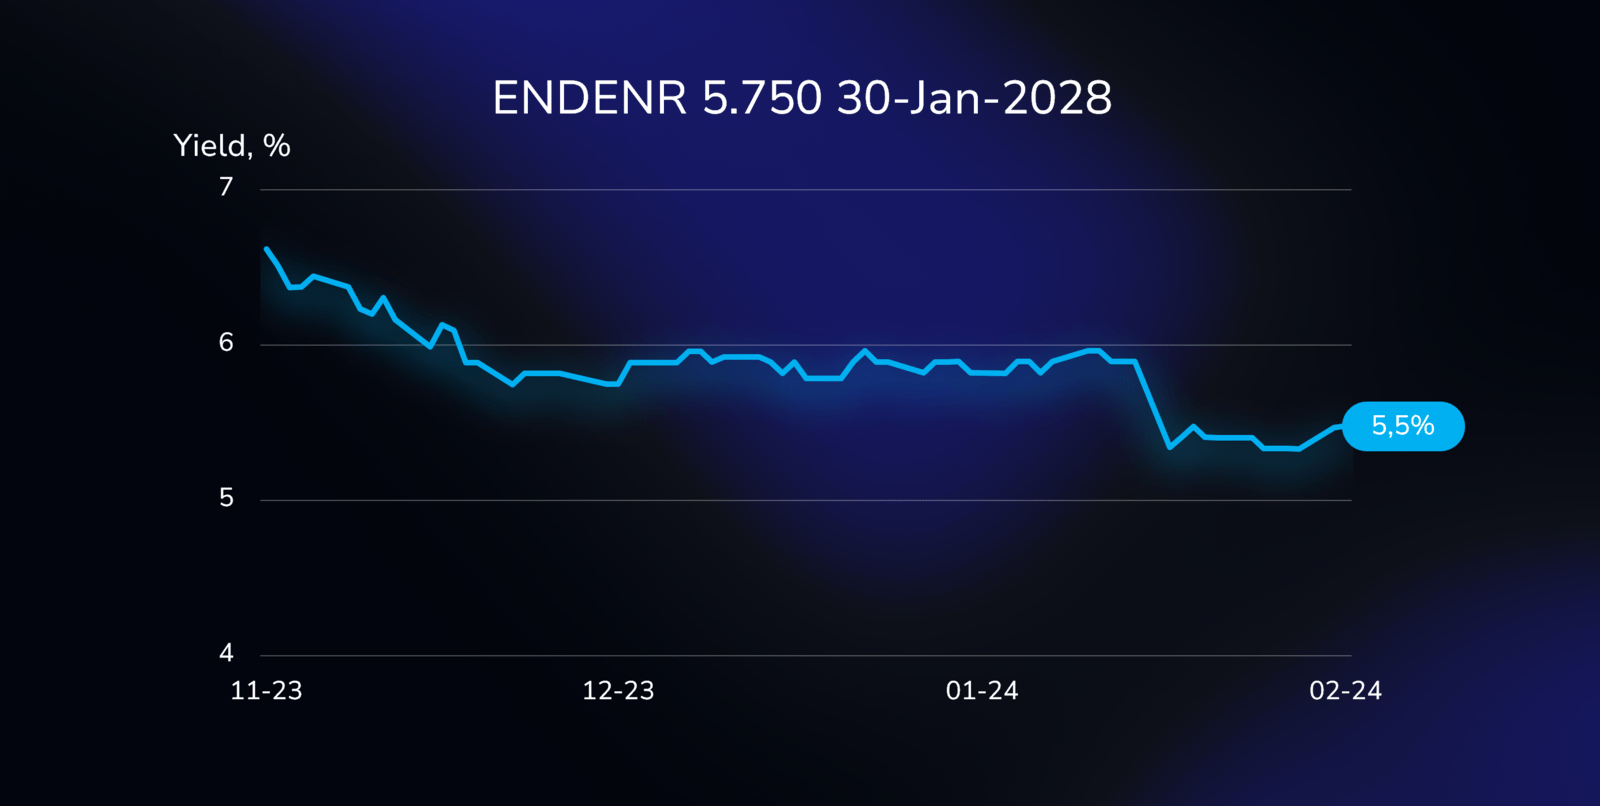
The format we use to display the name of a bond is as follows: “Issuer Name”, “Current Coupon Rate”, “Maturity Date (mm-yyyy)”.
The return you would get if you bought at a given price and held to maturity, expressed on an annualised basis. If the bond has embedded options (i.e. put or call options), the yield is calculated to the worst possible outcome for you.
The difference in before-tax return between an investment in a bond and an investment in a bank deposit, both with the same maturity and in the same currency, assuming the bond is held to maturity. The benchmark deposit rate used for comparison depends on the currency of the bond and is derived from fixed-term deposits available in the following countries:
- EUR – Germany
- USD – United Stated of America
- GBP – United Kingdom
- CHF – Switzerland
For the benchmark deposit rate, we use indicative bank deposit rates from central banks. When central bank statistics are significantly delayed, we rely on actual deposit rates from leading banks within the selected country where possible.
The best available clean price at which a bond can be bought.
The term 'firm price' refers to the price that closely approximates the ask price seen from brokers known to us who trade the bond. It is calculated as the average of the best ask prices at market close on the most recent trading day, from the most liquid exchanges where the bond was actively traded. Selecting this option enhances your confidence in matching the price when accessing your broker's application
Proceeds from the bond issue are used to finance environmentally friendly projects, such as reducing carbon emissions or mitigating the effects of climate change
When this option is selected, the screener excludes Subordinated and Senior non-preferred bonds.These bonds rank lower in the repayment order and carry higher risk.
Only Senior and Secured bonds remain visible, which generally have higher priority in case of issuer default.
When this option is selected, the screener excludes bonds that do not pay regular interest. Only bonds with periodic coupon payments remain visible.
Zero-coupon bonds are issued at a discount and repay their full face value at maturity. The investor’s return comes from the difference between the purchase price and the redemption amount.
Example: A 5-year zero-coupon bond bought for €800 and redeemed at €1,000 will generate €200 of income at maturity. This corresponds to an annualized return of approximately 5%: (€1,000 – €800) / €800 / 5
The estimated annualised return if you bought the bond at the current market price and held it to maturity, after applying the applicable tax rate.
Formula:
Yield after tax = Yield × (1 − applicable tax rate)
The tax rate is determined by the country of tax residence selected in your user settings.
In jurisdictions where multiple tax rates apply (e.g. preferential rates for certain bond types), the relevant rate is applied. If a bond benefits from a lower tax rate than the standard base rate, the after-tax yield is highlighted in green.
Important:
This calculation is indicative and based on general assumptions. Individual tax circumstances may differ. Bondfish does not provide tax advice and cannot account for all personal factors. Please consult a qualified tax advisor before making investment decisions.
When enabled, the Yield column displays the estimated yield after tax instead of the gross yield.
Formula:
Yield after tax = Yield × (1 − applicable tax rate)
The applicable tax rate is determined by the country of residence selected in your user settings.
In certain jurisdictions (e.g. Italy), tax rates may vary depending on the bond type. Where relevant, the appropriate rate is applied. If a bond benefits from a tax rate lower than the standard default for that country, the after-tax yield is highlighted in green.
Important:
This calculation is indicative and based on general assumptions. Individual tax circumstances may differ. Bondfish does not provide tax advice and cannot account for all personal factors. Please consult a qualified tax advisor before making investment decisions.
Eligible for 12.5% tax rate:
- Italian government and municipal bonds
- Government, municipal and supranational bonds issued by countries included in Italy’s “white list”
The time to maturity of a bond from today, expressed in years.
An assessment of a borrower's creditworthiness, or the likelihood that the borrower will pay its debts and not go bankrupt.
Credit risk level is based on the average publicly available credit ratings of the issuer and its bonds assigned by the major rating agencies: S&P, Moody’s, and Fitch.
An assessment of a borrower's creditworthiness, or the likelihood that the borrower will pay its debts and not go bankrupt.
We calculate the average publicly available bond and borrower credit rating assigned by global rating agencies and present it on a five-point scale with the following meaning:
Current average credit rating in the range of AA- and higher
Current average credit rating of A-, A or A+
Current average credit rating of BBB-, BBB or BBB+
Current average credit rating of BB-, BB, BB+
Current average credit rating in the range of B+ and below. Bonds and borrowers that are not rated by any global rating agency also fall into this category
If market interest rates move by 1%, the price of this bond changes by about 1%. Very low sensitivity to rate movements.
A 1% change in market rates moves the bond’s price by around 2–3%. Moderate sensitivity.
A 1% change in interest rates leads to a price move of about 3–4%.
A 1% change in rates can shift the price by around 4–5%. High sensitivity to interest-rate movements.
A 1% move in interest rates changes the bond’s price by more than 5%. Very high rate sensitivity - prices can fluctuate significantly.
The country in which a borrower's main business is located, either in terms of assets or sources of income.
The high-level type of industry in which the borrower of a bond operates.
Brokers and banks known to us that allow you to trade the bond you are looking at on their platform.
The minimum tradable amount for a bond, expressed in the bond’s currency. This is not relevant if the broker allows you to trade fractions of bonds (Trade Republic is an example).
International Securities Identification Number (ISIN) is a globally recognized unique identifier for a security. Click on it to copy it to the clipboard and look it up with your broker.
We offer two different types of pricing data, both calculated in-house: 'firm price' and 'indicative price'.
The 'firm price' is based on the lowest ask price from the previous day’s trading session taken from the exchanges listed below and adjusted for the liquidity level of the venue specific to the instrument.
Exchanges used to calculate the 'firm price':
- Euronext Paris
- Euronext Amsterdam
- Euronext Brussels
- Euronext Lisbon
- Euronext Dublin
- Euronext Oslo
The 'indicative price' is generated by our unique pricing model, which aggregates data from multiple sources to estimate a value for the instrument on the last trading day. This model incorporates multi-factor analysis, taking into account aspects such as trading volume at relevant venues, randomised factors and a pre-defined maximum variance.
Please note that the pricing data provided by Bondfish is proprietary and may not be redistributed without explicit permission.
The name of the organization, government, or municipal authority that has issued the bond.
The currency in which the bond is denominated. This means that you buy or sell the bonds in exchange for that currency, and receive payments from the issuer in that currency.
Interest rate, expressed in annualised terms, that an issuer must pay to holders of the bond. Interest is accrued on the par amount, not the market value.
The coupon rate may be Fixed for the life of the bond.
It may be Floating, linked to a public interest rate benchmark and change based on movements in that rate.
the bond may pay no interest at all. In this case it is called a Zero coupon bond.
Indicates how often the bond pays out its coupon.
The nearest upcoming date on which the bond’s coupon payment will be made to the bondholder.
The date on which the bond was issued by an issuer.
The date on which the bond is to be repaid in full by the borrower. After this date, the bond is no longer active and available for trading.
This is the total value of all notes in the same bond issue that are currently active or unpaid. It's found by multiplying the par amount of the bond (usually set at 1,000 euros, dollars, etc.) by the total number of those notes. The amount is displayed in the currency of the bond.
The classification of a bond that indicates the order of priority for repayment in the event of the issuer's bankruptcy:
- Secured and Senior bonds are repaid first.
- Senior Non-preferred bonds issued by financial institutions are repaid after Secured and Senior Preferred bonds.
- Subordinated and Junior Subordinated bonds are repaid last, so their holders may suffer the greatest losses if the borrower goes out of business.
Indicates whether the bond can be called by the issuer. Hover over the value to see the date and price of the next possible call.
When this option is selected, only bonds that cannot be redeemed before their maturity date are shown.
A bond is considered liquid if, based on data from our partner brokers:
- At least 5 tradable units are available to buy and sell, and
- The difference between buy and sell prices is less than 2%.
Shows bonds with a purchase price below 100 (below face value).
If you buy a bond below 100 and hold it until maturity, it is usually repaid at 100.
The difference is a capital gain.
Example:
Buy at 95, receive 100 at maturity → +5 capital gain.
In some countries, capital gains can be used to offset previously realized investment losses.
Example:
An investor previously sold shares with a loss of 5.
He buys a bond at 95 and holds it to maturity.
The +5 capital gain can offset the earlier −5 loss, so no tax is paid on the gain.
This improves the net return.
Indicates whether the bond is callable by the issuer. For callable bonds, the date and price of the next call is shown.
The market parameters of the bond at which it can be sold at the time specified above.
The market parameters of the bond at which it can be purchased at the time specified above.
The annual yield differential between the bond and the corresponding bank deposit. The benchmark deposit rate used for comparison is sourced from fixed-term deposits in your designated home country, which can be updated in your Account settings.
A measure of a bond’s interest rate risk. It shows how much the price of the bond will fall or rise if the level of market interest rates changes.