Weekly bond digest: October 26 – November 1, 2026
Tech companies drove the bond market in the last week of October. Oracle's long-dated bonds bounced after it capped new fundraising, Intel's bonds fell after a weak outlook, and Microsoft raised $25 billion in its first bond sale in nearly a decade.
Government bond yields fell in the US, the UK and Germany. The Fed and the ECB held rates, and the UK budget brought no surprises. Next week, the Bank of England is expected to raise rates to 4%.
Yield Curves
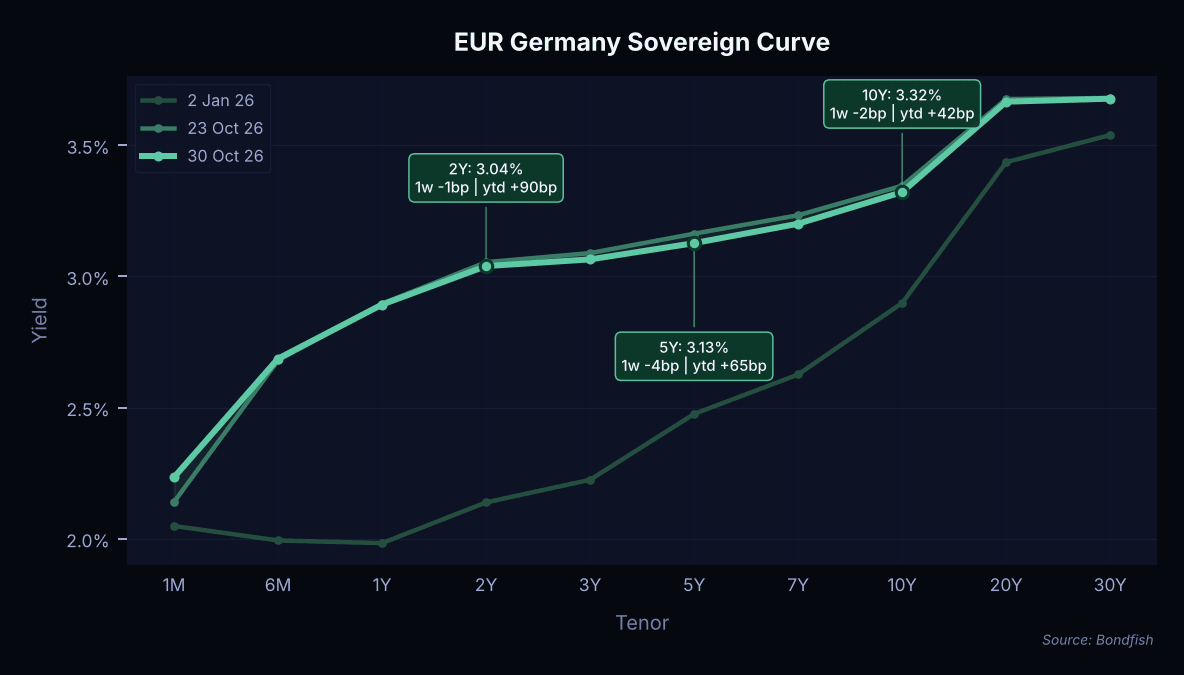
German yields edged lower, with the 10-year down 2 basis points to 3.32%. The European Central Bank kept rates on hold but still pointed to a hike in December. For the first time since March, it also said that higher borrowing costs could weigh on growth, which markets read as a slightly softer message. News that Christine Lagarde will leave the ECB early, after February 2027, added some uncertainty.
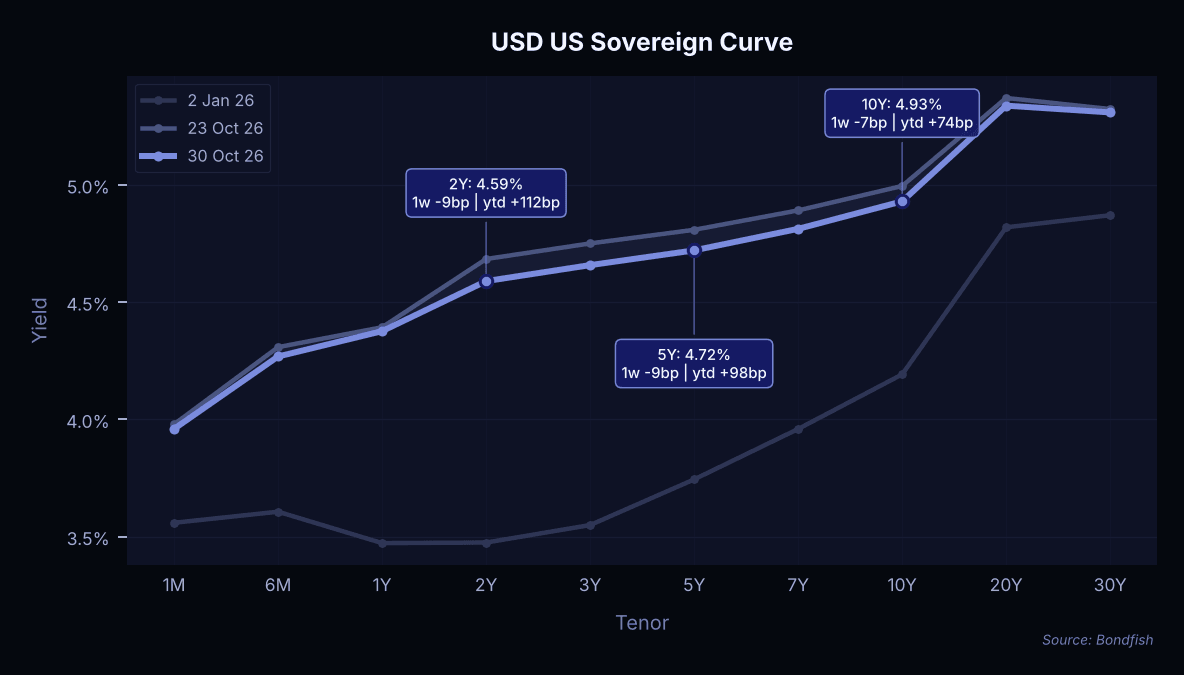
US Treasuries rallied, with 2-year and 5-year yields down about 9 basis points and the 10-year down 7 to 4.93%. The Fed held rates at 3.75% to 4%. Its statement left the door open to a December hike, but Chair Warsh sounded less hawkish at the press conference, saying tighter financial conditions are already doing part of the Fed's job. He also said the Fed will hold fewer policy votes in 2027 and 2028. Investors took that as less transparency and asked for a bit more to hold long bonds, so the 30-year yield barely moved. Weakness in tech stocks also pushed money into Treasuries.
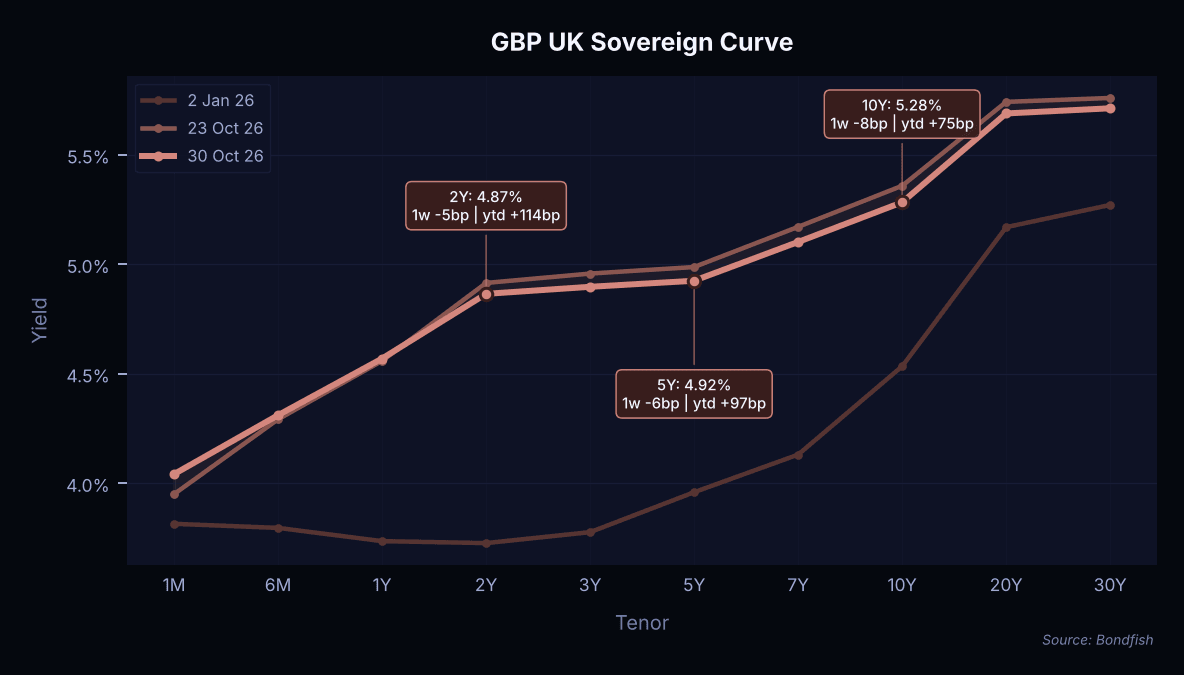
UK gilt yields fell, with the 10-year down 8 basis points to 5.28%. Chancellor Healey's budget on Wednesday held no big surprises. He stuck to the government's commitment to fiscal discipline, so investors saw no new reason to demand higher yields on UK debt. Next week, the Bank of England is widely expected to raise rates to 4%.
For long-term investors who can live with short-term swings, medium-term government bonds of around 5 to 10 years still offer attractive yields, while weak tech stocks and the Middle East conflict argue for caution in the near term.
Top gainers
Oracle bonds took most of the top spots, with long-dated issues up as much as 3.8%. At its investor day on October 28, Oracle said its free cash flow should turn positive in 2028 and capped new fundraising at $20 billion through fiscal 2030, split evenly between debt and shares. That eased worries about how it will pay for its AI data centers. Surgery Center bonds rose 4.2% after a Bon Secours Mercy Health affiliate agreed to buy its parent, Surgery Partners, in a $5.7 billion deal. Heimstaden's 2031 bond led the table with a 6.3% gain after third-quarter results showed lower debt relative to property values and better interest cover.
| Name | Cur | Price change 1w (%) |
Yield | Risk Level |
|---|---|---|---|---|
| Heimstaden 7.361% Jan 2031 | EUR | 6,33% | 10,52% | |
| Surgery Cntr 7.25% Apr 2032 | USD | 4,23% | 5,83% | |
| Oracle 5.5% Sep 2064 | USD | 3,78% | 8,32% | |
| Oracle 5.95% Sep 2055 | USD | 3,71% | 8,26% | |
| Oracle 5.375% Sep 2054 | USD | 3,61% | 8,25% | |
| Oracle 3.6% Apr 2040 | USD | 3,59% | 7,78% | |
| Oracle 5.55% Feb 2053 | USD | 3,31% | 8,32% | |
| Oracle 6% Aug 2055 | USD | 3,00% | 8,31% | |
| Paramount Global 5.5% May 2033 | USD | 2,73% | 10,89% | |
| Oracle 4.5% Jul 2044 | USD | 2,71% | 8,07% |
Top losers
Intel bonds fell as much as 2.7% after the chipmaker's third-quarter results on October 29. Its outlook disappointed and PC demand slumped, sending its shares down more than 20%. The news pushed the cost of insuring US tech companies' debt against default to record highs. Intrum's 2027 bond lost 3.1% in the week after third-quarter results came in below forecasts, including a SEK 1.5 billion write-off on its German business. Navient's 2030 bond also slipped 2.6%.
| Name | Cur | Price change 1w (%) |
Yield | Risk Level |
|---|---|---|---|---|
| Intrum Investmen 7.75% Sep 2027 | EUR | -3,08% | 12,08% | |
| Intel 4.1% May 2047 | USD | -2,73% | 6,93% | |
| Intel 3.734% Dec 2047 | USD | -2,73% | 6,90% | |
| Navient 9.375% Jul 2030 | USD | -2,60% | 10,79% | |
| Intel 5.7% Feb 2053 | USD | -2,52% | 6,97% | |
| Intel 5.9% Feb 2063 | USD | -2,24% | 7,00% | |
| Intel 4.9% Aug 2052 | USD | -2,18% | 6,91% | |
| Intel 5.05% Aug 2062 | USD | -2,11% | 6,97% | |
| Intel 4.9% Jul 2045 | USD | -1,91% | 6,84% | |
| Ford Motor 9.98% Feb 2047 | USD | -1,57% | 7,80% |
Rating changes
Note: only long-term senior unsecured ratings were taken into account.
S&P raised Telecom Italia to BBB-, returning the Italian phone company to investment grade. S&P also upgraded Synopsys to BBB+. On the downside, S&P cut Whirlpool by two notches to B, and Thames Water slipped further into junk at CCC-. Moody's downgraded Senegal to Ca from Caa2, a level that signals the country is close to default.
| Issuer | Agency | Change |
|---|---|---|
| Asia Commercial Bank | Fitch | |
| Cable One | S&P | |
| CAP | S&P | |
| Charter Hall Prime Industrial Fund | Moody's | |
| China Longyuan Power | Moody's | |
| Citadel | S&P | |
| Convatec | S&P | |
| Dongxing Securities Hong Kong | Fitch | |
| Eldorado Brasil Celulose | Fitch | |
| Emeria | S&P | |
| Energa | Moody's | |
| Flamingo Lux | S&P | |
| Grupo Aeromexico | S&P | |
| HelloFresh | S&P | |
| Mitchell Topco | S&P | |
| NCBA | Fitch | |
| Nexa Resources | S&P | |
| Ontex | S&P | |
| Oriental Securities | Fitch | |
| Republic of Senegal | Moody's | |
| Republic of Zambia | Moody's | |
| Synopsys | S&P | |
| Telecom Italia | S&P | |
| Thames Water | S&P | |
| Vietnam Technological & Commercial Joint Stock Bank | Fitch | |
| Whirlpool | S&P | |
| Win Waste Innovations | S&P | |
| Zorlu Enerji | Fitch |
New issues
Big tech set the tone in the new-issue market. Microsoft raised $25 billion across ten bonds, its first bond sale in nearly a decade, and its AAA rating attracted strong demand even as investors grow wary of AI borrowing. Procter & Gamble sold $4 billion of bonds, including a 30-year bond priced just 0.6 percentage points above Treasuries, a level not seen since 2003. Heavy tech borrowing pushed global investment-grade and high-yield bond sales to a yearly record, with two months still to go. In Europe, the European Union raised €32 billion across six bonds and Italy sold €8 billion of 12-year bonds.
The table shows only bonds sold in small lots, with a minimum investment of 2,000 or less in the bond’s currency. Deals sold only in large blocks, or only to big US institutional investors, are left out.
| Issuer | Size | Term | Yield | Risk Level |
|---|---|---|---|---|
| American Express Credit | USD 3,0bn | 4–8Y | 5,4–5,8% | |
| ISIN (CUSIP)US025816EW58…US025816EX32 | ||||
| Asian Development Bank | USD 2,0bn | 10Y | 4,7% | |
| ISIN (CUSIP)US045167GT47 | ||||
| Asian Infrastructure Investment Bank | USD 0,69bn | 5Y | FLOAT, +34bp | |
| ISIN (CUSIP)XS3555722852 | ||||
| Blackstone Reg Finance | USD 1,1bn | 5–7Y | 5,7–5,9% | |
| ISIN (CUSIP)US092914AD23…US092914AE06 | ||||
| CBRE Group | USD 1,0bn | 5–10Y | 5,8–6,2% | |
| ISIN (CUSIP)12505BAN0…12505BAP5 | ||||
| CMS Energy | USD 1,0bn | 31Y | 6,8% | |
| ISIN (CUSIP)US125896CB49 | ||||
| Deutsche Telekom | EUR 1,9bn | 4–12Y | 4,0–4,7% | |
| ISIN (CUSIP)XS3528376877…XS3528381281 | ||||
| European Investment Bank | EUR 5,0bn | 5Y | 3,3% | |
| ISIN (CUSIP)EU000A4E0ET7 | ||||
| European Investment Bank | USD 4,0bn | 5Y | 4,4% | |
| ISIN (CUSIP)US298785KU94 | ||||
| European Stability Mechanism | EUR 1,0bn | 3Y | 3,5% | |
| ISIN (CUSIP)EU000A2SCA15 | ||||
| European Union | EUR 32,0bn | 4–30Y | 2,9–4,5% | |
| ISIN (CUSIP)EU000A4EXVK3…EU000A4E0866 | ||||
| Federal Republic of Germany | EUR 4,0bn | 30Y | 3,8% | |
| ISIN (CUSIP)DE000BU2D012 | ||||
| Franklin BSP Capital | USD 0,30bn | 3Y | 7,5% | |
| ISIN (CUSIP)USU3510AAD38 | ||||
| Free and Hanseatic City of Hamburg | EUR 0,50bn | 10Y | 3,7% | |
| ISIN (CUSIP)DE000A3MQTV9 | ||||
| General Motors | USD 1,2bn | 3Y | 5,6% | |
| ISIN (CUSIP)US37045XFS09 | ||||
| Instituto de Crédito Oficial | EUR 0,50bn | 5Y | 3,7% | |
| ISIN (CUSIP)XS3526683621 | ||||
| KeyCorp | USD 1,0bn | 6Y | 5,9% | |
| ISIN (CUSIP)US49326EES81 | ||||
| KfW | EUR 8,0bn | 3–6Y | 3,0–3,5% | |
| ISIN (CUSIP)XS3480769069…XS3166721913 | ||||
| Kingdom of Spain | EUR 4,0bn | 21Y | 4,3% | |
| ISIN (CUSIP)ES0000012S30 | ||||
| L-Bank Baden-Württemberg | USD 1,5bn | 3Y | 4,4% | |
| ISIN (CUSIP)XS3455113186 | ||||
| Microsoft | USD 25,0bn | 2–40Y | 4,9–6,4%; FLOAT | |
| ISIN (CUSIP)US594918CZ59…US594918DG69 | ||||
| Procter & Gamble | USD 4,0bn | 5–30Y | 5,1–5,9% | |
| ISIN (CUSIP)US742718GU73…US742718GX13 | ||||
| Public Storage | USD 0,50bn | 10Y | 5,8% | |
| ISIN (CUSIP)US74464AAJ07 | ||||
| Republic of Finland | EUR 4,0bn | 7Y | 3,3% | |
| ISIN (CUSIP)FI4000609516 | ||||
| Republic of Italy | EUR 8,0bn | 12Y | 4,5% | |
| ISIN (CUSIP)IT0005733099 | ||||
| Ryder System | USD 0,70bn | 5Y | 5,6% | |
| ISIN (CUSIP)US78355HLJ67 | ||||
| Southwest Airlines | USD 0,65bn | 5Y | 6,1% | |
| ISIN (CUSIP)US844741BP21 | ||||
| State of Baden-Württemberg | EUR 0,60bn | 10Y | 3,7% | |
| ISIN (CUSIP)DE000A3H26C0 | ||||
| State of Berlin | EUR 1,2bn | 10Y | 3,5% | |
| ISIN (CUSIP)DE000A5H3DJ1 | ||||
| State of Brandenburg | EUR 0,75bn | 4Y | 3,7% | |
| ISIN (CUSIP)DE000A351UV1 | ||||
| State of Hesse | EUR 1,2bn | 5Y | 3,3% | |
| ISIN (CUSIP)DE000A1RQFH0 | ||||
| State of North Rhine-Westphalia | EUR 1,5bn | 7Y | 3,3% | |
| ISIN (CUSIP)DE000NRW0QR6 | ||||
| State of Thuringia | EUR 0,65bn | 8Y | 3,7% | |
| ISIN (CUSIP)DE000A5GS4C0 | ||||
| Texas Instruments | USD 2,0bn | 2–10Y | 5,1–5,8% | |
| ISIN (CUSIP)US882508CN25…US882508CR39 | ||||
| United Kingdom | GBP 9,0bn | 12–29Y | 2,1–5,8% | |
| ISIN (CUSIP)GB00BMY62Z61…GB00BT7J0241 | ||||
| United Rentals | USD 1,0bn | 10Y | 6,2% | |
| ISIN (CUSIP)US911365BV58 | ||||
| World Bank (IBRD) | GBP 1,2bn | 6Y | 4,7% | |
| ISIN (CUSIP)XS3487947957 | ||||
This article does not constitute investment advice or personal recommendation. Investments in securities and other financial instruments always involve the risk of loss of your capital. Past performance is not a reliable indicator of future results. Bondfish does not recommend using the data and information provided as the only basis for making any investment decision. You should not make any investment decisions without first conducting your own research and considering your own financial situation.