 Premium
Bekaert is the largest European maker of steel wire for car tyres and one of the largest in the world, with about one in four tyres worldwide built on its steel cord. We highlight its unrated bond's 4,2% euro yield, with only one year to maturity in October 2027. This short duration might be attractive for investors expecting further interest rate increases.
Publication date: 11-10-2026
Bekaert turns steel into wire and cord at about 65 plants in about 20 countries. Founded in 1880 in Belgium as a maker of barbed wire, it now buys 1,9 million tonnes of steel rod a year. Tyre cord is half of sales, and the rest is wire, ropes and steel fibres for power cables, construction, mining and farming. Sales are 40% in Europe, the Middle East and Africa, a third in Asia and 20% in North America. The founding family's foundation holds about 40% of the shares, and the rest free float trades on Euronext Brussels (BEKB).
Sales are under pressure from lower steel prices and weaker demand in Europe and North America. Revenue is €3,7bn, a quarter below 2021, with flat volumes since 2024. Selling prices follow the steel price, and competition from Asian producers limits Bekaert's pricing ability. In Europe and North America tyre makers lose share to Asian imports and builders buy fewer steel fibres. Growth comes from tyre makers in Asia and from wire for power and data cables, now 13% of sales. Asia also has most of the production, with half of Bekaert's staff and over half of its energy use, mostly in China.
Margins have fallen since 2021, but free cash flow stays positive. The adjusted EBITDA margin (excluding write-downs of assets) decreased to 11-12% from 14% in 2021. In 2025 Bekaert cut plant capacity in Italy, Belgium and China, sold its Latin American wire plants and booked €162m of write-downs and restructuring charges. Free cash flow after interest and CAPEX has been €120-250m a year since 2021. Management expects flat sales and a slightly lower margin in 2026.
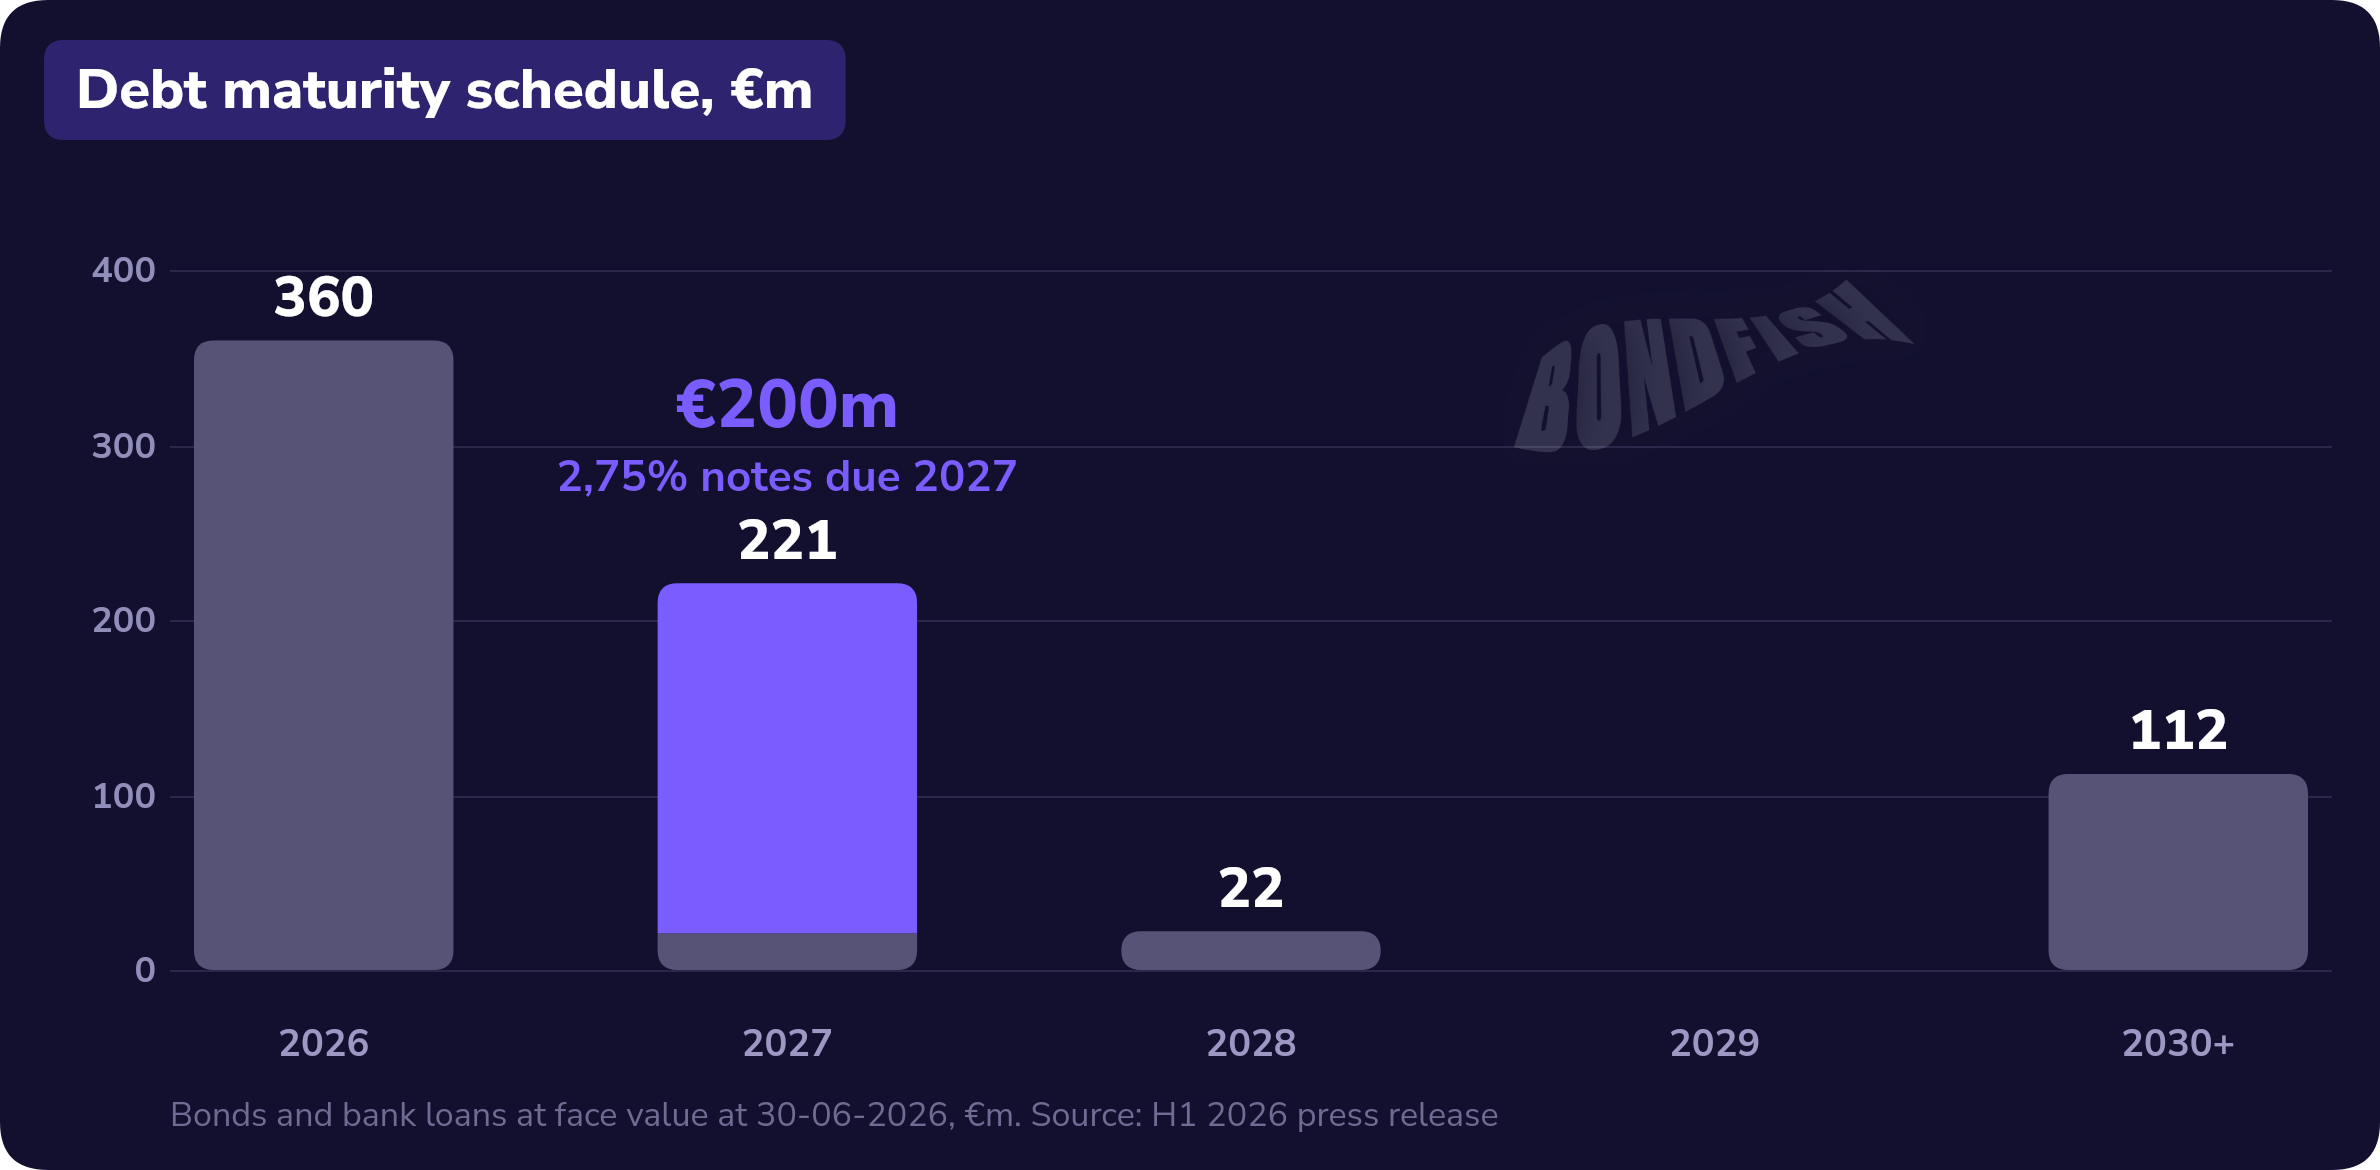
Indebtedness is low, with Net Debt/EBITDA of 1,2× at June 2026. Debt is €0,8bn (incl. leases) against €0,4bn of cash and includes €0,3bn of bank loans and leases at the plant subsidiaries. Debt fell from €1,2bn in 2022 to €0,7bn in 2025, repaid from operating cash flows. Its €1bn of plants and equipment in the balance sheet are unpledged. Cash on hand covers the €0,4bn of debt maturing before the notes. In July 2026 Bekaert borrowed €250m to refinance maturing 2026 debt (€360m total).
Payments to shareholders are aggressive. Bekaert paid €0,7bn in dividends and buybacks in 2022-2025, about all of its free cash flow after interest and CAPEX. The €96m dividend paid in 2026 was larger than the 2025 net profit. Dividends, buybacks and two minor acquisitions raised debt by about €90m in the first half of 2026.
Bekaert and the notes are not rated by the big three rating agencies. The company funds itself with retail bonds, private placements and bank loans.
The 2,75% notes mature in October 2027, with €200m outstanding. They are unsecured obligations of the parent company NV Bekaert SA and are not guaranteed by the subsidiaries that run the plants. The notes rank equally with the parent's other bonds and loans and behind an estimated €0,3bn of bank loans and leases at the subsidiaries. Under the change-of-control covenant, bondholders can sell the notes back at 101% if a bidder other than the family foundation acquires more than half the shares.
as of 30-06-2026 EUR bn
| Column 1 | Column 2 | Column 3 | Column 4 | Column 5 | Column 6 |
|---|---|---|---|---|---|
| Assets | 3,9 | EBITDA Margin | 9 % | CFO/Debt | 0,4 |
| Revenue | 3,6 | Net debt | 0,4 | FCF | 0,2 |
| EBITDA | 0,3 | Net Debt/EBITDA | 1,2× | Equity | 2,1 |
| Net Profit | 0,1 | EBITDA/Interest | 14,1× | Debt/Equity | 0,4× |
All data and information is provided “as is” for informational purposes only, and is not intended for trading purposes or financial, investment, tax, legal, accounting or other advice. Please consult your broker or financial representative to verify pricing before executing any trade. Bondfish is not an investment adviser, financial adviser or a broker. None of the data and information constitutes investment advice nor an offering, recommendation or solicitation by Bondfish to buy, sell or hold any security or financial product, and Bondfish makes no representation (and has no opinion) regarding the advisability or suitability of any investment. Mention of specific financial products or operations does not constitute an endorsement by Bondfish.
The financial products or operations referred to in such data and information may not be suitable for your investment profile and investment objectives or expectations. It is your responsibility to consider whether any financial product or operation is suitable for you based on your interests, investment objectives, investment horizon and risk appetite. Bondfish shall not be liable for any damages arising from any operations or investments in financial products referred to within. Bondfish does not recommend using the data and information provided as the only basis for making any investment decision.
This data is not updated in real time and represents the prices available at the end of the previous trading day. Bondfish does not verify any data and disclaims any obligation to do so. Bondfish expressly disclaims the accuracy, adequacy, or completeness of any data and shall not be liable for any errors, omissions or other defects therein, delays or interruptions in such data, or for any actions taken in reliance thereon. Bondfish shall not be liable for any damages relating to your use of the information provided herein.
Past performance is not a reliable indicator of future results.