Weekly bond digest: August 31 – September 6, 2026
Yield Curves
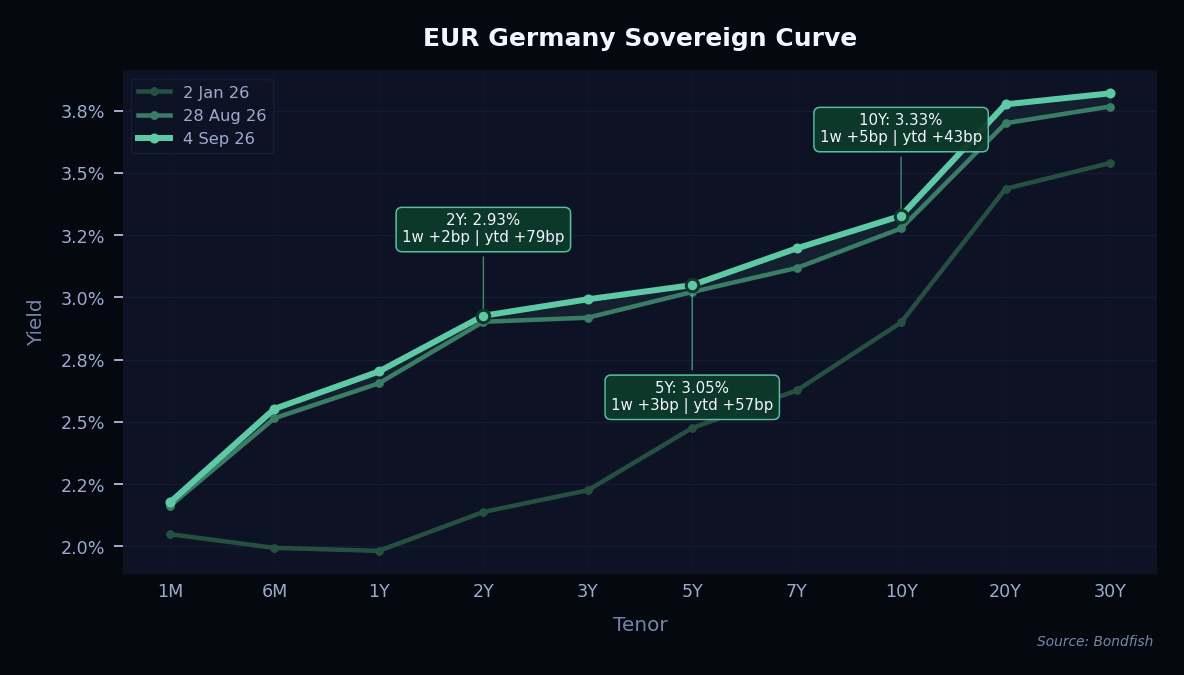
German yields drifted higher this week, adding about 4 to 6 basis points along the curve, with the 10-year Bund near 3.34%. The main driver was caution ahead of the US Federal Reserve meeting in two weeks, which investors see as close to a coin-flip between a rate rise and no change. Closer to home, European gas prices at a three-year high and renewed political and budget uncertainty in France added to the upward pressure on yields.
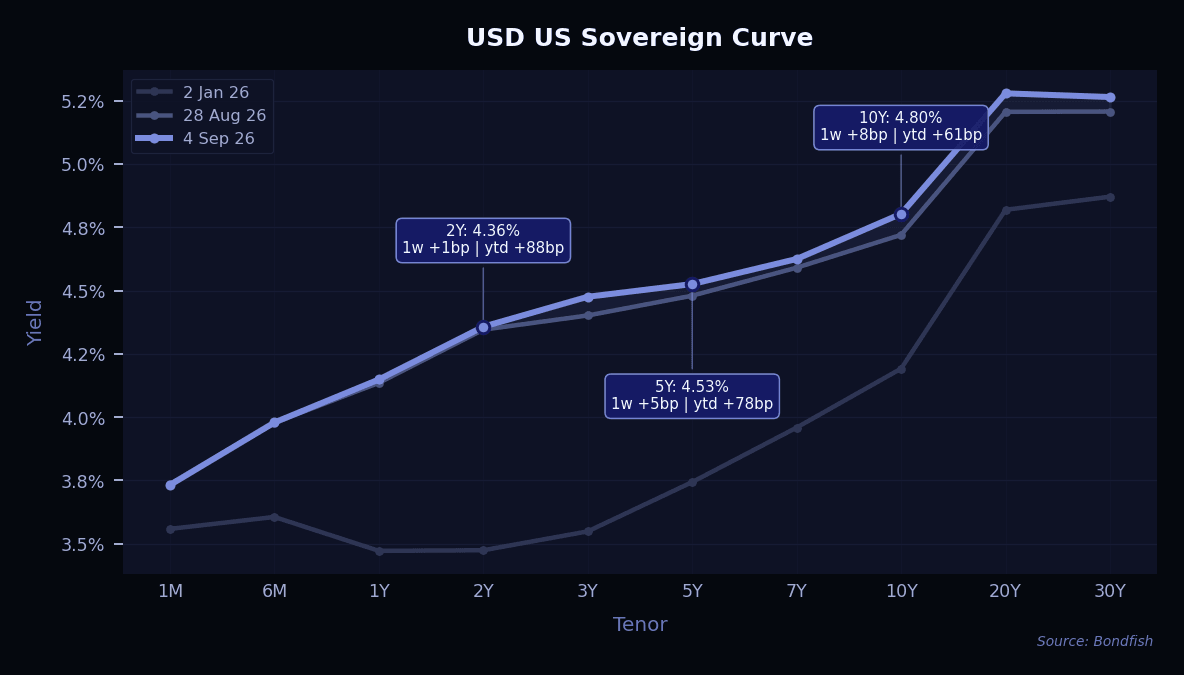
US Treasury yields rose in the belly and long end, with the 5- to 10-year area up about 6 basis points and the 10-year near 4.78%. Very short maturities barely moved. Markets are now pricing a real chance the Fed raises rates at its coming meeting, an unusual stance this late in the cycle, while a weaker dollar kept upward pressure on longer-term yields.
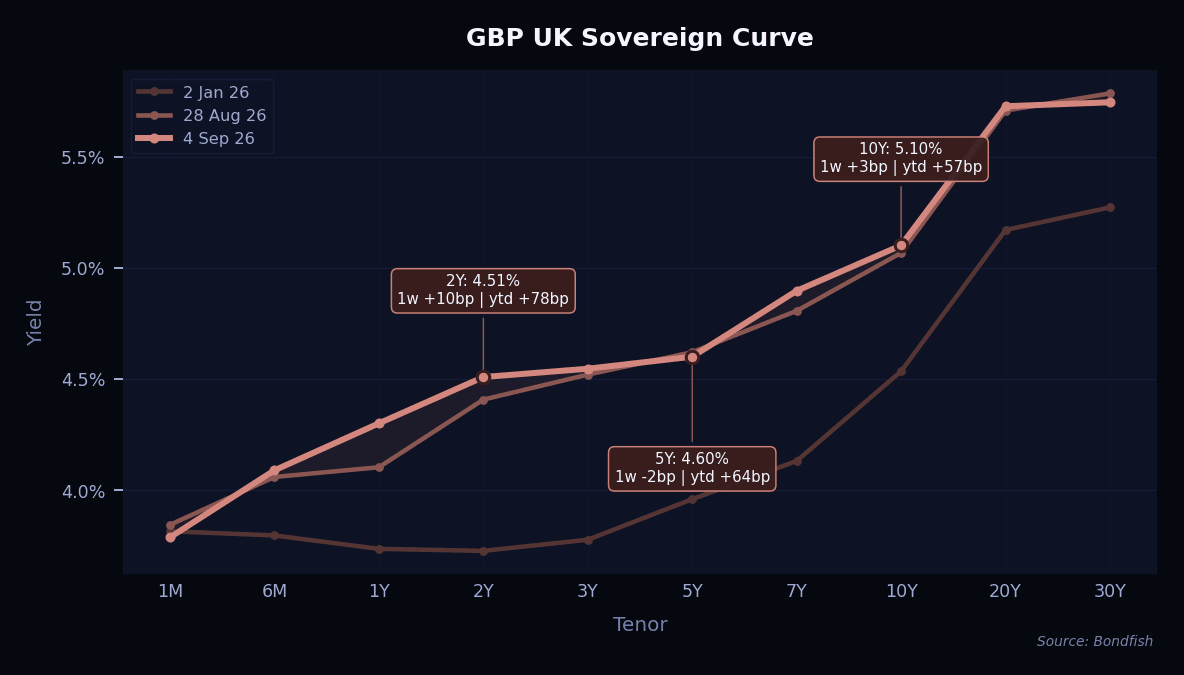
UK yields jumped at the front of the curve, with the 1-year up more than 20 basis points and the 2-year up 12, as investors pushed back the timing of the next Bank of England rate cut. Longer maturities were little changed to slightly lower, leaving the 10-year Gilt around 5.13%. The result was a flatter curve, with short-dated yields catching up to longer ones.
With investment-grade spreads already close to fair value and the Fed decision looming, the prevailing view favours higher-quality, shorter-dated bonds and a lighter tilt toward the most rate-sensitive long maturities.
Top gainers
Last week's biggest gainers were mostly longer-dated US corporate bonds. ONEOK led the way across several of its issues after both S&P and Fitch put the pipeline operator on track for an upgrade, which tightened its borrowing spreads. FMC and Jefferies Financial also rose, and higher-risk names such as Coronado Finance climbed as riskier credit found buyers.
| Name | Cur | Price change 1w(%) |
Yield | Risk Level |
|---|---|---|---|---|
| ONEOK 3.95% Mar 2050 | USD | 3,10% | 6,20% | |
| Jefferies Fincl 6% Sep 2036 | USD | 2,28% | 6,46% | |
| Motorola 5.22% Oct 2097 | USD | 2,13% | 6,77% | |
| Coronado Finance 9.25% Oct 2029 | USD | 1,95% | 14,42% | |
| FMC 4.5% Oct 2049 | USD | 1,90% | 7,60% | |
| ONEOK 5.7% Nov 2054 | USD | 1,83% | 6,32% | |
| ONEOK 5.45% Jun 2047 | USD | 1,79% | 6,24% | |
| FMC 6.375% May 2053 | USD | 1,73% | 8,14% | |
| ONEOK 4.85% Feb 2049 | USD | 1,67% | 6,23% | |
| Ineos Quattro Fin 2 6.75% Apr 2030 | EUR | 1,66% | 12,53% |
Top losers
The week's biggest fallers were almost all long-dated US utility bonds. Southern California Edison accounted for most of the list, with San Diego Gas and a long FedEx bond also lower, as the rise in long-term Treasury yields pushed down prices on these high-quality, long-maturity issues. The exception was Medical Properties (MPT), a higher-risk name that fell on its own credit concerns rather than on interest rates.
| Name | Cur | Price change 1w(%) |
Yield | Risk Level |
|---|---|---|---|---|
| San Diego Gas 3.95% Nov 2041 | USD | -5,14% | 6,19% | |
| Nature 3.957% Mar 2052 | USD | -4,46% | 5,78% | |
| MPT Opt Partner 4.625% Aug 2029 | USD | -4,33% | 16,36% | |
| FedEx 4.95% Oct 2048 | USD | -4,02% | 6,16% | |
| Southern Ca 5.45% Jun 2052 | USD | -3,43% | 6,68% | |
| Southern Ca 6.2% Sep 2055 | USD | -3,40% | 6,71% | |
| Southern Ca 5.7% Mar 2053 | USD | -3,33% | 6,75% | |
| Southern Ca 4.05% Mar 2042 | USD | -3,28% | 6,46% | |
| Southern Ca 5.875% Dec 2053 | USD | -3,27% | 6,71% | |
| Southern Ca 4.65% Oct 2043 | USD | -3,23% | 6,62% |
Rating changes
Note: only long-term senior unsecured ratings were taken into account.
On the upgrade side, Teva Pharmaceutical returned to investment grade, and Portugal was lifted one notch higher within the single-A range. Smith & Nephew and two Kazakh energy names, KazMunayGas and Tengizchevroil, also moved up. Downgrades were led by Leggett & Platt, which slipped from investment grade into high yield, while Getty Images and CDK Global were cut deeper into speculative territory. Overall the week brought more upgrades than downgrades.
| Issuer | Agency | Change |
|---|---|---|
| Acacium | S&P | SD → CCC+ |
| Advancion | S&P | CCC → CC |
| Alliance Laundry | S&P | B+ → BB- |
| Aramark | S&P | BB → BB+ |
| Banco BTG Pactual Chile | Fitch | BBB → BBB+ |
| Bank CenterCredit | S&P | BB → BB+ |
| CDK Global | S&P | B- → CCC |
| DRW | Moody's | Ba3 → B1 |
| Energia | Fitch | BB → BB+ |
| Getty Images | S&P | CCC+ → CCC |
| Hangzhou Shangcheng Urban Construction | Fitch | BBB- (new) |
| Hayward | S&P | BB → BB+ |
| ICS US | S&P | SD → CCC+ |
| KazMunayGas National | S&P | BBB- → BBB |
| Korea Railroad | Moody's | Aa3 → Aa2 |
| Leggett & Platt | Fitch | BBB- → BB+ |
| Pitney Bowes | S&P | B+ → BB- |
| Platform Housing | S&P | A+ → A |
| Plymouth Community Homes | S&P | A+ → A |
| Portugal | Fitch | |
| Secure Waste Infrastructure | S&P | B+ → BB |
| Smith & Nephew | Moody's | Baa2 → Baa1 |
| Tengizchevroil | S&P | BBB- → BBB |
| Teva Pharmaceutical Industries | S&P | BB+ → BBB- |
| Vesta | Fitch | BBB- → BBB |
| WestJet Airlines | S&P | B → B- |
New issues
New bond sales surged as issuers returned from the summer break, with banks, development agencies and government-backed borrowers leading the way. The European Investment Bank priced the largest deal at 5 billion euros, followed by sizeable sales from Saudi Arabia's sukuk programme, TenneT, Bank Gospodarstwa Krajowego and Korea Development Bank. Most of the supply came in euros and US dollars across short and medium maturities, with a handful of banks, including Commerzbank and Koninklijke KPN, selling perpetual bonds. The mix of senior, covered and subordinated deals is typical of the first full week after the summer lull.
| Issuer | Size | Term | Yield | Risk Level |
|---|---|---|---|---|
| 3M | EUR 1,0bn | 2–5Y | 3,5–3,9% | |
| ISIN (CUSIP)XS3460877650…XS3460877734 | ||||
| Agence Centrale Des Organismes De Securite Sociale | EUR 2,0bn | 2Y | 3,3% | |
| ISIN (CUSIP)FR0129816759 | ||||
| Al Rajhi Sukuk | USD 0,60bn | 10Y | 6,2% | |
| ISIN (CUSIP)XS3489932593 | ||||
| ANB Tier 1 Sukuk Company | USD 0,75bn | PERP | 6,5% | |
| ISIN (CUSIP)XS3482759688 | ||||
| Argenta Spaarbank | EUR 0,33bn | 5Y | 4,1% | |
| ISIN (CUSIP)BE6377154834 | ||||
| Asian Infrastructure Investment Bank | USD 2,0bn | 3Y | 4,5% | |
| ISIN (CUSIP)US04522KAU07 | ||||
| Autobahnen Und Schnellstrassen Finanzierungs | EUR 0,50bn | 5Y | 3,3% | |
| ISIN (CUSIP)XS3496782338 | ||||
| Autostrade Per L'Italia | EUR 0,75bn | 7Y | 4,4% | |
| ISIN (CUSIP)XS3496775985 | ||||
| Banca Monte Dei Paschi Di Siena | EUR 0,50bn | 10Y | 4,7% | |
| ISIN (CUSIP)IT0005730202 | ||||
| Banco Santander Totta | EUR 0,50bn | 3Y | 3,4% | |
| ISIN (CUSIP)PTBSRWOM0026 | ||||
| Bangkok Bank PCL | USD 0,45bn | 5Y | 5,3% | |
| ISIN (CUSIP)USY0616GAB96 | ||||
| Bank Gospodarstwa Krajowego | USD 2,5bn | 8–12Y | 5,6–6,0% | |
| ISIN (CUSIP)XS3479197306…XS3479197488 | ||||
| Bank Of Montreal | USD 1,2bn | 4Y | 5,1% | |
| ISIN (CUSIP)06368MY99 | ||||
| Boels Topholding | EUR 0,40bn | 6Y | 5,1% | |
| ISIN (CUSIP)XS3478193363 | ||||
| BPCE | GBP 0,40bn | 11Y | 6,3% | |
| ISIN (CUSIP)FR001401AQD7 | ||||
| Bureau Veritas | EUR 0,70bn | 8Y | 4,2% | |
| ISIN (CUSIP)FR001401ARS3 | ||||
| Canadian Imperial Bank Of Commerce | GBP 0,85bn | 5Y | FLOAT, +55bp | |
| ISIN (CUSIP)XS3496762819 | ||||
| Capri Global Capital | USD 0,30bn | PERP | 7,5% | |
| ISIN (CUSIP)USY1R30AAA11 | ||||
| Cassa Di Risparmio Di Bolzano | EUR 0,25bn | 5Y | 3,6% | |
| ISIN (CUSIP)IT0005730160 | ||||
| Ceska Sporitelna | EUR 0,50bn | 5Y | 3,6% | |
| ISIN (CUSIP)XS3498880254 | ||||
| Commerzbank | EUR 0,75bn | PERP | 6,3% | |
| ISIN (CUSIP)DE000CZ45WE9 | ||||
| Compagnie De Financement Foncier | EUR 1,0bn | 10Y | 3,9% | |
| ISIN (CUSIP)FR001401AQT3 | ||||
| Compass Group | EUR 0,25bn | 9Y | 4,1% | |
| ISIN (CUSIP)XS3232968985 | ||||
| Credit Agricole Public Sector | EUR 0,50bn | 6Y | 3,6% | |
| ISIN (CUSIP)FR001401ATK6 | ||||
| Development Bank Of Japan | EUR 0,55bn | 4Y | 3,5% | |
| ISIN (CUSIP)XS3465635830 | ||||
| Dexia | USD 1,0bn | 3Y | 4,8% | |
| ISIN (CUSIP)XS3498851586 | ||||
| DZ Hyp | EUR 0,50bn | 5Y | 3,3% | |
| ISIN (CUSIP)DE000A4DFKV8 | ||||
| East Japan Railway | EUR 0,50bn | 9Y | 4,1% | |
| ISIN (CUSIP)XS3471560519 | ||||
| Eika Boligkreditt | EUR 0,50bn | 10Y | 3,7% | |
| ISIN (CUSIP)XS3498888661 | ||||
| Erste Group Bank | EUR 1,5bn | 3–7Y | 3,6–4,0% | |
| ISIN (CUSIP)AT0000A3X172…AT0000A3X180 | ||||
| Eurobank | EUR 0,60bn | 7Y | 4,2% | |
| ISIN (CUSIP)XS3489639370 | ||||
| European Investment Bank | EUR 5,0bn | 5Y | 3,3% | |
| ISIN (CUSIP)EU000A4E0ET7 | ||||
| Exmar Netherlands | USD 0,15bn | 5Y | 7,8% | |
| ISIN (CUSIP)NO0013769299 | ||||
| GSK Capital | EUR 0,85bn | 2Y | FLOAT, +30bp | |
| ISIN (CUSIP)XS3480669517 | ||||
| Hamburg Commercial Bank | EUR 0,50bn | 3Y | 3,5% | |
| ISIN (CUSIP)DE000HCB0CN5 | ||||
| Hammerson | GBP 0,25bn | 7Y | 5,9% | |
| ISIN (CUSIP)XS3489989866 | ||||
| Hessen, State Of | EUR 1,2bn | 5Y | 3,3% | |
| ISIN (CUSIP)DE000A1RQFH0 | ||||
| HSBC Holdings | GBP 0,75bn | 9Y | 6,0% | |
| ISIN (CUSIP)XS3487885405 | ||||
| Hypo Vorarlberg Bank | EUR 0,50bn | 7Y | 3,6% | |
| ISIN (CUSIP)AT0000A3X0F3 | ||||
| ISDB Services | USD 1,5bn | 5Y | 4,8% | |
| ISIN (CUSIP)XS3498841942 | ||||
| Israel Discount Bank | EUR 0,50bn | 5Y | 3,9% | |
| ISIN (CUSIP)IL0012436585 | ||||
| Jinan Lixia Holding Group | USD 0,30bn | 3Y | 4,9% | |
| ISIN (CUSIP)XS3491287721 | ||||
| KIB Sukuk | USD 0,50bn | 5Y | 5,5% | |
| ISIN (CUSIP)XS3479250477 | ||||
| Koninklijke KPN | EUR 0,50bn | PERP | 4,8% | |
| ISIN (CUSIP)XS3485542800 | ||||
| Korea Development Bank | USD 2,0bn | 3–5Y | 4,6–4,8% | |
| ISIN (CUSIP)US500630ES35…US500630ET18 | ||||
| KSA Ijarah Sukuk | USD 3,2bn | 5–10Y | 5,3–5,6% | |
| ISIN (CUSIP)XS3498812844…XS3498813222 | ||||
| Kuntarahoitus | EUR 1,0bn | 5Y | 3,3% | |
| ISIN (CUSIP)XS3500110997 | ||||
| La Poste | EUR 0,50bn | 5Y | 3,9% | |
| ISIN (CUSIP)FR001401AQR7 | ||||
| M&G European Property Fund | EUR 0,50bn | 5Y | 4,2% | |
| ISIN (CUSIP)XS3498808651 | ||||
| Manulife Financial | USD 0,75bn | 15Y | 6,1% | |
| ISIN (CUSIP)US56501RAY27 | ||||
| National Bank Of Canada | USD 1,2bn | 3Y | 5,0% | |
| ISIN (CUSIP)US63307A3T08 | ||||
| Nationale-Nederlanden Bank | EUR 0,50bn | 5Y | 3,4% | |
| ISIN (CUSIP)NL0015074CE2 | ||||
| New Immo Holding | EUR 0,50bn | 6Y | 6,0% | |
| ISIN (CUSIP)FR001401ART1 | ||||
| Nexans | EUR 0,50bn | 5Y | 4,2% | |
| ISIN (CUSIP)FR001401APK4 | ||||
| Norddeutsche Landesbank | EUR 0,75bn | 7Y | 3,6% | |
| ISIN (CUSIP)DE000NLB57X5 | ||||
| Norinchukin Bank | USD 1,0bn | 5–10Y | 5,5–6,0% | |
| ISIN (CUSIP)USJ5901UAL64…USJ5901UAM48 | ||||
| Oberbank | EUR 0,30bn | 8Y | 3,7% | |
| ISIN (CUSIP)AT0000A3X198 | ||||
| OCBC Bank | USD 0,75bn | 3Y | 4,6% | |
| ISIN (CUSIP)XS3500115012 | ||||
| OPEC Fund For International Development | USD 1,0bn | 3Y | 4,7% | |
| ISIN (CUSIP)XS3487861562 | ||||
| Paccar Financial | USD 0,30bn | 3Y | 4,8% | |
| ISIN (CUSIP)69371RU79 | ||||
| Paccar Financial Europe | EUR 0,30bn | 3Y | 3,6% | |
| ISIN (CUSIP)XS3491333772 | ||||
| Raiffeisen Schweiz | EUR 0,50bn | 8Y | 4,3% | |
| ISIN (CUSIP)CH1579254470 | ||||
| Rothesay Life | GBP 0,50bn | 10Y | 7,0% | |
| ISIN (CUSIP)XS3495734744 | ||||
| Royal Bank Of Canada | USD 2,0bn | 5Y | 4,8% | |
| ISIN (CUSIP)USC7976PAM89 | ||||
| Sage Group | EUR 0,50bn | 6Y | 4,3% | |
| ISIN (CUSIP)XS3491327378 | ||||
| Swedish Export Credit | USD 1,2bn | 5Y | 4,6% | |
| ISIN (CUSIP)US01021NAJ19 | ||||
| Swiss Life Finance Ii | EUR 0,60bn | 20Y | 4,8% | |
| ISIN (CUSIP)CH1598620032 | ||||
| Tennet Netherlands | EUR 2,5bn | 7–15Y | 3,4–3,9% | |
| ISIN (CUSIP)XS3495741525…XS3495741798 | ||||
| UBS Group | EUR 1,8bn | 11Y | 4,5% | |
| ISIN (CUSIP)CH1598620016 | ||||
| UBS Group | GBP 1,0bn | 6Y | 5,6% | |
| ISIN (CUSIP)CH1598620024 | ||||
| UniCredit Bank Czech Republic And Slovakia | EUR 0,75bn | 5Y | 3,6% | |
| ISIN (CUSIP)XS3499982463 | ||||
| Volksbank Wien | EUR 0,50bn | 6Y | 4,6% | |
| ISIN (CUSIP)AT000B122460 | ||||
| Zuercher Kantonalbank | EUR 0,50bn | 6Y | 3,6% | |
| ISIN (CUSIP)CH1515238637 | ||||
This article does not constitute investment advice or personal recommendation. Investments in securities and other financial instruments always involve the risk of loss of your capital. Past performance is not a reliable indicator of future results. Bondfish does not recommend using the data and information provided as the only basis for making any investment decision. You should not make any investment decisions without first conducting your own research and considering your own financial situation.