Weekly bond digest: September 7 – September 13, 2026
Yield Curves
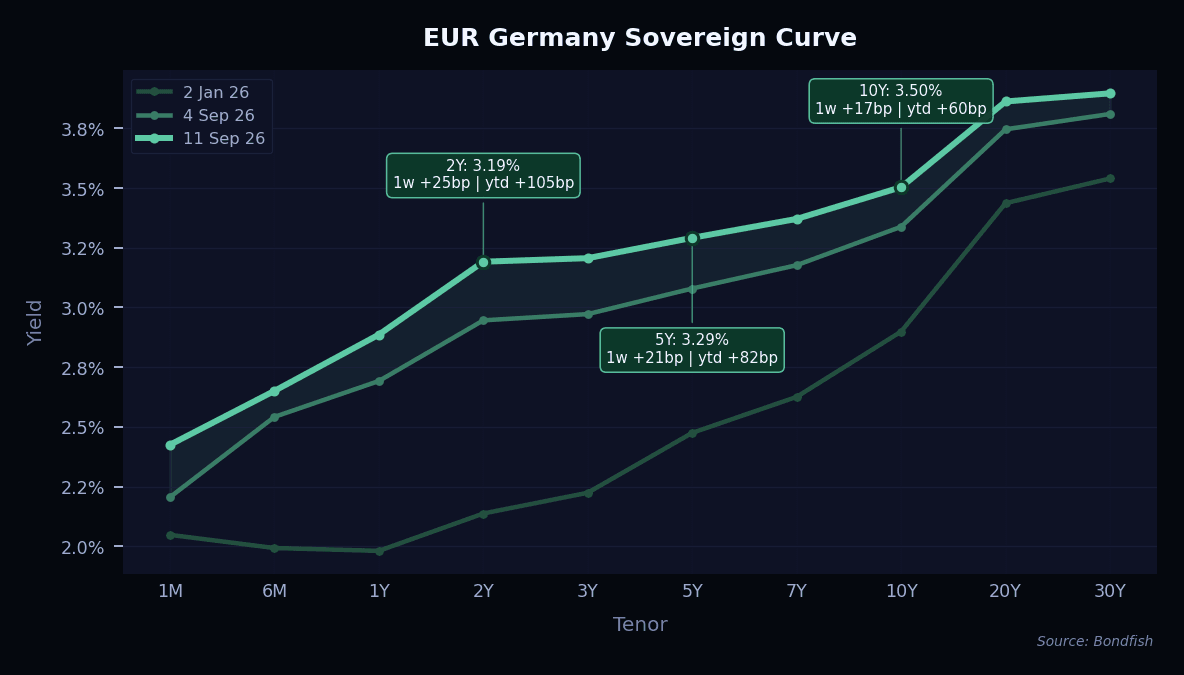
German yields climbed again this week, with the 10-year rising 17 basis points to around 3.50% and shorter maturities moving even more. The main push came from energy: natural gas and fuel prices have jumped, and investors worry those costs will keep inflation high, especially with tensions in the Middle East showing no sign of easing. The European Central Bank added to the move by raising rates to 2.5% and signalling it is not finished yet. German yields are now close to their highest levels since the 2008 financial crisis.
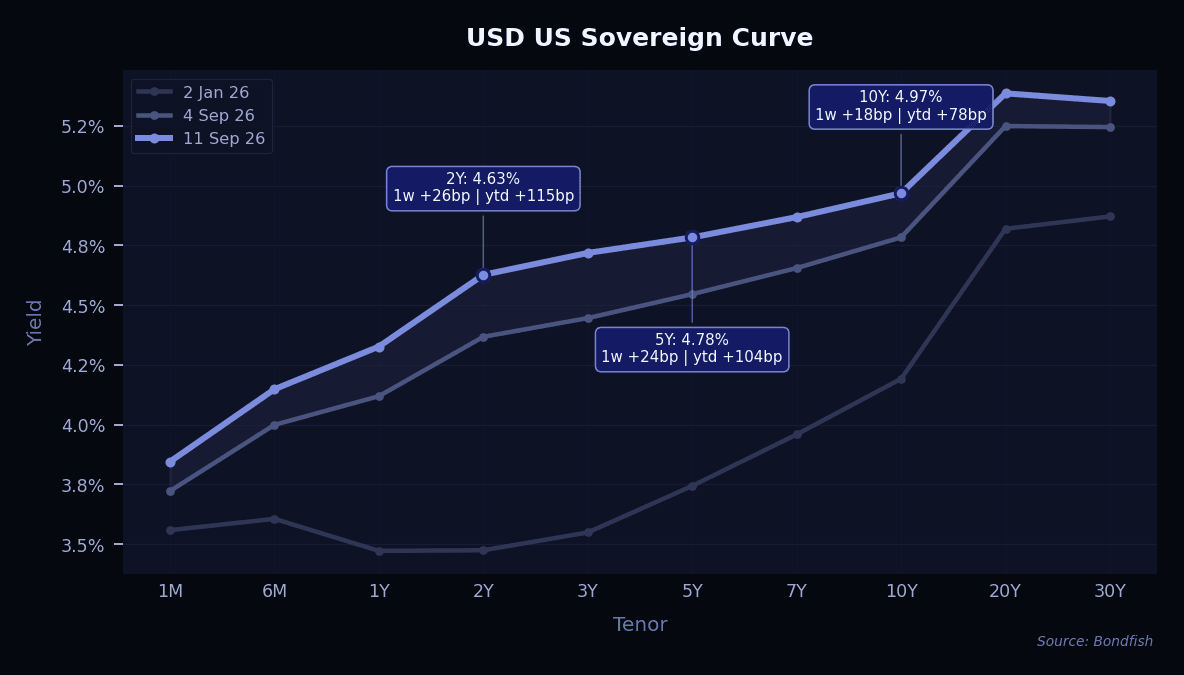
US Treasury yields rose across the board, led by shorter maturities, with the 10-year up 18 basis points to just under 5%. Fresh inflation data came in hot, and markets now expect the Federal Reserve to raise rates again at its meeting next week. Higher energy prices are feeding the same worry that inflation will prove hard to shake off. Two-year yields, which are the most sensitive to rate expectations, jumped 26 basis points on the week.
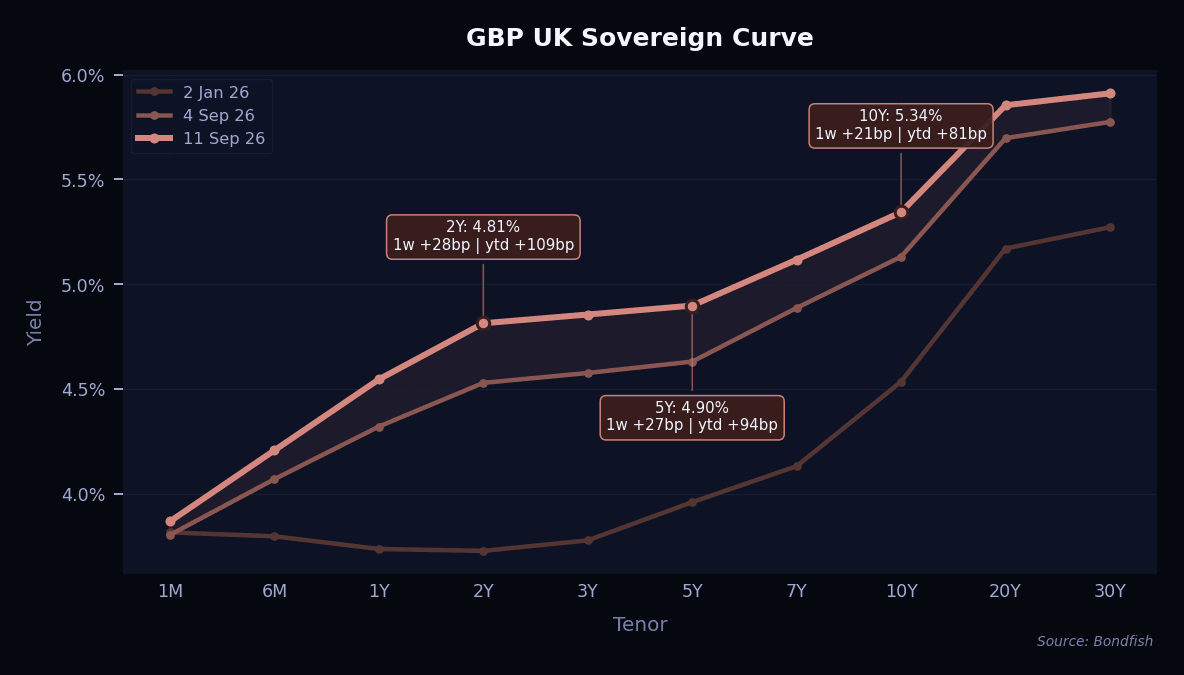
UK yields followed the same path, with the 10-year gilt up 21 basis points to 5.34% and the front end leading the way. Energy costs are a big part of the story here too, keeping inflation pressure alive. Markets are now pricing a large amount of Bank of England rate rises over the next year, which many see as more than the economy is likely to deliver. The Bank meets next week and is expected to hold rates steady for now.
After this sell-off, European bond yields look attractive by the standards of recent years, though caution is still warranted while energy prices and geopolitical risks stay elevated.
Top gainers
Even as government yields jumped, corporate credit stayed remarkably calm, and the biggest gainers were mostly higher-yielding bonds, where price swings tend to be larger. Pembroke Olive, Shearwater Geo, Waga BondCo and Ineos Quattro Finance all rose, helped by steady demand for extra yield. Enel, the Italian utility, also gained, along with UK transport group Mobico. The week showed how firm the appetite for credit remains, with corporate bond spreads sitting near their tightest levels in years.
| Name | Cur | Price change 1w(%) |
Yield | Risk Level |
|---|---|---|---|---|
| Pembroke Olive 11.5% Feb 2030 | USD | 4,49% | 3,26% | |
| Enel Fin 5.6% Mar 2031 | EUR | 2,63% | 3,35% | |
| Shearwater Geo 9.5% Apr 2029 | USD | 2,12% | 9,18% | |
| Waga BondCo 8.5% Jun 2030 | GBP | 1,92% | 13,70% | |
| Trinidad Tobago 5.875% May 2027 | USD | 1,65% | 4,08% | |
| Ineos Quattro Fin 2 6.75% Apr 2030 | EUR | 1,54% | 12,05% | |
| Shawbrook Group 12.25% Jan 2034 | GBP | 1,18% | 7,59% | |
| Oracle 3.95% Mar 2051 | USD | 1,04% | 7,40% | |
| Kftwrk Linth Lim 3% Apr 2048 | CHF | 0,97% | 1,87% | |
| Mobico Group 3.625% Nov 2028 | GBP | 0,91% | 6,10% |
Top losers
The biggest fallers were long-dated bonds, which lose the most value when yields rise. French government bonds dominated the list, hit by worries about the country's budget and political uncertainty that have pushed French borrowing costs well above Germany's. Long high-grade corporate bonds such as FedEx and FMC also dropped as yields climbed. Flowers Foods fell after its credit rating was cut, and Cogent Communications and Goodyear rounded out the decliners.
| Name | Cur | Price change 1w(%) |
Yield | Risk Level |
|---|---|---|---|---|
| Cogent Cmmns Grp 7% Jun 2027 | USD | -5,66% | 26,22% | |
| FMC 4.5% Oct 2049 | USD | -3,35% | 7,88% | |
| Flowers Foods 6.2% Mar 2055 | USD | -3,33% | 8,44% | |
| Republic of France 2% May 2048 | EUR | -3,15% | 4,99% | |
| Goodyear 5.25% Apr 2031 | USD | -3,13% | 8,86% | |
| Republic of France 3% May 2054 | EUR | -3,06% | 5,08% | |
| FedEx 5.25% May 2050 | USD | -3,05% | 6,66% | |
| Republic of France 3.25% May 2055 | EUR | -3,00% | 5,10% | |
| Republic of France 4% Apr 2060 | EUR | -2,97% | 5,14% | |
| Republic of France 3% Jun 2049 | EUR | -2,97% | 5,00% |
Rating changes
Note: only long-term senior unsecured ratings were taken into account.
Upgrades outnumbered downgrades this week, by 24 to 17. On the positive side, Capital One, Rolls-Royce and Citizens Financial each moved up a notch, and Smithfield Foods, Reliance and Embraer were among other well-known names to improve. The downgrades were led by Flowers Foods, which lost its investment-grade rating, along with Taiwan Power, Leggett & Platt and casino operator Resorts World Las Vegas. Genting and Utz were also cut.
| Issuer | Agency | Change |
|---|---|---|
| AMC Entertainment | Fitch | B- (new) |
| Bank of India | S&P | BBB (new) |
| Bingo | Fitch | B+ → B |
| Bowlero | S&P | B → B- |
| Capital One | S&P | BBB → BBB+ |
| Citizens Financial | Fitch | BBB+ → A- |
| Community First Credit Union | S&P | BBB → BBB+ |
| Congruex | S&P | CCC → CCC- |
| Davr Bank | S&P | B → B+ |
| Deep Blue Operating | S&P | BB- → BB |
| Derby Buyer | S&P | B → B+ |
| Embraer | Fitch | BBB- → BBB |
| Flowers Foods | S&P | BBB- → BB+ |
| Genting | Fitch | BBB → BBB- |
| GMR Hyderabad International Airport | Fitch | BB+ → BBB- |
| HX Holdco | Fitch | RD → CCC- |
| Integer | S&P | BB- → B |
| Intergas Central Asia | S&P | BB+ → BBB- |
| Kapitalbank | Fitch | B → B+ |
| Kite Realty | Fitch | BBB → BBB+ |
| LD Celulose | Fitch | BB- → BB |
| Leggett & Platt | S&P | BBB- → BB+ |
| Limak Yenilenebilir Enerji | Fitch | BB- → B+ |
| Lucky Strike Entertainment | S&P | B → B- |
| Michael Baker International | S&P | B → B- |
| Novae | S&P | B → CCC+ |
| Office Properties Income Trust | S&P | D → B- |
| Peach Property | Fitch | B → B+ |
| Peru LNG | Fitch | B → B+ |
| QazaqGaz | S&P | BB+ → BBB- |
| Queensland Treasury | S&P | AA+ → AA |
| Reliance | S&P | BBB- → BBB |
| Resorts World Las Vegas | Fitch | BBB- → BB+ |
| Rolls-Royce | S&P | BBB+ → A- |
| Shea Homes | S&P | BB- → B+ |
| Smithfield Foods | S&P | BBB- → BBB |
| Taiwan Power | Fitch | AA → A+ |
| Townsquare Media | S&P | B+ → B |
| UM-U Intermediate | S&P | B- (new) |
| Utz | S&P | B → B- |
| WH Group | S&P | BBB → BBB+ |
New issues
It was a busy week for new bond sales as issuers rushed to raise money after the summer break. Banks, agencies and companies all came to market across dollars, euros and sterling, from large names like KfW, ING, UBS and Orange to sovereigns including Spain and the UK. American companies again borrowed heavily in euros, drawn by comparatively cheaper funding. Investor demand held up well despite the sharp move in yields, a sign that appetite for new bonds remains strong.
| Issuer | Size | Term | Yield | Risk Level |
|---|---|---|---|---|
| Agence Francaise de Developpement | EUR 1,5bn | 8Y | 4,3% | |
| ISIN (CUSIP)FR001401AXV5 | ||||
| Alcoa Nederland Holding | USD 1,1bn | 10Y | 6,9% | |
| ISIN (CUSIP)USN02175AG70 | ||||
| Ally Financial | USD 0,75bn | 4Y | 5,5% | |
| ISIN (CUSIP)02005NCC2 | ||||
| Alumina Finance | USD 1,5bn | 8Y | 6,6% | |
| ISIN (CUSIP)USQ0270AAC64 | ||||
| Amazon | GBP 3,2bn | 3–12Y | 5,2–6,3% | |
| ISIN (CUSIP)XS3504677348…XS3504677777 | ||||
| Ameren | USD 0,90bn | 31Y | 6,5% | |
| ISIN (CUSIP)US023608AT96 | ||||
| American Tower | USD 1,6bn | 5–10Y | 5,4–5,8% | |
| ISIN (CUSIP)US03027XCT54…US03027XCV01 | ||||
| Ares Capital | USD 0,75bn | 7Y | 6,5% | |
| ISIN (CUSIP)04010LBP7 | ||||
| Arxo Finance | USD 0,30bn | 5Y | 11,0% | |
| ISIN (CUSIP)NO0013769844 | ||||
| Asian Development Bank | EUR 1,2bn | 7Y | 3,5% | |
| ISIN (CUSIP)XS3504828735 | ||||
| Autodesk | USD 1,0bn | 3–7Y | 5,1–5,7% | |
| ISIN (CUSIP)US052769AK24…US052769AL07 | ||||
| Banco BPM | EUR 0,75bn | 6Y | 4,1% | |
| ISIN (CUSIP)IT0005730749 | ||||
| Bank of Montreal | GBP 0,40bn | 7Y | 5,7% | |
| ISIN (CUSIP)XS3496798177 | ||||
| Bank of Montreal | USD 1,0bn | 60Y | 7,4% | |
| ISIN (CUSIP)US06368L8W98 | ||||
| Bank of Nova Scotia | GBP 2,0bn | 4–6Y | 5,1%; FLOAT, +49bp | |
| ISIN (CUSIP)XS3506172645 | ||||
| Bayerische Landesbodenkreditanstalt | EUR 0,50bn | 10Y | 3,6% | |
| ISIN (CUSIP)DE000A161R93 | ||||
| Blue Owl Credit Income | USD 1,0bn | 3–5Y | 6,4–6,9% | |
| ISIN (CUSIP)USU0942DAK55…USU0942DAH27 | ||||
| BNP Paribas | EUR 1,5bn | 6Y | 4,2% | |
| ISIN (CUSIP)FR001401AXT9 | ||||
| Bpifrance | EUR 1,2bn | 5Y | 3,6% | |
| ISIN (CUSIP)FR001401AQN6 | ||||
| Brenntag Finance | EUR 0,50bn | 7Y | 4,3% | |
| ISIN (CUSIP)XS3502111522 | ||||
| Capital One Financial | EUR 1,5bn | 6–11Y | 4,3–4,8% | |
| ISIN (CUSIP)XS3486716775…XS3486716858 | ||||
| Capital Southwest | USD 0,35bn | 5Y | 7,0% | |
| ISIN (CUSIP)140501AG2 | ||||
| Clariane | EUR 0,50bn | 5Y | 6,9% | |
| ISIN (CUSIP)XS3491326727 | ||||
| Commonwealth Bank of Australia | USD 3,0bn | 3–11Y | 4,8–6,1%; FLOAT | |
| ISIN (CUSIP)US20271RAY63…USQ2704MAQ17 | ||||
| Corebridge Global Funding | USD 0,75bn | 5Y | 5,6% | |
| ISIN (CUSIP)00138EBQ6 | ||||
| Corporacion Andina de Fomento | USD 2,0bn | 5Y | 4,8% | |
| ISIN (CUSIP)US219868CS37 | ||||
| Cox Asset Mexico | USD 0,80bn | PERP | 8,8% | |
| ISIN (CUSIP)USP3172AAC01 | ||||
| Credit Agricole | USD 1,8bn | 4Y | 5,3%; FLOAT, +100bp | |
| ISIN (CUSIP)US22536PAW14 | ||||
| Dekabank Deutsche Girozentrale | EUR 0,50bn | 3Y | 3,7% | |
| ISIN (CUSIP)XS3499990649 | ||||
| Dell International | USD 4,0bn | 3–7Y | 5,1–5,7% | |
| ISIN (CUSIP)24703DBY6…24703DCA7 | ||||
| Derichebourg | EUR 0,47bn | 5Y | 5,4% | |
| ISIN (CUSIP)XS3450028124 | ||||
| DP World | EUR 0,75bn | 6Y | 4,9% | |
| ISIN (CUSIP)XS3504857676 | ||||
| DP World | USD 0,75bn | 10Y | 6,3% | |
| ISIN (CUSIP)XS3504857593 | ||||
| Duke Energy Progress | USD 1,0bn | 10–30Y | 5,6–6,2% | |
| ISIN (CUSIP)US26442UAW45…US26442UAX28 | ||||
| Electricite de France | EUR 1,0bn | PERP | 5,4% | |
| ISIN (CUSIP)FR001401ARD5 | ||||
| Engie | EUR 0,75bn | PERP | 5,0% | |
| ISIN (CUSIP)FR001401AVW7 | ||||
| Erste Bank Hungary | EUR 0,50bn | 6Y | 4,4% | |
| ISIN (CUSIP)AT0000A3X206 | ||||
| Euroclear Holding | EUR 0,60bn | 10Y | 4,2% | |
| ISIN (CUSIP)BE6377188204 | ||||
| FedEx | EUR 2,0bn | 4–8Y | 4,1–4,7% | |
| ISIN (CUSIP)XS3494005021…XS3494029393 | ||||
| FedEx | USD 1,1bn | 10Y | 5,8% | |
| ISIN (CUSIP)US31428XED49 | ||||
| First Abu Dhabi Bank | USD 0,50bn | 5Y | 5,5% | |
| ISIN (CUSIP)XS3506218737 | ||||
| First Citizens BancShares | USD 0,30bn | PERP | 7,5% | |
| ISIN (CUSIP)US31959XAK90 | ||||
| Fortis | USD 1,0bn | 30Y | 6,6–6,9% | |
| ISIN (CUSIP)US349553AV96…US349553AW79 | ||||
| GlaxoSmithKline | USD 3,8bn | 3–30Y | 5,1–6,1%; FLOAT, +56bp | |
| ISIN (CUSIP)US377372AT41…US377372AW79 | ||||
| Group 1 Automotive | USD 0,62bn | 5Y | 6,2% | |
| ISIN (CUSIP)USU03903AH14 | ||||
| Hamburg Free and Hanseatic, City of | EUR 1,0bn | 6Y | 3,5% | |
| ISIN (CUSIP)DE000A3MQTU1 | ||||
| ING Bank | EUR 1,8bn | 8–12Y | 3,6–3,8% | |
| ISIN (CUSIP)XS3503934476…XS3503934559 | ||||
| IQVIA | USD 2,0bn | 8Y | 6,4% | |
| ISIN (CUSIP)USU46093AM99 | ||||
| Jackson National Life Global Funding | USD 0,70bn | 3Y | 5,4% | |
| ISIN (CUSIP)US46849MCV90 | ||||
| Jamaica | USD 1,0bn | 11Y | 6,2% | |
| ISIN (CUSIP)US470160CG50 | ||||
| Japan Post Insurance | USD 1,0bn | 30Y | 6,5% | |
| ISIN (CUSIP)USJ2800EAE70 | ||||
| John Deere Capital | USD 1,8bn | 2–5Y | 4,7–5,1%; FLOAT | |
| ISIN (CUSIP)US24422EYR43…US24422EYU71 | ||||
| Kasikornbank | USD 0,80bn | 10Y | 6,3% | |
| ISIN (CUSIP)XS3503275177 | ||||
| KfW | USD 3,0bn | 5Y | 4,6% | |
| ISIN (CUSIP)US500769KT05 | ||||
| Kommunalbanken | USD 1,0bn | 3Y | 4,7% | |
| ISIN (CUSIP)XS3507773698 | ||||
| Kommuninvest i Sverige | USD 1,0bn | 3Y | 4,6% | |
| ISIN (CUSIP)XS3504711030 | ||||
| Korea Securities Finance | USD 0,30bn | 3Y | 5,0% | |
| ISIN (CUSIP)XS3504731228 | ||||
| Korea Southern Power | USD 0,30bn | 3Y | 5,0% | |
| ISIN (CUSIP)XS3493264934 | ||||
| Kutxabank | EUR 0,75bn | 7Y | 3,7% | |
| ISIN (CUSIP)ES0443307089 | ||||
| Lagardere | EUR 0,50bn | 6Y | 5,4% | |
| ISIN (CUSIP)FR001401AUH0 | ||||
| LBBW | EUR 1,0bn | 4Y | 3,4% | |
| ISIN (CUSIP)DE000LB4XHY2 | ||||
| Helaba | EUR 0,75bn | 5Y | 3,5% | |
| ISIN (CUSIP)XS3503935283 | ||||
| Loomis | EUR 0,30bn | 5Y | 4,2% | |
| ISIN (CUSIP)XS3504841910 | ||||
| Malayan Banking | USD 0,30bn | 3–5Y | 5,1%; FLOAT, +60bp | |
| ISIN (CUSIP)XS3504963789 | ||||
| Mashreqbank | USD 0,50bn | 5Y | 5,7% | |
| ISIN (CUSIP)XS3506239907 | ||||
| Mercadolibre | USD 1,0bn | 10Y | 6,1% | |
| ISIN (CUSIP)US58733RAJ14 | ||||
| Mitsubishi UFJ Financial Group | USD 2,8bn | 6–21Y | 5,4–6,2%; FLOAT, +110bp | |
| ISIN (CUSIP)US606822EF74…US606822EH31 | ||||
| National Bank of Canada | USD 1,2bn | 3Y | 4,7% | |
| ISIN (CUSIP)USC60191BH20 | ||||
| NWB Bank | EUR 1,2bn | 5Y | 3,4% | |
| ISIN (CUSIP)XS3504737001 | ||||
| NORD/LB | EUR 0,50bn | 3Y | 3,6% | |
| ISIN (CUSIP)DE000NLB57Z0 | ||||
| Nordea Kiinnitysluottopankki | EUR 1,2bn | 3–7Y | 3,5%; FLOAT, +16bp | |
| ISIN (CUSIP)XS3503302831 | ||||
| Oaktree Specialty Lending | USD 0,30bn | 5Y | 7,0% | |
| ISIN (CUSIP)US67401PAF53 | ||||
| Office Properties Income | USD 0,42bn | 5Y | 9,1% | |
| ISIN (CUSIP)USU6768CAH26 | ||||
| Oncor Electric Delivery Company | USD 1,8bn | 10–40Y | 5,7–6,4% | |
| ISIN (CUSIP)USU68279AV72…USU68279AW55 | ||||
| OP Corporate Bank | EUR 0,50bn | 7Y | 3,9% | |
| ISIN (CUSIP)XS3504771364 | ||||
| Orange | EUR 1,9bn | 9–12Y | 4,3–4,6% | |
| ISIN (CUSIP)FR001401AWB9…FR001401AWC7 | ||||
| OTP Bank | EUR 0,75bn | 5Y | 3,7% | |
| ISIN (CUSIP)XS3503291026 | ||||
| Parker-Hannifin | EUR 2,0bn | 4–10Y | 3,8–4,4% | |
| ISIN (CUSIP)XS3498804585…XS3498804825 | ||||
| Parker-Hannifin | USD 2,4bn | 2–7Y | 4,8–5,3% | |
| ISIN (CUSIP)US701094AT15…US701094AV60 | ||||
| Pattern Energy Group | USD 0,95bn | 5Y | 7,0% | |
| ISIN (CUSIP)USU70445AC21 | ||||
| Pilgrims Pride | EUR 0,50bn | 7Y | 4,8% | |
| ISIN (CUSIP)XS3507736224 | ||||
| Plains All American Pipeline | USD 1,5bn | 30Y | 6,8–7,0% | |
| ISIN (CUSIP)US726503AF21…US726503AG04 | ||||
| RBL Bank | USD 0,35bn | 5Y | 5,8% | |
| ISIN (CUSIP)XS3506162687 | ||||
| Royal Bank of Canada | EUR 3,0bn | 5–10Y | 3,5–3,8% | |
| ISIN (CUSIP)XS3506171837 | ||||
| Shea Homes Funding | USD 0,75bn | 6–8Y | 6,6–7,0% | |
| ISIN (CUSIP)USU82091AG11…USU82091AF38 | ||||
| Shinhan Bank | EUR 0,60bn | 4Y | 3,4% | |
| ISIN (CUSIP)XS3478212924 | ||||
| Societe Nationale SNCF | GBP 0,25bn | 15Y | 6,2% | |
| ISIN (CUSIP)FR001401ARM6 | ||||
| Spain, Kingdom of | EUR 4,0bn | 21Y | 4,3% | |
| ISIN (CUSIP)ES0000012S30 | ||||
| Sr-Boligkreditt | EUR 0,75bn | 5Y | 3,4% | |
| ISIN (CUSIP)XS3504723985 | ||||
| Stellantis Finance Us | USD 2,5bn | 5–10Y | 6,8–7,4% | |
| ISIN (CUSIP)US85855CAR16…US85855CAS98 | ||||
| Tecpetrol | USD 0,45bn | PERP | 7,2% | |
| ISIN (CUSIP)USP90187AR99 | ||||
| Tenet Healthcare | USD 2,0bn | 8Y | 6,2% | |
| ISIN (CUSIP)USU88030BR83 | ||||
| Teva Pharmaceutical | EUR 1,5bn | 6–10Y | 4,5–4,8% | |
| ISIN (CUSIP)XS3498885725…XS3498887341 | ||||
| Teva Pharmaceutical | USD 3,2bn | 5–10Y | 5,5–5,9% | |
| ISIN (CUSIP)US881937AB24…US88167AAV35 | ||||
| Toyota Tsusho America | USD 0,50bn | 5Y | 5,2% | |
| ISIN (CUSIP)XS3481514522 | ||||
| Tr Finance | USD 1,3bn | 2–7Y | 5,1–5,8% | |
| ISIN (CUSIP)US87268LAF40…US87268LAG23 | ||||
| TTM Technologies | USD 0,50bn | 8Y | 6,8% | |
| ISIN (CUSIP)USU8729LAD56 | ||||
| Turkiye Ihracat Kredi Bankasi | USD 0,50bn | 4Y | 7,0% | |
| ISIN (CUSIP)XS3501986874 | ||||
| Uber Technologies | EUR 4,5bn | 3–20Y | 3,8–5,3% | |
| ISIN (CUSIP)XS3498991671…XS3498992216 | ||||
| UBS Group | USD 6,0bn | 5–21Y | 5,4–6,3% | |
| ISIN (CUSIP)USH42097FW29…USH42097FY84 | ||||
| United Kingdom of Great Britain and Northern Ireland | GBP 4,2bn | PERP | 5,8% | |
| ISIN (CUSIP)GB00BT7J0241 | ||||
| USA Compression Partners | USD 0,60bn | 8Y | 6,8% | |
| ISIN (CUSIP)USU9033CAE22 | ||||
| Vedanta Resources Finance Ii | USD 0,40bn | 6–11Y | 7,0–7,7% | |
| ISIN (CUSIP)XS3427418432…XS3427418788 | ||||
| Vistra Operations Company | USD 1,5bn | 30Y | 7,0–7,2% | |
| ISIN (CUSIP)US92840VBE11…US92840VBF85 | ||||
| Volkswagen Group of America Finance | USD 3,0bn | 2–7Y | 5,1–6,0%; FLOAT, +101bp | |
| ISIN (CUSIP)USU9273AFD29…USU9273AFG59 | ||||
| Williams Cos | USD 2,8bn | 3–30Y | 5,0–6,4% | |
| ISIN (CUSIP)US969457DA58…969457CZ1 | ||||
| Wynn Resorts Finance | USD 0,90bn | 8Y | 7,0% | |
| ISIN (CUSIP)USU98354AF77 | ||||
| YPF | USD 1,2bn | 9Y | 7,8% | |
| ISIN (CUSIP)USP989MJCB55 | ||||
This article does not constitute investment advice or personal recommendation. Investments in securities and other financial instruments always involve the risk of loss of your capital. Past performance is not a reliable indicator of future results. Bondfish does not recommend using the data and information provided as the only basis for making any investment decision. You should not make any investment decisions without first conducting your own research and considering your own financial situation.