Weekly bond digest: July 13 – July 19, 2026
Yield Curves
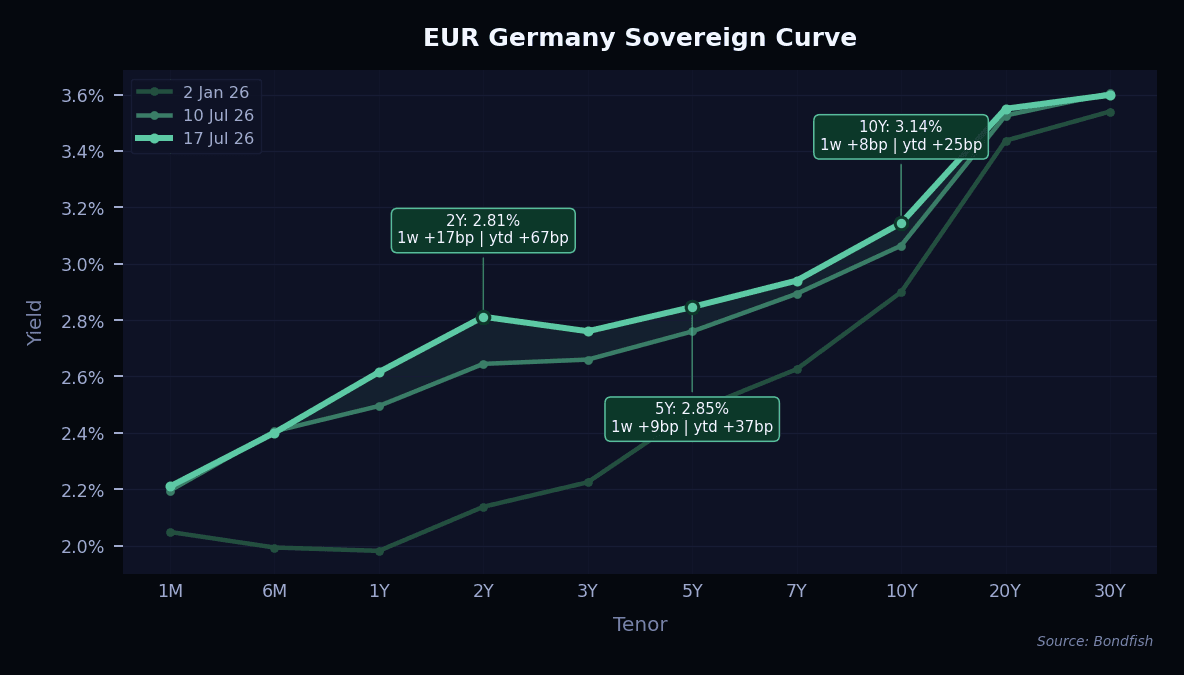
German yields rose across the curve, and the biggest move was at the short end — the 2-year climbed 17 basis points to 2.81%. The jump in oil and gas prices revived inflation worries, and heavy government bond supply added to the pressure. The 10-year finished at 3.14%, up 8 basis points on the week.
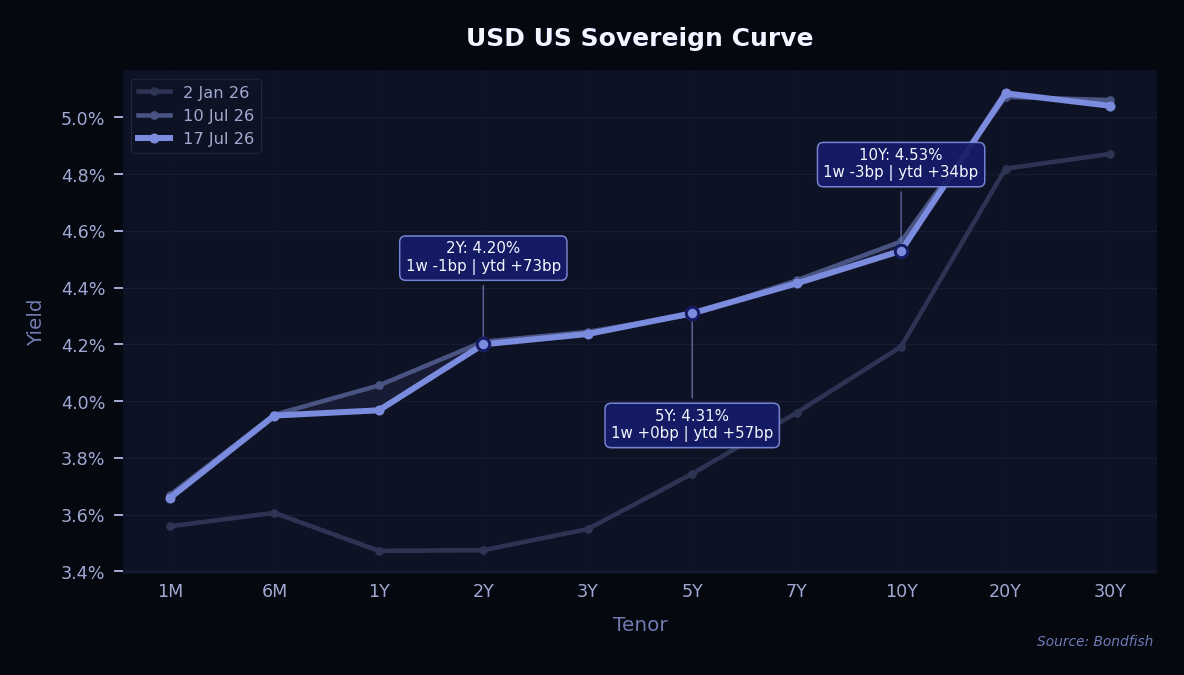
US yields barely moved, and the long end slipped a little. The 10-year eased 3 basis points to 4.53% and the 2-year was down 1 basis point at 4.20%. A sharp drop in semiconductor shares pulled some money into Treasuries as a safe haven, which offset the inflation signal from higher oil and left the curve broadly steady.
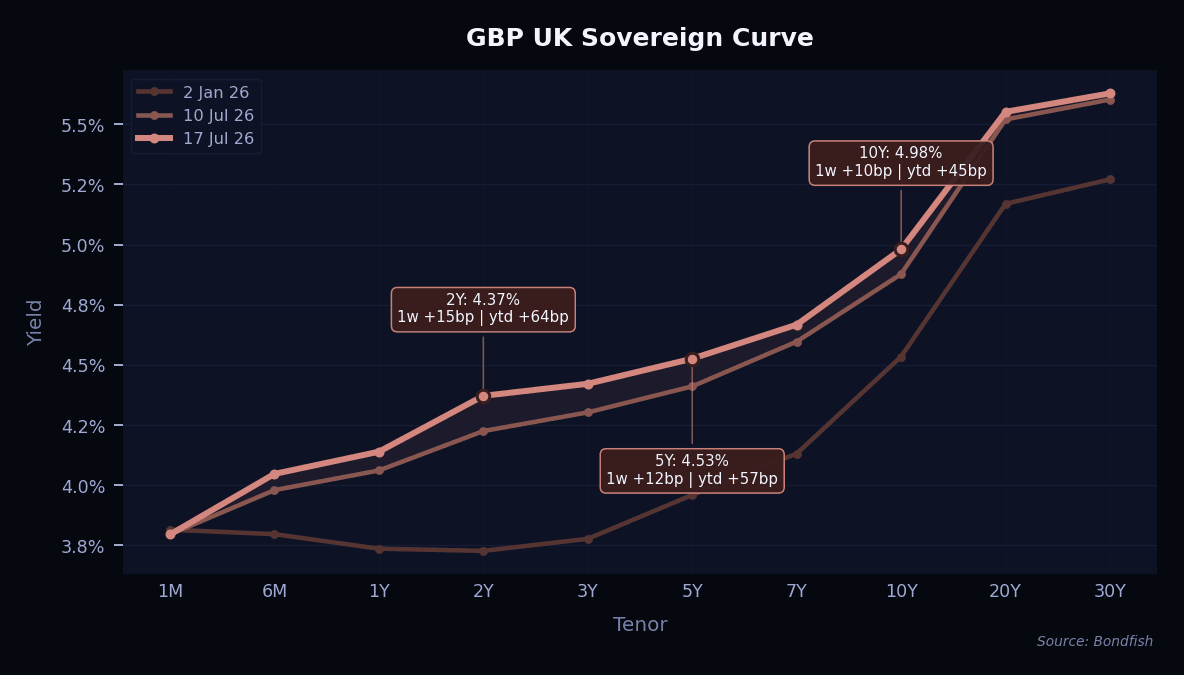
UK yields rose all along the curve. The 2-year gained 15 basis points to 4.37% and the 10-year added 10 basis points to 4.98%. Higher energy prices and still-sticky inflation kept the pressure on gilts, and investors trimmed their bets on near-term rate cuts.
With supply heavy and inflation still sticky, the favoured stance stays defensive — keeping duration on the shorter side and earning income from high-quality bonds rather than reaching for the longest maturities.
Top gainers
The week's standout was PayPal's 3.25% 2050 bond, a long-dated high-grade name that jumped 12.1%. High-yield industrials rebounded broadly: both Ineos Quattro Fin 2 bonds rose (up 4.3% and 3.3%), joined by Ineos Finance (+1.7%), Kohl's (+2.4%), Domtar (+2.4%) and Kronos International (+1.7%). Howard University's 2051 bond gained 4.5%, and higher-rated names Athene Global (+1.8%) and Stora Enso (+1.7%) rounded out the list.
| Name | Cur | Price change 1w(%) | Yield | Risk Level |
| PayPal Hldg 3.25% Jun 2050 | USD | 12,14% | 5,39% | Low |
| Howard Uni 4.756% Oct 2051 | USD | 4,53% | 6,49% | Medium |
| Ineos Quattro Fin 2 6.75% Apr 2030 | EUR | 4,29% | 11,44% | Very High |
| Ineos Quattro Fin 2 8.5% Mar 2029 | EUR | 3,33% | 11,18% | Very High |
| Kohls 6.875% Dec 2037 | USD | 2,41% | 9,25% | Very High |
| Domtar 6.75% Oct 2028 | USD | 2,39% | 23,48% | Very High |
| Athene Global 5.543% Aug 2035 | USD | 1,79% | 5,50% | Low |
| Stora Enso 7.25% Apr 2036 | USD | 1,73% | 5,72% | Medium |
| Kronos Intnl 9.5% Mar 2029 | EUR | 1,70% | 10,21% | Very High |
| Ineos Finance 5.625% Aug 2030 | EUR | 1,67% | 6,96% | High |
Top losers
The falls were concentrated in high-yield telecom, where all three Virgin Media bonds dropped — Virgin Media Fin (-4.7%), Virgin Media O2 (-3.3%) and Vmed UK (-2.9%). Community Health Systems (-3.1%) and Flagstar Bank (-2.9%) also declined. Longer-dated bonds felt the rise in yields most: Northumbrian Water (-2.7%), Paramount Global (-2.5%) and Harley-Davidson (-2.4%) all slid, along with Places for People and even the very-low-risk European Financial Stability Facility bond (-2.4%).
| Name | Cur | Price change 1w(%) | Yield | Risk Level |
| Virgin Media Fin 3.75% Jul 2030 | EUR | -4,74% | 11,18% | Very High |
| Virgin Media O2 7.875% Mar 2032 | GBP | -3,32% | 13,21% | Very High |
| Community Health Systems 6.125% Apr 2030 | USD | -3,09% | 9,90% | Very High |
| Places Peopl 3.901% Dec 2034 | EUR | -3,00% | 4,47% | Low |
| Flagstar Bnk 7.574% Nov 2030 | USD | -2,93% | 19,31% | High |
| Vmed UK 3.25% Jan 2031 | EUR | -2,93% | 6,83% | High |
| Northumbrian Wtr 6.875% Apr 2045 | GBP | -2,65% | 7,00% | Medium |
| Paramount Global 5.9% Oct 2040 | USD | -2,46% | 9,06% | High |
| Harley Davidson 4.625% Jul 2045 | USD | -2,42% | 6,76% | Medium |
| European Fin Stability 2.75% Dec 2029 | EUR | -2,39% | 2,97% | Very Low |
Rating changes
Note: only long-term senior unsecured ratings were taken into account.
Upgrades edged out downgrades, 16 to 14. The biggest jump came from Chart Industries, lifted several notches by S&P to A-, while Ford Bank, KeyCorp and KeyBank all won higher marks from Moody's and Banco BPI moved up to A+. On the downside, HSBC Bank Uruguay was cut three notches to BB+, Baker Hughes slipped to A-, and KB Home, Cornerstone OnDemand and PECO Energy were all lowered. Sirona fell to selective default.
| Issuer | Agency | Change |
| Ammega | Fitch | B- → CCC+ |
| Baker Hughes | S&P | A → A- |
| Banco BPI | Fitch | A → A+ |
| Banistmo | S&P | BB- → BB |
| Bright Food International | S&P | BBB- → BBB |
| Chart Industries | S&P | BB- → A- |
| Co-Operative Bank | Fitch | A+ (new) |
| Cornerstone OnDemand | S&P | B- → CCC+ |
| Eagle Broadband Investments | S&P | B+ → B |
| Eurotelesites | Fitch | BBB- → BBB |
| Ford Bank | Moody's | Baa1 → A3 |
| Forgent Power | S&P | B → B+ |
| HSBC Bank Uruguay | Fitch | BBB+ → BB+ |
| Janus Henderson US | Fitch | BB+ (new) |
| KB Home | S&P | BB+ → BB |
| Keybank National Association | Moody's | Baa1 → A3 |
| KeyCorp | Moody's | Baa2 → Baa1 |
| M/I Homes | S&P | BB → BB+ |
| Medical Solutions Parent | S&P | D → CCC+ |
| Mega Broadband Investments Intermediate I | S&P | B+ → B |
| Neuraxpharm | S&P | B → B- |
| PECO Energy | Moody's | A2 → A3 |
| Petroquimica Comodoro Rivadavia | S&P | B (new) |
| Project Boost Purchaser | S&P | B- → B |
| Project Leopard | Fitch | B- → CCC |
| Sirona | S&P | CCC → SD |
| Tungsten Cayco | Fitch | B- → CCC |
| Urumqi Gaoxin Investment and Development | Fitch | BB+ → BBB- |
| Uzmetkombinat OAO | Fitch | B+ → B |
| Victoria | S&P | CCC+ → CCC- |
New issues
It was a heavy week for high-grade supply, led by financials. JPMorgan Chase, Morgan Stanley, Goldman Sachs, Mitsubishi UFJ and PNC all printed multi-tranche dollar deals. Supranationals and agencies were busy too — the International Bank for Reconstruction and Development, Export Development Canada, New Development Bank and African Export-Import Bank all came to market — alongside sovereigns including the United Kingdom and Serbia. Demand stayed firm even with oil prices spiking and volatility rising elsewhere, with investors leaning toward high-quality, longer-dated bonds.
| Issuer | Size | Term | Yield | Risk Level |
| African Export Import Bank | USD 1,5bn | 6–10Y | 6,2–7,1% | Medium |
ISIN (CUSIP) XS3437376703…XS3437376612 | ||||
| Anhui Transportation Holding Group HK | USD 0,40bn | 3Y | 4,3% | Low |
ISIN (CUSIP) XS3435193381 | ||||
| Australia and New Zealand Banking Group | GBP 1,2bn | 4Y | FLOAT, +50bp | Very Low |
ISIN (CUSIP) XS3449093007 | ||||
| Bank of New York Mellon | USD 0,50bn | PERP | 6,2% | Medium |
ISIN (CUSIP) US064058AW09 | ||||
| Bayer US Finance | USD 5,0bn | 5–30Y | 5,1–6,4% | Medium |
ISIN (CUSIP) USU07264AN10…USU07264AQ41 | ||||
| Beusa Investments | USD 0,80bn | 5Y | 7,0% | Very High |
ISIN (CUSIP) USU0877JAA35 | ||||
| Carrix | USD 2,5bn | 7Y | 6,1% | Medium |
ISIN (CUSIP) USU1453NAA47 | ||||
| China CITIC Bank International | USD 0,40bn | PERP | 5,0% | High |
ISIN (CUSIP) XS3371242911 | ||||
| Conceria Pasubio SpA | EUR 0,40bn | 6Y | 9,5% | Very High |
ISIN (CUSIP) XS3445916524 | ||||
| Corelogic | USD 2,5bn | 5–6Y | 9,0–13,3% | Very High |
ISIN (CUSIP) USU20621AC97…USU20621AD70 | ||||
| Distrito Especial Industrial y Portuario de Barranquilla | USD 0,35bn | 5Y | 7,3% | High |
ISIN (CUSIP) USP3600PAD70 | ||||
| Export Development Canada | USD 2,0bn | 5Y | 4,3% | Very Low |
ISIN (CUSIP) US30216BKT88 | ||||
| Export-Import Bank of Korea | USD 2,0bn | 3–5Y | 4,5–4,6% | Very Low |
ISIN (CUSIP) US302154EV78…US302154EW51 | ||||
| GA Global Funding | USD 0,40bn | 5Y | 5,5% | Low |
ISIN (CUSIP) US36143M2X01 | ||||
| Goldman Sachs Group | EUR 5,0bn | 4–8Y | 3,6–4,1%; FLOAT | Low |
ISIN (CUSIP) XS3447651202…XS3447651111 | ||||
| Goldman Sachs Group | USD 10,0bn | 6–31Y | 5,2–6,2% | Low |
ISIN (CUSIP) US38145GAV23…US38145GAX88 | ||||
| Heico | USD 1,2bn | 10Y, PERP | 5,0–5,4% | Medium |
ISIN (CUSIP) 422806AC3…422806AD1 | ||||
| Iliad | EUR 0,65bn | 5Y | 4,1% | High |
ISIN (CUSIP) FR0014019WY8 | ||||
| International Bank for Reconstruction and Development | USD 1,5bn | 7Y | FLOAT, +38bp | Very Low |
ISIN (CUSIP) US459058MB69 | ||||
| Intrum Investments and Financing AB | EUR 0,53bn | 5Y | 7,0% | Very High |
ISIN (CUSIP) XS3438544630 | ||||
| Jinko Power (HK) | USD 0,10bn | 3Y | 4,4% | Very High |
ISIN (CUSIP) XS3408475476 | ||||
| John Deere Bank | EUR 0,60bn | 4Y | 3,4% | Low |
ISIN (CUSIP) XS3438591128 | ||||
| JPMorgan Chase | USD 9,0bn | 4–15Y | 4,9–5,8%; FLOAT | Very Low |
ISIN (CUSIP) US48128BAV36…US48128BAT89 | ||||
| Kennedy Wilson | USD 0,30bn | 7Y | 7,0% | Very High |
ISIN (CUSIP) USU49454AG37 | ||||
| Korea Electric Power | USD 0,70bn | 3–5Y | 4,9%; FLOAT, +62bp | Very Low |
ISIN (CUSIP) USY4907LAU62 | ||||
| KT&G | USD 0,30bn | 4Y | 4,9% | Low |
ISIN (CUSIP) XS3428230844 | ||||
| Massachusetts Electric | USD 0,60bn | 30Y | 6,2% | Medium |
ISIN (CUSIP) USU57467AE94 | ||||
| Mitsubishi HC Finance America | USD 0,50bn | 5Y | 5,2% | Low |
ISIN (CUSIP) USU6S68YAK42 | ||||
| Mitsubishi UFJ Financial Group | USD 3,0bn | 4–21Y | 5,0–6,0%; FLOAT | Low |
ISIN (CUSIP) US606822DZ48…US606822ED27 | ||||
| Morgan Stanley | USD 6,5bn | 3–11Y | 5,2–5,6%; FLOAT | Low |
ISIN (CUSIP) US61748UBA97…US61748UBB70 | ||||
| New Development Bank | USD 1,8bn | 3Y | 4,4% | Very Low |
ISIN (CUSIP) XS3425662601 | ||||
| Nonghyup Bank | USD 0,60bn | 4–5Y | 4,7%; FLOAT, +60bp | Very Low |
ISIN (CUSIP) USY6396XAM12 | ||||
| Paragon Banking Group | GBP 0,20bn | 10Y | 6,5% | Medium |
ISIN (CUSIP) XS3392880038 | ||||
| PNC Financial Services Group | USD 2,0bn | 4–11Y | 4,8–5,5% | Low |
ISIN (CUSIP) US693475CL76 | ||||
| Sba Communications | USD 3,5bn | 3–7Y | 5,1–5,6% | Medium |
ISIN (CUSIP) US78410GAH74…US78410GAK04 | ||||
| Republic of Serbia | EUR 0,50bn | 6Y | 4,8% | Very High |
ISIN (CUSIP) XS3436151750 | ||||
| SMBC Aviation Capital Finance | USD 2,0bn | 3–10Y | 5,0–5,7% | Medium |
ISIN (CUSIP) USG82296AR85…USG82296AQ03 | ||||
| Standard Life | GBP 0,35bn | PERP | 7,4% | Medium |
ISIN (CUSIP) XS3435285070 | ||||
| Tata Capital | USD 0,40bn | 4Y | 5,3% | Very High |
ISIN (CUSIP) XS3436154341 | ||||
| Turkiye Is Bankasi | USD 0,50bn | 12Y | 8,4% | Very High |
ISIN (CUSIP) XS3431962532 | ||||
| United Kingdom of Great Britain and Northern Ireland | GBP 4,8bn | 12Y | 2,1% | Very Low |
ISIN (CUSIP) GB00BMY62Z61 | ||||
| Validus Energy II Midcon | USD 0,50bn | 5Y | 8,0% | Very High |
ISIN (CUSIP) USU9100XAA29 | ||||
This article does not constitute investment advice or personal recommendation. Investments in securities and other financial instruments always involve the risk of loss of your capital. Past performance is not a reliable indicator of future results. Bondfish does not recommend using the data and information provided as the only basis for making any investment decision. You should not make any investment decisions without first conducting your own research and considering your own financial situation.