Weekly bond digest: March 16–22, 2026
Yield Curves
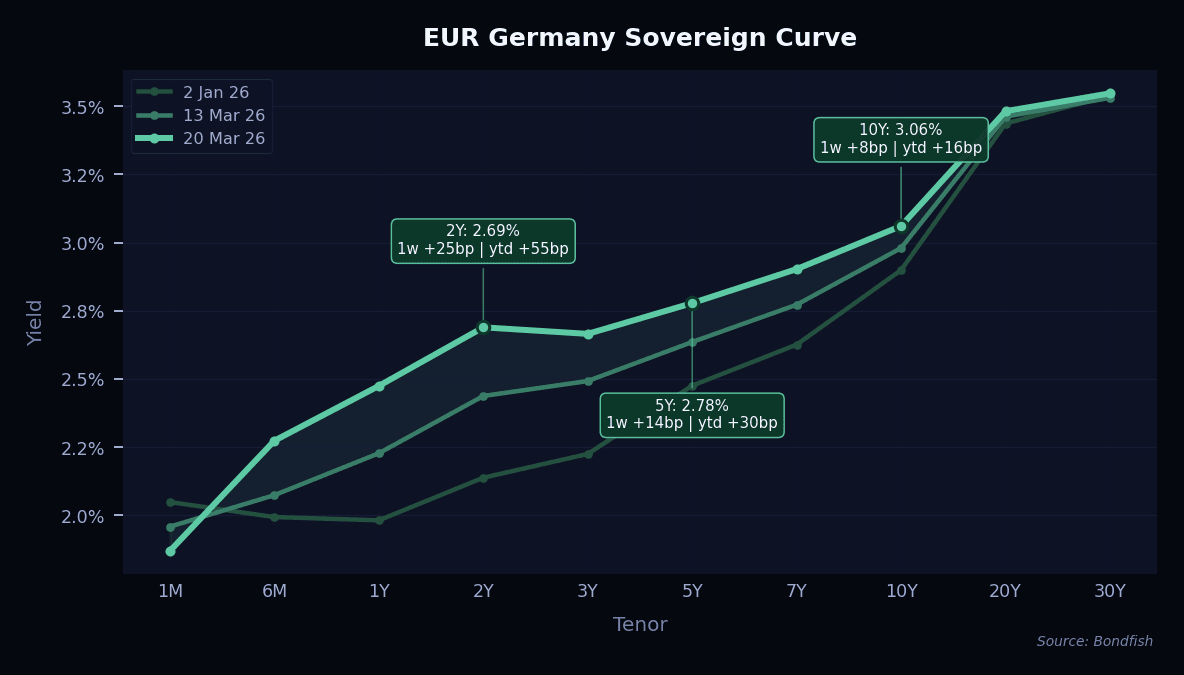
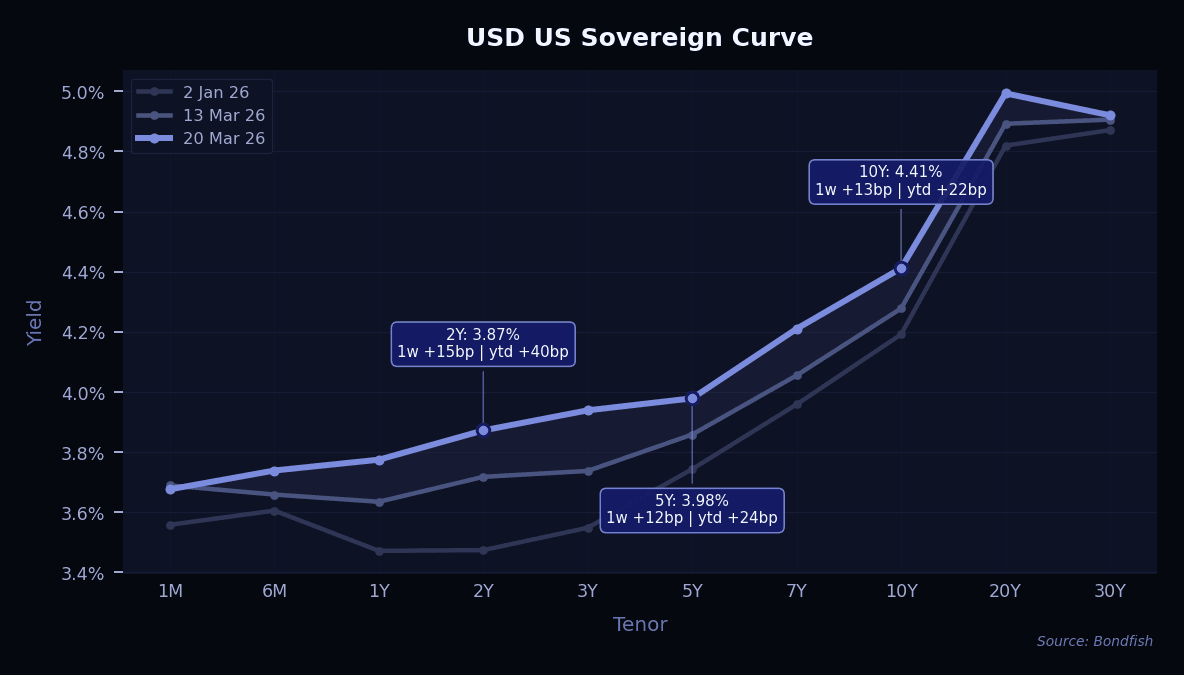
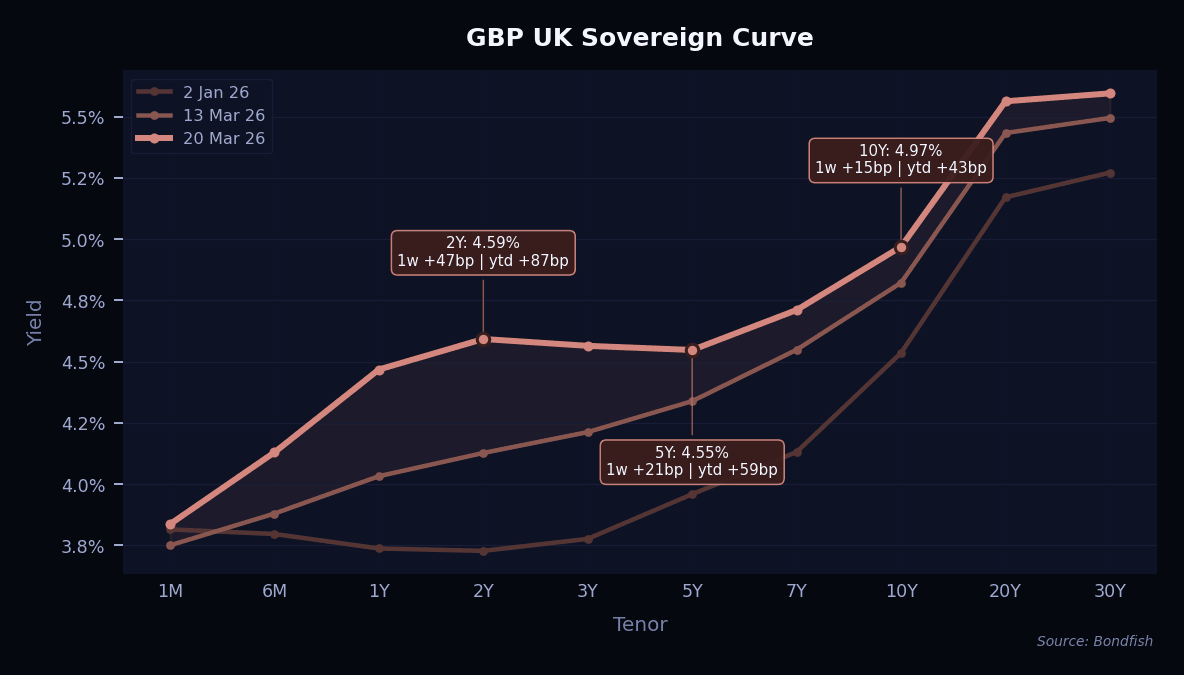
Developed market yield curves moved higher and flattened during the week, as investors priced in more persistent inflation risk from renewed energy price pressure and geopolitical uncertainty. Rising gas prices and fading expectations of a quick resolution in the Middle East conflict pushed short-dated rates up more than long-dated yields, producing a broad bear-flattening across major markets. In this environment, it makes sense to stay in shorter-duration bonds, as they are generally less exposed to further rate volatility while uncertainty remains high. If the geopolitical situation improves and the conflict moves toward resolution, longer-dated bonds could become more attractive, as elevated yields may offer a better entry point for investors looking to lock in income for longer.
Top movers
Credit markets were choppy this week as investors reacted to uncertainty around interest rates and energy prices. Fears that central banks may stay tougher for longer put pressure on bond prices, especially in longer-dated bonds, which are usually more sensitive to changes in yields. If oil prices stay high and the Fed turns more hawkish, this could create further pressure on credit markets.
At the same time, higher yields kept attracting investors into investment-grade bonds. This demand helped limit the downside, even though returns stayed weak and market swings remained high.
Top gainers
Below are the bonds with the strongest weekly price appreciation.
| Name | Cur | Price change 1w(%) | Yield | Risk Level |
| Telesat Canada 4.875% Jun 2027 | USD | 4.00% | 27.82% | VeryHigh |
Reason Narrower quarterly loss, helped by FX gains, supported bonds. | ||||
| Warnermedia Hldg 4.279% Mar 2032 | USD | 3.08% | 8.19% | High |
Reason Skydance acquisition optimism improved views on debt refinancing and balance sheet support. | ||||
| Ineos Finance 5.625% Aug 2030 | EUR | 3.05% | 8.77% | High |
Reason Iran-related petrochemical disruption boosted earnings outlook and refinancing prospects. | ||||
| Rivian Holdings 10% Jan 2031 | USD | 2.30% | 10.31% | VeryHigh |
Reason Uber robotaxi partnership boosted sentiment despite higher expected R&D spending. | ||||
| Brookfield Asst 6.077% Sep 2055 | USD | 2.01% | 6.20% | Low |
Reason OpenAI venture talks and new financing activity supported sentiment. | ||||
| Interconti Exc 5.2% Jun 2062 | USD | 1.97% | 5.96% | Low |
Reason Record revenue and cash flow, plus private credit expansion. | ||||
Top losers
The following bonds experienced the sharpest weekly declines.
| Name | Cur | Price change 1w(%) | Yield | Risk Level |
| Newell Brands 7.5% Apr 2046 | USD | -5.40% | 9.81% | VeryHigh |
Reason Weak equity performance and rising default concerns. | ||||
| Longfor Grp Hldg 3.85% Jan 2032 | USD | -5.15% | 11.07% | High |
Reason Profit warning and declining property sales. | ||||
| Bapco Energies S 6.25% Jan 2035 | USD | -4.74% | 7.08% | VeryHigh |
Reason Fitch downgraded Bapco after Bahrain’s sovereign downgrade. | ||||
| Cleveland-Cliffs 6.25% Oct 2040 | USD | -4.34% | 8.90% | VeryHigh |
Reason Analyst downgrades and fraud investigation weighed on sentiment. | ||||
| Bapco Energies S 5.25% Apr 2029 | USD | -3.96% | 7.69% | VeryHigh |
Reason Fitch downgraded Bapco after Bahrain’s sovereign downgrade. | ||||
| QP 3.3% Jul 2051 | USD | -3.65% | 5.96% | VeryLow |
Reason Iran attack damages Qatar LNG export capacity. | ||||
| QP 3.125% Jul 2041 | USD | -3.58% | 5.79% | VeryLow |
Reason Iran attack damages Qatar LNG export capacity. | ||||
| Homann Holzwerk 7.5% Jun 2032 | EUR | -3.33% | 7.05% | VeryHigh |
Reason Startup losses and weaker EBITDA margins. | ||||
| Longfor Grp Hldg 3.95% Sep 2029 | USD | -3.27% | 11.59% | High |
Reason Profit warning and declining property sales. | ||||
| Navient 11.5% Mar 2031 | USD | -3.21% | 10.52% | High |
Reason Student loan policy uncertainty pressures sector. | ||||
New issues
New bond issuance slowed sharply last week after a very heavy week before. In the US investment-grade market, supply fell to about $34bn, around 70% lower than the previous week. That lower supply helped the market absorb new deals more easily and reduced some pressure on spreads. At the same time, investors remained selective, with demand holding up better for higher-quality bonds while riskier financing faced a tougher reception.
| Issuer | Size | Term | Yield | Risk Level |
| Anglo American Capital | USD 1,3bn | 5–7Y | 4,7–5,0% | Medium |
ISIN (CUSIP) USG0446NBB94…USG0446NBC77 | ||||
| Brandenburg, State Of | EUR 0,60bn | 6Y | 2,9% | Very Low |
ISIN (CUSIP) DE000A351US7 | ||||
| Danske Bank A/S | USD 0,50bn | PERP | 6,6% | Medium |
ISIN (CUSIP) XS3317583022 | ||||
| Deutsche Boerse | EUR 0,65bn | 5Y | 3,4% | Very Low |
ISIN (CUSIP) DE000A460QR6 | ||||
| Hsbc Holdings | USD 2,5bn | PERP | 6,8–7,0% | Medium |
ISIN (CUSIP) US404280FH76…US404280FJ33 | ||||
| Infinity Natural Resources | USD 0,55bn | 5Y | 7,6% | Very High |
ISIN (CUSIP) USU45249AA49 | ||||
| Investitionsbank Berlin | EUR 1,0bn | 5Y | 2,8% | Very Low |
ISIN (CUSIP) DE000A3828Q4 | ||||
| Lower Austria, State Of | EUR 0,50bn | 12Y | 3,5% | Very Low |
ISIN (CUSIP) AT0000A3SXX0 | ||||
| Nationwide Building Society | EUR 0,75bn | 10Y | 3,3% | Very Low |
ISIN (CUSIP) XS3322497036 | ||||
| Nederlandse Financierings-Maatschappij Voor Ontwlkkelingslanden (Fmo) | USD 0,50bn | 5Y | 3,9% | Very Low |
ISIN (CUSIP) XS3325368267 | ||||
| Nederlandse Waterschapsbank | USD 1,2bn | 5Y | 3,9% | Very Low |
ISIN (CUSIP) XS3325350307 | ||||
| Nrw Bank | GBP 0,35bn | 5Y | 4,3% | Very Low |
ISIN (CUSIP) XS3325330457 | ||||
| Royal Bank Of Canada | GBP 1,0bn | 5Y | FLOAT, +58bp | Very Low |
ISIN (CUSIP) XS3323632987 | ||||
| Sydney Airport Finance Company Pty | USD 1,0bn | 10Y | 5,2% | Medium |
ISIN (CUSIP) USQ8809VAP42 | ||||
| Toronto-Dominion Bank | EUR 1,5bn | 5Y | 3,0% | Very Low |
ISIN (CUSIP) XS3324523045 | ||||
This article does not constitute investment advice or personal recommendation. Investments in securities and other financial instruments always involve the risk of loss of your capital. Past performance is not a reliable indicator of future results. Bondfish does not recommend using the data and information provided as the only basis for making any investment decision. You should not make any investment decisions without first conducting your own research and considering your own financial situation.