Weekly bond digest: August 17 – August 23, 2026
Yield Curves
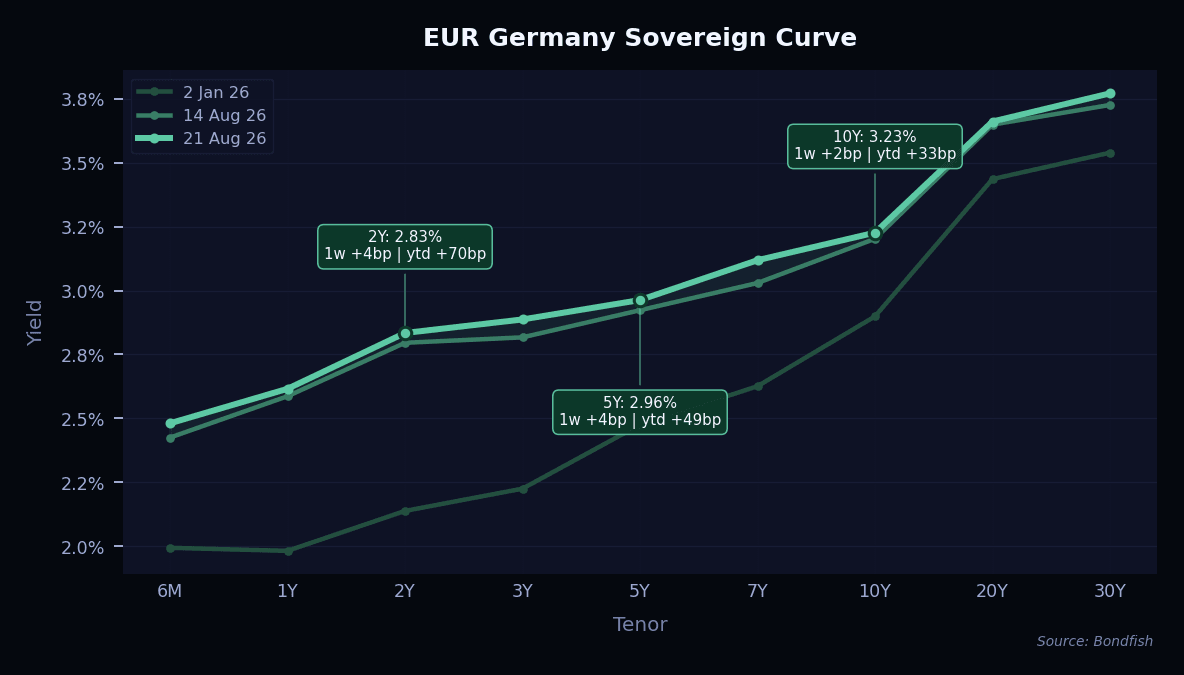
Last week was really a story about the long end of the government bond market, and it did not start well. Thirty-year yields in Japan, the United States and the UK pushed up towards their highest levels in decades, and that pull was felt everywhere, Germany included. Three things were behind it: government debt keeps growing in most large economies, companies are selling a lot of very long-dated bonds to fund artificial-intelligence projects, and energy prices are rising again. Europe then had a problem of its own. The 60-day negotiating window between the US and Iran expired without a deal, and European natural gas jumped to a post-conflict high of about €208 per megawatt hour. Higher energy costs feed into inflation, and higher inflation pushes yields up. Thin August trading made every move larger than it would normally be. Yields did come back down later in the week once the US Treasury stepped in — more on that below — but German yields still finished higher right across the curve, with the biggest rise in the five- to ten-year part. Friday's business surveys pointed the same way, with the euro-area composite index edging up to 52.1 and German manufacturing the bright spot.
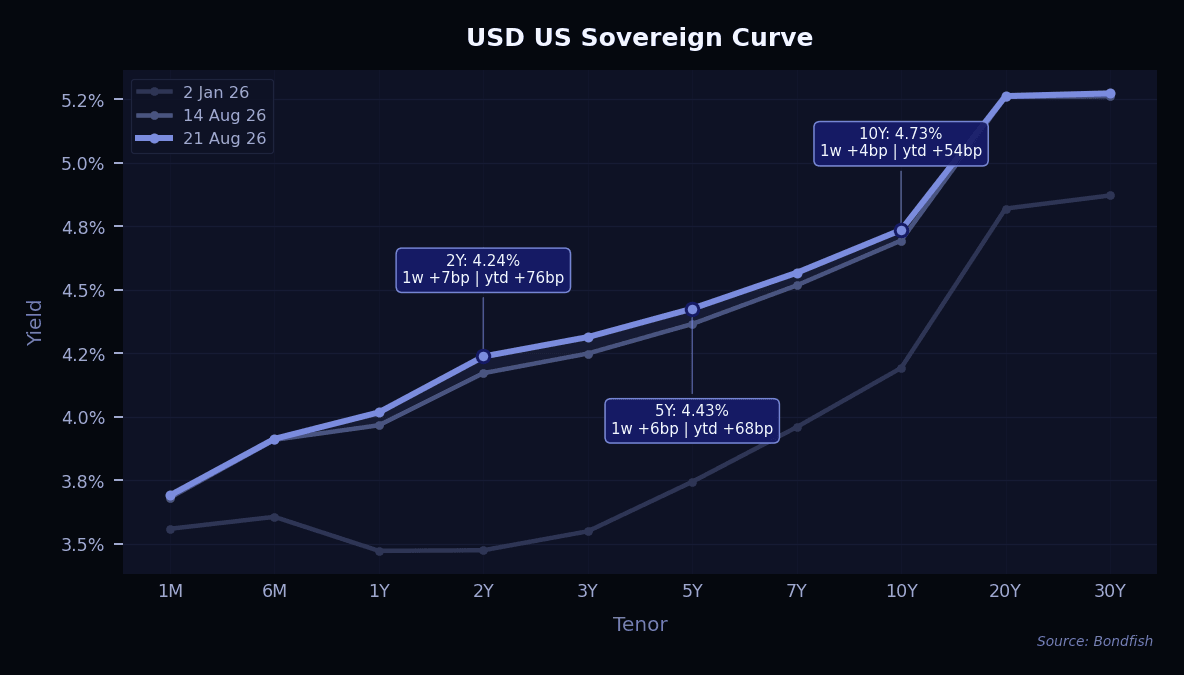
The US is where the week turned. Long-dated Treasury yields had been climbing for weeks, partly because investors want more compensation for locking money up for 20 or 30 years, and partly because rising Japanese long-term yields spill over into every other market. Then the Treasury made a surprise announcement: it will buy back at least $4 billion of long-dated bonds per operation, double the previous maximum of $2 billion. The timing was odd — just after the quarterly refunding and a day before a 20-year auction — and nothing in the market was broken enough to require it. Investors read it as a signal that officials are uncomfortable with how far long-term yields have climbed, and 20- and 30-year yields fell back. Over the week as a whole, short and medium maturities rose the most, while 20- and 30-year yields ended roughly where they started. Two things are worth keeping in mind. Almost all of this year's rise in yields comes from higher real yields, not from higher inflation expectations. And the buyback plan may not help for long: if the Treasury's borrowing becomes less predictable, investors could end up demanding more yield on long bonds, not less.
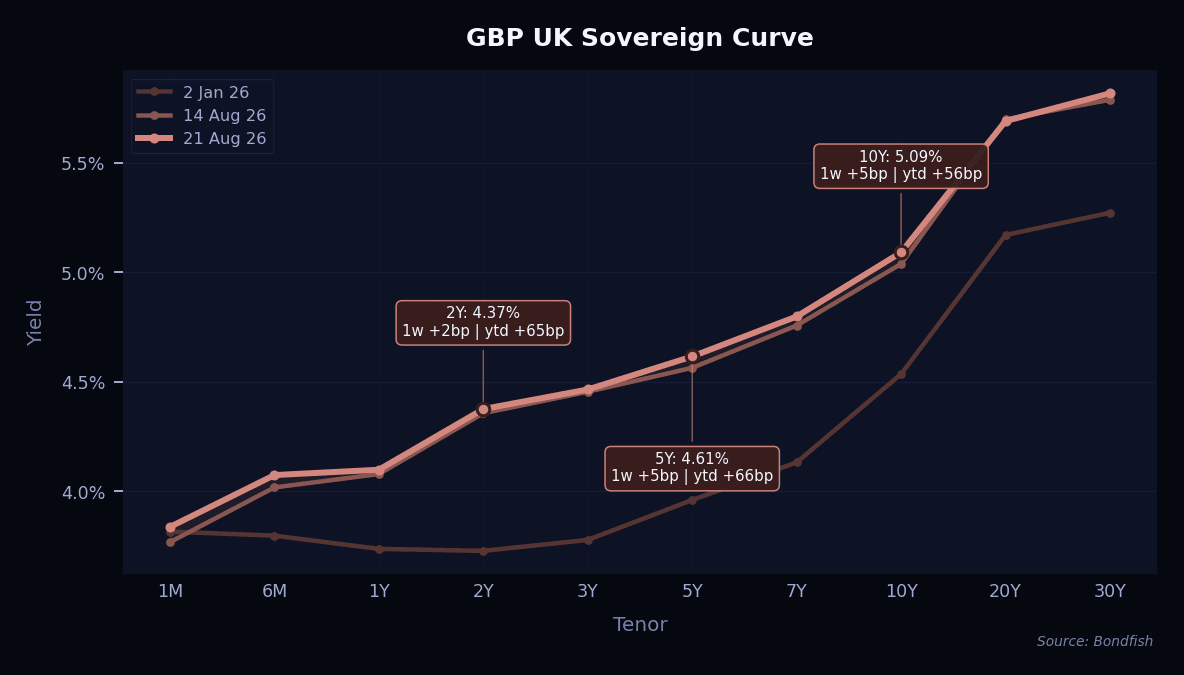
Gilts moved least of the three markets, but in the same direction. UK natural gas also hit a post-conflict high, around £208 per therm, which keeps inflation firmly in the picture. Long-dated gilt yields followed the global move higher and now sit around their highest levels since the financial crisis. The short end went the other way: traders see little chance of a Bank of England rate rise in September, so one- and two-year yields finished the week flat to slightly lower. The result was a slightly steeper curve — long maturities a couple of basis points higher, the front end unchanged.
Top gainers
Last week's biggest gainers were a mix of US corporate and higher-yielding bonds. Braskem Idesa led the list, and the reason is worth explaining. The Mexican petrochemicals producer filed for bankruptcy protection in the US last week, and the rating agencies duly marked it as in default — yet its bonds rose. This was a pre-agreed filing, made after creditors had already tabled restructuring proposals that include a cash injection into the business and collateral pledged against its assets. For holders of the secured 2032 bond, that points to a better recovery than the deeply discounted price had been assuming, which is why the bond went up rather than down. PayPal appeared twice, with its long-dated 2050 and 2052 bonds, and other risers included Discovery Communications, TVL Finance and Gray Television.
| Name | Cur | Price change 1w(%) |
Yield | Risk Level |
|---|---|---|---|---|
| Braskem Idesa 6.99% Feb 2032 | USD | 6,64% | 5,91% | |
| PayPal Hldg 3.25% Jun 2050 | USD | 3,78% | 5,62% | |
| Discovery Com 4.125% May 2029 | USD | 2,93% | 6,70% | |
| TVL Finance 10.25% Apr 2028 | GBP | 2,74% | 11,66% | |
| PayPal Hldg 5.05% Jun 2052 | USD | 2,13% | 6,08% | |
| Wurth Fin Intl 2.1% Nov 2026 | CHF | 1,97% | -7,02% | |
| West Allnce 3% Jun 2031 | USD | 1,69% | 0,62% | |
| Fiserv 4.4% Jul 2049 | USD | 1,54% | 6,27% | |
| Gray Television 4.75% Oct 2030 | USD | 1,53% | 9,83% |
Top losers
The fallers were almost all long-dated bonds — exactly the part of the market that suffers when 20- and 30-year yields climb, because a small move in yield translates into a large move in price. Kohl’s appeared twice, with its 2045 and 2031 bonds, alongside Cogent Communications, a long-dated Goldman Sachs 2034 bond, BBVA's 2050 issue, Whirlpool and Kyndryl.
| Name | Cur | Price change 1w(%) |
Yield | Risk Level |
|---|---|---|---|---|
| Kohls 5.55% Jul 2045 | USD | -4,65% | 9,19% | |
| Cogent Cmmns Grp 6.5% Jul 2032 | USD | -3,97% | 11,19% | |
| Goldman Sachs 4.75% Aug 2034 | USD | -3,87% | 5,49% | |
| Ukraine 4.5% Feb 2035 | USD | -3,45% | 12,68% | |
| MPT Opt Partner 3.5% Mar 2031 | USD | -3,29% | 15,44% | |
| Bbva Glo Secs 6.1% Aug 2050 | USD | -2,80% | 6,74% | |
| Kyndryl Holdings 4.1% Oct 2041 | USD | -2,63% | 7,43% | |
| Whirlpool 5.15% Mar 2043 | USD | -2,55% | 9,79% | |
| Kohls 5.125% May 2031 | USD | -2,54% | 7,90% | |
| Workday 3.8% Apr 2032 | USD | -2,44% | 5,23% |
Rating changes
Note: only long-term senior unsecured ratings were taken into account.
Upgrades outnumbered downgrades last week, in line with the steady improvement in credit ratings seen across investment-grade companies over the past couple of years. Among the better-known names, memory-chip maker SK hynix was raised to A- and Micron Technology moved up a notch, while Tapestry, the owner of Coach, and Singapore Telecommunications were also upgraded. Ireland's government rating was lifted to Aa2. On the downside, the standout was Cox Communications, cut into high-yield territory, while cosmetics group Coty was lowered to BB-. Braskem Idesa was moved to default after filing for a pre-agreed bankruptcy in the US.
| Issuer | Agency | Change |
|---|---|---|
| AIR Baltic | S&P | CCC- → SD |
| Athletico | S&P | CC → D |
| AvalonBay Communities | S&P | A- → A |
| Axactor | S&P | B- → B |
| Balcan Innovations | S&P | B- → CCC+ |
| Banka Kombetare Tregtare | S&P | BB- → BB |
| BRANICKS | S&P | SD → CCC- |
| Braskem Idesa | Fitch | RD → D |
| Caja Los Andes | Fitch | BBB- → BBB |
| California Resources | S&P | B+ → BB- |
| Corp Inmobiliaria Vesta | S&P | BBB- → BBB |
| Coty | Fitch | BB+ → BB- |
| Cox Communications | Fitch | BBB+ → BB+ |
| ERP Operating | S&P | A- → A |
| Filtration Group | S&P | B → BBB+ |
| Foundever | S&P | CCC → D |
| HSE Finance | S&P | CCC- → B- |
| HX Hold | Fitch | CCC- → C |
| Hyster-Yale | S&P | B → B- |
| IIFL Finance | Fitch | B+ → BB- |
| Leslie's Poolmart | S&P | CCC → CCC- |
| Liberty Communications of Puerto Rico | Fitch | CCC → CC |
| Light | Fitch | D → B- |
| Micron Technology | S&P | BBB → BBB+ |
| Mitnick Corporate Purchaser | Fitch | B- → CCC+ |
| NOVA Chemicals | Fitch | BB- → BB |
| PCF | S&P | CCC+ → SD |
| Pfleiderer | S&P | CCC+ → SD |
| Pretzel Parent | S&P | B → B- |
| Republic of Ireland | Moody's | Aa3 → Aa2 |
| Singapore Telecommunications | S&P | A → A+ |
| SK hynix | S&P | BBB+ → A- |
| Somnigroup International | S&P | BB → BB+ |
| Spencer Spirit | S&P | B+ → BB- |
| SSH Holdings | S&P | B+ → BB- |
| Summit Midstream | Fitch | B- → B |
| Tapestry | S&P | BBB → BBB+ |
| Toshiba | S&P | BB- → BB |
| Trident Energy | S&P | B- → B |
| Unibail-Rodamco-Westfield | Moody's | Baa2 → Baa1 |
| Vivmark Residential | S&P | A- → A |
| Wealthspire | S&P | B → B- |
| Webster Financial | S&P | BBB → BBB+ |
| XPO | S&P | BB → BB+ |
New issues
New bond sales came back strongly after the summer lull, making it the busiest week since early July. In Europe alone, 19 investment-grade borrowers raised €11 billion in euros and £1.6 billion in sterling, while high-yield issuance was completely absent. Banks and financial firms led the way, with large deals from Mizuho — whose €1.5 billion two-part deal was the biggest euro trade of the week — along with Credit Agricole, Santander, ICICI Bank, Kotak Mahindra Bank and Bank of New York Mellon.
Governments and agencies were just as active. Germany sold a 30-year bond into the middle of the long-end sell-off, and Finland, KfW, the European Investment Bank and the International Bank for Reconstruction and Development each raised multi-billion amounts. Buyers were still there: European investment-grade funds took in fresh money over the week, though almost all of it went into short-dated strategies rather than long bonds.
| Issuer | Size | Term | Yield | Risk Level |
|---|---|---|---|---|
| Agence France Locale | EUR 0,50bn | 8Y | 4,1% | |
| ISIN (CUSIP)FR001401AN14 | ||||
| Ameren Illinois | USD 0,40bn | 10Y | 5,5% | |
| ISIN (CUSIP)02361DBD1 | ||||
| Arkea Public Sector SCF | EUR 0,50bn | 8Y | 3,7% | |
| ISIN (CUSIP)FR001401AMG9 | ||||
| Asian Development Bank | USD 2,0bn | 10Y | 4,7% | |
| ISIN (CUSIP)US045167GT47 | ||||
| Athene Global Funding | USD 0,50bn | 3–5Y | 5,1–5,5% | |
| ISIN (CUSIP)US04686E5N86…US04686E5P35 | ||||
| Avnet | USD 0,55bn | 5Y | 5,7% | |
| ISIN (CUSIP)053807BA0 | ||||
| Banco Santander | USD 2,0bn | 4–8Y | 5,0–5,6% | |
| ISIN (CUSIP)US05971KAZ21…US05971KBA60 | ||||
| Bank of New York Mellon | USD 1,6bn | 2–3Y | 4,6%; FLOAT, +43bp | |
| ISIN (CUSIP)US06405LAL53 | ||||
| Bank of New Zealand | EUR 1,0bn | 5Y | 3,4% | |
| ISIN (CUSIP)XS3476693778 | ||||
| Banque Federative Du Credit Mutuel | EUR 0,75bn | 11Y | 4,5% | |
| ISIN (CUSIP)FR001401AN55 | ||||
| Belfius Banque | EUR 0,75bn | 7Y | 3,9% | |
| ISIN (CUSIP)BE6376796163 | ||||
| Blackstone Private Credit Fund | USD 0,75bn | 5Y | 6,4% | |
| ISIN (CUSIP)09261HCD7 | ||||
| Blue Owl Technology Finance | USD 0,40bn | 3Y | 6,7% | |
| ISIN (CUSIP)US095924AD81 | ||||
| BNG Bank | USD 1,2bn | 2Y | 4,3% | |
| ISIN (CUSIP)XS3481696618 | ||||
| Boston Properties | USD 0,70bn | 10Y | 6,1% | |
| ISIN (CUSIP)10112RBP8 | ||||
| Bunge Finance | USD 0,60bn | 5Y | 5,1% | |
| ISIN (CUSIP)120568BU3 | ||||
| Continental | EUR 0,75bn | 4Y | 3,7% | |
| ISIN (CUSIP)XS3478305777 | ||||
| Corebridge Financial | USD 0,75bn | 10Y | 5,9% | |
| ISIN (CUSIP)US21871XAV10 | ||||
| CPPIB Capital | USD 2,0bn | 3Y | 4,4% | |
| ISIN (CUSIP)US22411WBJ45 | ||||
| Credit Agricole | EUR 1,0bn | 6Y | 3,9% | |
| ISIN (CUSIP)FR001401AKZ3 | ||||
| Credit Agricole Home Loan SFH | EUR 2,5bn | 3–10Y | 3,2–3,8%; FLOAT, +24bp | |
| ISIN (CUSIP)FR001401AM72…FR001401AM80 | ||||
| Ctp | EUR 0,50bn | 3Y | 3,7% | |
| ISIN (CUSIP)XS3480651812 | ||||
| DBS Bank | EUR 2,0bn | 4Y | 3,2% | |
| ISIN (CUSIP)XS3479188222 | ||||
| Dekabank Deutsche Girozentrale | EUR 0,25bn | 4Y | 3,2% | |
| ISIN (CUSIP)XS3479243183 | ||||
| Deutsche Telekom | GBP 0,40bn | 20Y | 6,5% | |
| ISIN (CUSIP)XS3481540105 | ||||
| Development Bank of Japan | USD 1,0bn | 3Y | 4,5% | |
| ISIN (CUSIP)XS3471464399 | ||||
| European Investment Bank | USD 4,0bn | 5Y | 4,4% | |
| ISIN (CUSIP)US298785KU94 | ||||
| Evergy | USD 0,60bn | 30Y | 6,4% | |
| ISIN (CUSIP)US30034WAG15 | ||||
| Republic of Finland | EUR 4,0bn | 7Y | 3,3% | |
| ISIN (CUSIP)FI4000609516 | ||||
| Germany | EUR 4,0bn | 30Y | 3,8% | |
| ISIN (CUSIP)DE000BU2D012 | ||||
| Gray Media | USD 0,75bn | 8Y | 7,5% | |
| ISIN (CUSIP)USU4248MAC65 | ||||
| ICICI Bank | USD 0,75bn | 5Y | 5,4% | |
| ISIN (CUSIP)USY38604AB36 | ||||
| International Bank for Reconstruction and Development | USD 4,0bn | 7Y | 4,6% | |
| ISIN (CUSIP)US459058MC43 | ||||
| Interstate Power And Light | USD 0,50bn | 5Y | 5,1% | |
| ISIN (CUSIP)461070AZ7 | ||||
| Jyske Realkredit | EUR 0,50bn | 5Y | 3,3% | |
| ISIN (CUSIP)DK0009420655 | ||||
| KB Securities | USD 0,30bn | 3Y | 5,1% | |
| ISIN (CUSIP)XS3464389678 | ||||
| KfW | EUR 5,0bn | 3Y | 3,0% | |
| ISIN (CUSIP)XS3480769069 | ||||
| Korea SMEs and Startups Agency | USD 0,40bn | 4Y | 4,7% | |
| ISIN (CUSIP)HK0001325593 | ||||
| Kotak Mahindra Bank | USD 0,65bn | 5Y | 5,5% | |
| ISIN (CUSIP)XS3480765588 | ||||
| Landwirtschaftliche Rentenbank | EUR 1,2bn | 7Y | 3,3% | |
| ISIN (CUSIP)XS3481545088 | ||||
| LHV Group | EUR 0,20bn | 4Y | 4,6% | |
| ISIN (CUSIP)XS3448593023 | ||||
| Lloyds Bank | USD 1,5bn | 3Y | 4,5% | |
| ISIN (CUSIP)XS3479603733 | ||||
| Luso International Banking | USD 0,10bn | PERP | 6,6% | |
| ISIN (CUSIP)MO0000000634 | ||||
| Macquarie Group | GBP 0,50bn | 4Y | 5,3% | |
| ISIN (CUSIP)XS3482734186 | ||||
| Metropolitan Life Global Funding I | GBP 0,40bn | 6Y | 5,4% | |
| ISIN (CUSIP)XS3478195491 | ||||
| Mitsui | USD 0,75bn | 5Y | 4,9% | |
| ISIN (CUSIP)XS3459991751 | ||||
| Mizuho Financial Group | EUR 1,5bn | 6–12Y | 3,9–4,3% | |
| ISIN (CUSIP)XS3470748883…XS3470748966 | ||||
| National Australia Bank | USD 1,8bn | 5Y | 4,6% | |
| ISIN (CUSIP)USQ6535DCT92 | ||||
| NatWest Markets | USD 0,50bn | 5Y | FLOAT, +95bp | |
| ISIN (CUSIP)XS3478143004 | ||||
| Nederlandse Waterschapsbank | GBP 0,25bn | 5Y | 4,7% | |
| ISIN (CUSIP)XS3479661855 | ||||
| Nordea Bank | EUR 0,75bn | 7Y | 3,7% | |
| ISIN (CUSIP)XS3479233200 | ||||
| North Rhine-Westphalia | EUR 1,5bn | 7Y | 3,3% | |
| ISIN (CUSIP)DE000NRW0QR6 | ||||
| Northern Oil and Gas | USD 0,50bn | 8Y | 7,5% | |
| ISIN (CUSIP)US665531AM10 | ||||
| Northwestern Mutual Global Funding | GBP 0,30bn | 5Y | 5,3% | |
| ISIN (CUSIP)XS3480654675 | ||||
| Ocean Yield | USD 0,10bn | PERP | FLOAT, +350bp | |
| ISIN (CUSIP)NO0013759829 | ||||
| Oversea-Chinese Banking Corp | GBP 1,0bn | 3Y | FLOAT, +48bp | |
| ISIN (CUSIP)XS3481584657 | ||||
| Raiffeisen Bank | EUR 0,60bn | 6Y | 4,6% | |
| ISIN (CUSIP)XS3478186151 | ||||
| Raiffeisen Bank International | EUR 0,75bn | 10Y | 4,5% | |
| ISIN (CUSIP)XS3480675597 | ||||
| Raiffeisen Landesbank Steiermark | EUR 0,50bn | 5Y | 3,3% | |
| ISIN (CUSIP)AT0000A3WQC0 | ||||
| Sika Capital | EUR 1,0bn | 30Y | 4,5–5,0% | |
| ISIN (CUSIP)XS3476053445…XS3476053791 | ||||
| Skandinaviska Enskilda Banken | EUR 1,5bn | 3Y | 3,2%; FLOAT, +18bp | |
| ISIN (CUSIP)XS3482637496 | ||||
| Southern California Gas | USD 0,50bn | 10Y | 5,6% | |
| ISIN (CUSIP)US842434DF68 | ||||
| SpareBank 1 Boligkreditt | EUR 1,0bn | 7Y | 3,4% | |
| ISIN (CUSIP)XS3482718734 | ||||
| SpareBank 1 Sor-Norge | EUR 0,50bn | 5Y | 3,6% | |
| ISIN (CUSIP)XS3480525867 | ||||
| Swisscom Finance | EUR 0,50bn | PERP | 4,2% | |
| ISIN (CUSIP)XS3460850616 | ||||
| Tatra Banka | EUR 0,60bn | 3Y | 3,3% | |
| ISIN (CUSIP)SK4000030193 | ||||
| Thales | EUR 1,0bn | 4–8Y | 3,5–3,8% | |
| ISIN (CUSIP)FR001401AM07…FR001401AM15 | ||||
| Tractor Supply | USD 0,50bn | 5Y | 5,2% | |
| ISIN (CUSIP)892356AC0 | ||||
| Volvo Treasury | EUR 0,50bn | 3Y | 3,4% | |
| ISIN (CUSIP)XS3479662234 | ||||
| Vylor | USD 1,1bn | 5–10Y | 5,2–5,7% | |
| ISIN (CUSIP)USU92928AB30…USU92928AC13 | ||||
| Wealthspire | USD 0,30bn | 8Y | 9,0% | |
| ISIN (CUSIP)USU9430XAA38 | ||||
| Wisconsin Electric Power | USD 0,30bn | 10Y | 5,4% | |
| ISIN (CUSIP)976656CY2 | ||||
This article does not constitute investment advice or personal recommendation. Investments in securities and other financial instruments always involve the risk of loss of your capital. Past performance is not a reliable indicator of future results. Bondfish does not recommend using the data and information provided as the only basis for making any investment decision. You should not make any investment decisions without first conducting your own research and considering your own financial situation.