Weekly bond digest: July 20 – July 26, 2026
Yield Curves
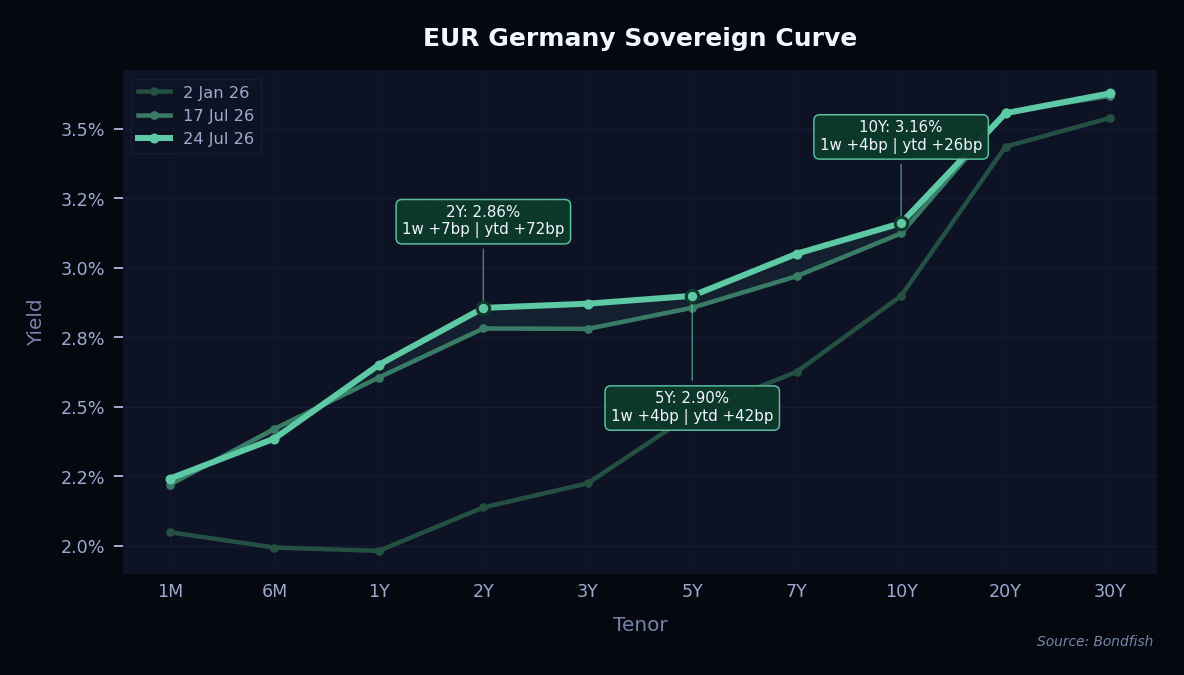
German yields rose again this week, with most of the move in medium- and long-dated bonds. The 2-year added about 4 basis points to 2.83%, the 5-year rose 7 to 2.93%, and the 10-year climbed to around 3.18%. Governments across Europe are selling record amounts of debt to cover their deficits, and that steady supply keeps pushing prices down and yields up. Inflation in services is also proving sticky, so the European Central Bank is in no hurry to cut rates — which kept very short-dated yields roughly flat while longer maturities drifted higher. A fresh jump in European gas prices added to the inflation worry.
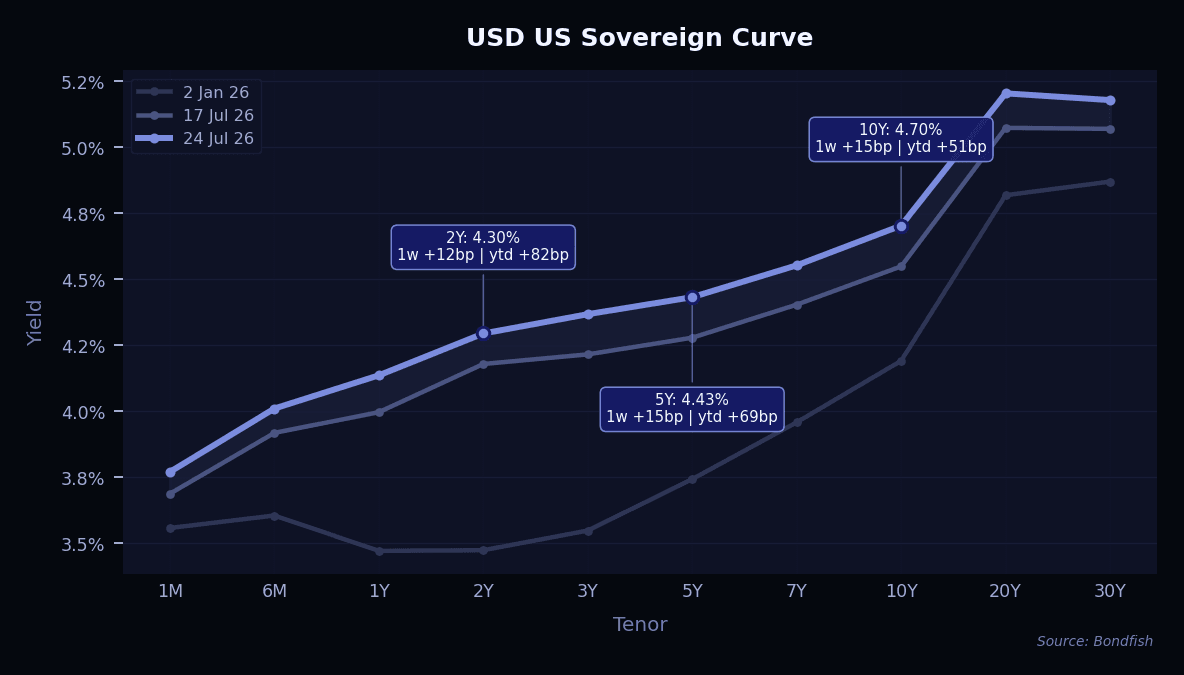
US Treasury yields rose across the board, with the sharpest moves in the 2- to 5-year part of the curve — all up roughly 14 basis points. The 2-year ended near 4.33%, the 5-year at 4.42% and the 10-year at 4.67%. The main driver is inflation that refuses to fall back to target: at around 3.5%, it has pushed investors to give up on hopes of quick rate cuts. The Federal Reserve's new leadership has been clear it wants inflation back at 2% and is in no rush to ease. On top of that, the Treasury is issuing huge amounts of debt to fund a deficit running above 6% of GDP, and investors want extra yield to absorb it.
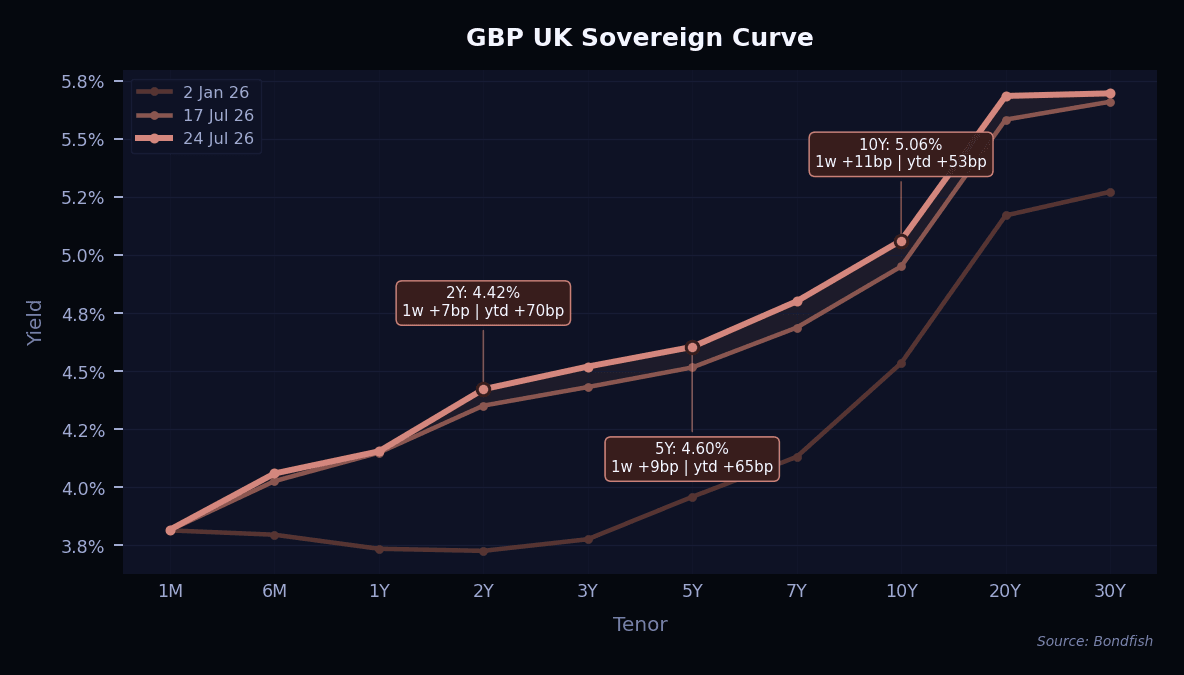
UK gilt yields followed the same path, rising most in maturities from 2 to 10 years — up 6 to 8 basis points — while the very front of the curve barely moved. The 2-year finished around 4.41%, the 5-year at 4.59% and the 10-year at 5.03%, still the highest of the three regions. Sticky inflation and a heavy schedule of government bond sales are the main forces, and higher yields elsewhere pulled UK yields along with them. With the Bank of England expected to hold steady for now, short-dated yields stayed anchored while longer bonds did the moving.
With yields still drifting higher and central banks in no rush to cut, the tone this week favoured shorter and intermediate maturities — where yields are already generous and price swings are milder — over adding fresh long-dated exposure.
Top gainers
Last week's gainers were a mix of higher-risk, high-yield names, and the moves were modest — all between about 1.1% and 1.7%. Clearwater and Nordstrom led, with Compass, Coterra Energy and LXP Industrial also higher. Cellnex Fin Co, Cleveland-Cliffs and ASGN rounded out the list, along with Central Bank of Tunisia's 2027 dollar bond.
| Name | Cur | Price change 1w(%) |
Yield | Risk Level |
|---|---|---|---|---|
| Clearwater 4.75% Aug 2028 | USD | 1,65% | 13,10% | |
| Nordstrom 5% Jan 2044 | USD | 1,62% | 7,88% | |
| LXP Industrial 2.375% Oct 2031 | USD | 1,34% | 4,88% | |
| Compass 5% Jan 2032 | USD | 1,15% | 6,64% | |
| Coterra Energy 5.4% Feb 2035 | USD | 1,14% | 5,68% | |
| Central Bank Tunisia 8.25% Sep 2027 | USD | 1,13% | 5,28% | |
| Cellnex Fin Co 2% Feb 2033 | EUR | 1,11% | 3,79% | |
| Cleveland-Cliffs 7.375% May 2033 | USD | 1,08% | 6,82% | |
| ASGN 4.625% May 2028 | USD | 1,07% | 8,24% |
Top losers
The losers were led by stressed high-yield names and long-dated bonds. Getty Images and MPH Acquisition each fell about 6%, and Atos slid again. The bigger story sits with long-maturity high-grade bonds: Oracle's 2047 and 2052 issues and Meta Platforms' 2053 bond all dropped 4% or more as long-term yields pushed higher. Whirlpool's 2033 and 2034 bonds and Virgin Media O2's 2032 sterling bond also lost ground.
| Name | Cur | Price change 1w(%) |
Yield | Risk Level |
|---|---|---|---|---|
| Getty Images 11.25% Feb 2030 | USD | -6,01% | 19,54% | |
| MPH Acquisition 5.75% Dec 2030 | USD | -6,01% | 12,29% | |
| Bluenord 12% Jul 2085 | USD | -5,22% | 0,01% | |
| Whirlpool 5.5% Mar 2033 | USD | -4,56% | 10,76% | |
| Virgin Media O2 7.875% Mar 2032 | GBP | -4,40% | 14,29% | |
| Oracle 4% Nov 2047 | USD | -4,31% | 7,69% | |
| Oracle 6.9% Nov 2052 | USD | -4,21% | 8,03% | |
| Atos 5% Dec 2030 | EUR | -4,19% | 5,53% | |
| Whirlpool 5.75% Mar 2034 | USD | -4,14% | 10,87% | |
| Meta Platforms 5.6% May 2053 | USD | -4,06% | 6,87% |
Rating changes
Note: only long-term senior unsecured ratings were taken into account.
Upgrades outnumbered downgrades this week. The standout was Argentina, lifted a notch to B3 and out of the CCC/Caa danger zone, while Greece's Piraeus Bank climbed back to investment grade and insurer Liberty Mutual edged up a notch. Hawaiian Electric and healthcare-software firm Waystar were also raised. On the downside, catering group Sodexo and homebuilder KB Home were each cut one notch, and a cluster of smaller, already-distressed borrowers — including Aventiv, Securus and System1 — were pushed into default.
| Issuer | Agency | Change |
|---|---|---|
| Argentine Republic | Moody's | Caa1 → B3 |
| Asmodee | S&P | BB- → BB |
| ASP Unifrax | S&P | CCC → CC |
| Aventiv Technologies | S&P | CC → D |
| Banistmo | S&P | BB- → BB |
| Bright Food International | S&P | BBB- → BBB |
| China CITIC Financial Asset Management | Fitch | BBB → BBB+ |
| Cia General de Combustibles | S&P | CCC+ → B- |
| Constellation Oil Services | Fitch | B → B+ |
| Cornerstone OnDemand | S&P | B- → CCC+ |
| DXP Enterprises | S&P | B → B+ |
| Energeticky a Prumyslovy Holding | Fitch | BBB- → BBB |
| EP Infrastructure | Fitch | BBB- → BBB |
| Eurotelesites | Fitch | BBB- → BBB |
| Family Dollar Stores | S&P | B (new) |
| Franklin Square | S&P | BB → BB- |
| Frigorifico Concepcion | Fitch | CC → C |
| Gulfport Energy Operating | S&P | B+ → BB- |
| Hawaiian Electric | S&P | B+ → BB- |
| HSE Finance | S&P | B- → CCC- |
| KB Home | S&P | BB+ → BB |
| Liberty Mutual | S&P | BBB → BBB+ |
| Magenta Buyer | S&P | CCC+ → CCC |
| Orchid Merger Sub II | S&P | CC → D |
| Pakistan Federal Investment Bonds | S&P | B- → B |
| Piraeus Bank | S&P | BB+ → BBB- |
| Proofpoint | S&P | B- → B |
| Public Power | Fitch | BB- → BB |
| Richmond Housing Partnership | S&P | A → A- |
| Securus | S&P | CC → D |
| Sirona HoldCo | S&P | SD → CCC- |
| Sodexo | S&P | BBB+ → BBB |
| Sonicwall | S&P | D → CCC+ |
| SPP-Distribucia | Fitch | A- → A |
| System1 | S&P | CC → D |
| Universal Entertainment | Fitch | B- → CCC+ |
| Victoria | Fitch | CCC → CCC- |
| VS Holding I | S&P | B+ → B |
| Waystar | Fitch | BB → BB+ |
New issues
It was a busy week for new bond sales. Governments led the way, with Kuwait raising $6 billion and Malaysia also tapping the market, alongside banks such as Goldman Sachs, US Bancorp and Truist Financial. The clearest sign of the moment was Galaxy Helios Data Centers, which sold $3.5 billion at a 10% yield — part of the wave of borrowing tied to artificial intelligence and data-centre build-out now flooding the corporate bond market. Demand stayed firm overall, but investors are growing pickier as the sheer volume of new supply piles up.
| Issuer | Size | Term | Yield | Risk Level |
|---|---|---|---|---|
| AA Bond Co | GBP 0,40bn | 4Y | 6,0% | |
| ISIN (CUSIP)XS3451648557 | ||||
| African Export Import Bank | USD 1,5bn | 6–10Y | 6,2–7,1% | |
| ISIN (CUSIP)XS3437376703…XS3437376612 | ||||
| Athenahealth | USD 0,50bn | 6Y | 7,5% | |
| ISIN (CUSIP)USU04754AA27 | ||||
| Boston Gas | USD 0,50bn | 10Y | 5,7% | |
| ISIN (CUSIP)USU0568KAG14 | ||||
| CGE Treasury IFSC | USD 0,39bn | 5Y | 7,9% | |
| ISIN (CUSIP)XS3451576899 | ||||
| Citizens Financial Group | USD 0,40bn | PERP | 6,8% | |
| ISIN (CUSIP)US174610BL82 | ||||
| CMB International Leasing Management | USD 0,60bn | 3Y | FLOAT, +47bp | |
| ISIN (CUSIP)XS3443285013 | ||||
| Conagra Brands | USD 0,50bn | 5Y | 5,4% | |
| ISIN (CUSIP)205887CM2 | ||||
| Constellation Oil Services | USD 0,65bn | 7Y | 7,7% | |
| ISIN (CUSIP)USL1965HAH32 | ||||
| Covivio | EUR 0,50bn | 7Y | 4,2% | |
| ISIN (CUSIP)FR001401A6Z6 | ||||
| Development Bank of Mongolia | USD 0,25bn | 5Y | 7,1% | |
| ISIN (CUSIP)USY2056PAJ58 | ||||
| Freedom Mortgage Holdings | USD 0,50bn | 6Y | 8,0% | |
| ISIN (CUSIP)USU3134EAA74 | ||||
| Fubon Life Singapore | USD 0,35bn | 15Y | 6,0% | |
| ISIN (CUSIP)XS3384667146 | ||||
| Galaxy Helios Data Centers II | USD 3,5bn | 5Y | 10,0% | |
| ISIN (CUSIP)USU3190CAA28 | ||||
| Goldman Sachs Group | USD 2,5bn | PERP | 6,5% | |
| ISIN (CUSIP)US38141GF665 | ||||
| Hanwha Aerospace | USD 0,50bn | 3Y | 5,1% | |
| ISIN (CUSIP)XS3448558893 | ||||
| Hercules Capital | USD 0,33bn | 5Y | 6,6% | |
| ISIN (CUSIP)US42711MAB90 | ||||
| Howard Midstream Energy Partners | USD 0,65bn | 8Y | 6,6% | |
| ISIN (CUSIP)USU4425TAE20 | ||||
| ICICI Bank | USD 1,0bn | 5Y | 5,5% | |
| ISIN (CUSIP)USY38604AA52 | ||||
| Korea Midland Power | USD 0,30bn | 3Y | 4,8% | |
| ISIN (CUSIP)XS3441682534 | ||||
| Kuwait | USD 6,0bn | 3–10Y | 5,0–5,5% | |
| ISIN (CUSIP)XS3443185650…XS3443187516 | ||||
| Landeskreditbank Baden Wuerttemberg Foerderbank | EUR 0,12bn | 3Y | 3,1% | |
| ISIN (CUSIP)DE000A352QN4 | ||||
| Landeskreditbank Baden Wuerttemberg Foerderbank | USD 1,5bn | 3Y | 4,4% | |
| ISIN (CUSIP)XS3455113186 | ||||
| Leasys | EUR 0,75bn | 4Y | 3,7% | |
| ISIN (CUSIP)XS3451580735 | ||||
| Magnolia Oil & Gas | USD 0,50bn | 8Y | 6,6% | |
| ISIN (CUSIP)USU55641AC57 | ||||
| Malaysia | USD 1,5bn | 6–10Y | 4,9% | |
| ISIN (CUSIP)USY5749NAB39 | ||||
| Mitsubishi HC Capital UK | EUR 0,50bn | 3Y | 3,6% | |
| ISIN (CUSIP)XS3450069748 | ||||
| Netflix | USD 1,0bn | 10Y | 5,3% | |
| ISIN (CUSIP)US64110LBB18 | ||||
| Nomad Foods | EUR 0,80bn | 7Y | 5,2% | |
| ISIN (CUSIP)XS3453584800 | ||||
| Petroquimica Comodoro Rivadavia | USD 0,38bn | 8Y | 8,6% | |
| ISIN (CUSIP)USP7865PAA41 | ||||
| Pinewood | GBP 0,30bn | 6Y | 6,4% | |
| ISIN (CUSIP)XS3444188968 | ||||
| Saturn Oil & Gas | USD 0,57bn | 5Y | 8,5% | |
| ISIN (CUSIP)USC8185KAB82 | ||||
| State Street Bank | USD 1,2bn | 3–8Y | 4,7–5,2% | |
| ISIN (CUSIP)US85744NAE13…US85744NAF87 | ||||
| Sunrise HoldCo IV | EUR 0,50bn | 7Y | 5,0% | |
| ISIN (CUSIP)XS3452875233 | ||||
| Taizhou Urban Construction and Investment Development Group | USD 0,40bn | 3Y | 4,4% | |
| ISIN (CUSIP)XS3435515179 | ||||
| Travelers Companies | USD 0,75bn | 5Y | 5,0% | |
| ISIN (CUSIP)US89417EAV11 | ||||
| Truist Financial | USD 1,2bn | 4Y | 5,0% | |
| ISIN (CUSIP)US89788MAZ59 | ||||
| Turkiye Is Bankasi | USD 0,50bn | 12Y | 8,4% | |
| ISIN (CUSIP)XS3431962532 | ||||
| US Bancorp | USD 2,0bn | 4–11Y | 4,9–5,5% | |
| ISIN (CUSIP)US91159HKA76…US91159HKB59 | ||||
| Yi Bright International | USD 0,11bn | 3Y | 5,2% | |
| ISIN (CUSIP)XS3447813380 | ||||
This article does not constitute investment advice or personal recommendation. Investments in securities and other financial instruments always involve the risk of loss of your capital. Past performance is not a reliable indicator of future results. Bondfish does not recommend using the data and information provided as the only basis for making any investment decision. You should not make any investment decisions without first conducting your own research and considering your own financial situation.