Weekly bond digest: October 19 – October 25, 2026
Investors ran for safety this week. AI-related shares kept falling, and Meta dropped about 7% after its results. French bonds came under heavy pressure too: their 10-year yield gap over Germany widened by more than 30 basis points to about 172, near its euro-crisis highs. On Friday Moody's kept France's rating at Aa3 instead of the expected cut, but it made that decision before the protests and this week's jump in French yields.
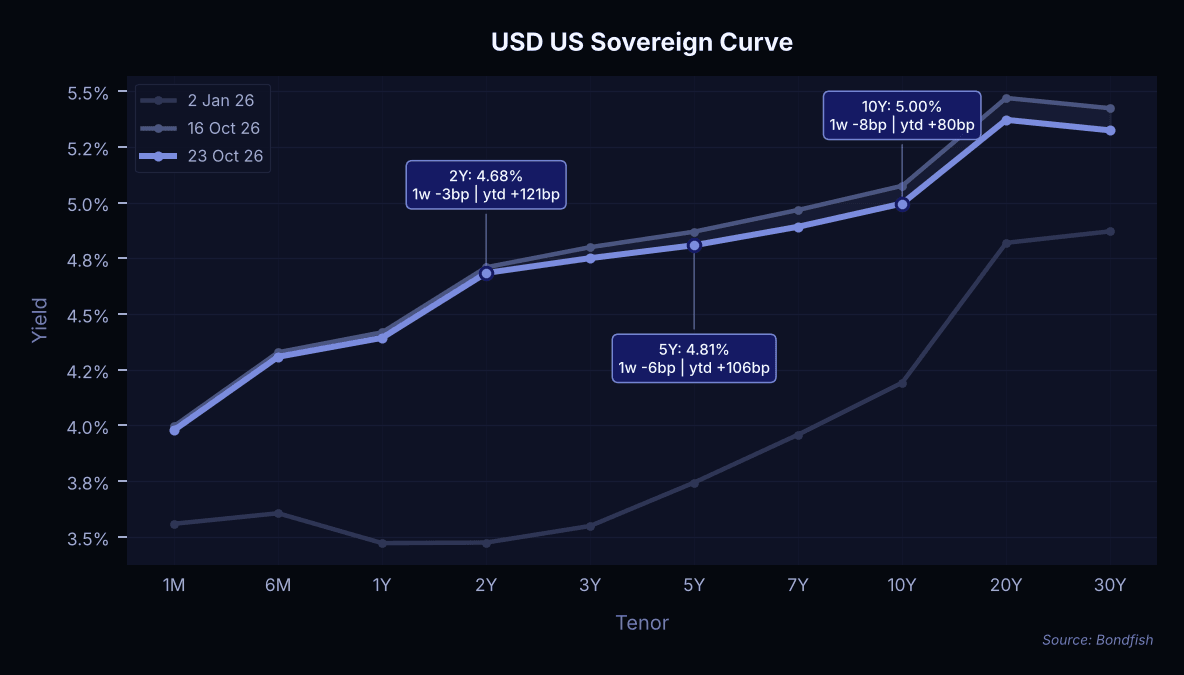
Safe government bonds gained. The 10-year US Treasury yield fell from 5.07% to 5.00%, and Wednesday brought its biggest one-day drop since the US regional bank failures of March 2023. German yields fell too.
Riskier debt went the other way. The extra yield on US junk bonds rose to a 17-month high, and companies delayed more than $5 billion of bond and loan sales this month. Virgin Media O2's bonds took four of the five biggest drops in our table.
Yield Curves
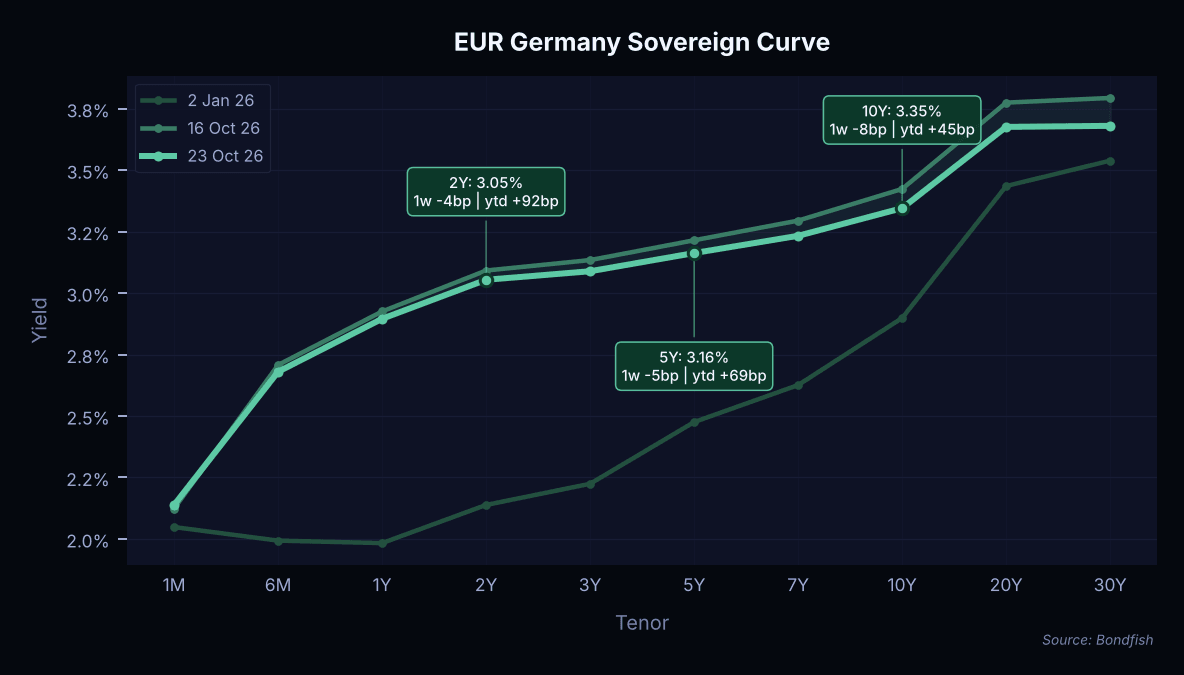
German government bonds rallied as investors looked for safety. The 10-year yield fell 8 basis points to 3.35%, and the 30-year dropped 11 basis points to 3.68%, while the 2-year slipped 4 basis points to 3.05%. Two things drove the move: falling technology shares and growing stress in French bonds. The gap between French and German 10-year yields widened by more than 30 basis points to about 172. There was no single trigger: sentiment toward France has been weakening for weeks, and protests last weekend added to the worries. The gap between Italian and German 10-year yields also widened, by 16 basis points to 122. The European Central Bank meets on October 29 and is expected to keep rates on hold.
US Treasuries also rallied, led by long-term bonds. The 10-year yield fell 8 basis points to 5.00%, the 30-year dropped 10 basis points to 5.32%, and the 2-year eased 3 basis points to 4.68%. On Wednesday the 10-year yield had its biggest one-day fall since the US regional bank failures of March 2023. Investors bought Treasuries as a safe place while French bonds came under stress and AI-related shares fell. Markets now expect fewer Fed rate rises over the next year, and a December hike is no longer fully priced in. The Fed meets on October 28 and is widely expected to hold rates.
UK gilts moved in two directions. The 2-year yield rose 4 basis points to 4.91%, while the 10-year dipped 2 basis points to 5.36% and the 30-year fell 8 basis points to 5.76%. Short-term yields rose because strong data made a Bank of England rate rise in November look almost certain. Unemployment fell from 4.9% to 4.7%, and inflation rose to 3.5%, slightly above forecasts. Long-term gilts gained on expectations that the government will sell fewer long-dated bonds after Chancellor John Healey's budget on October 28.
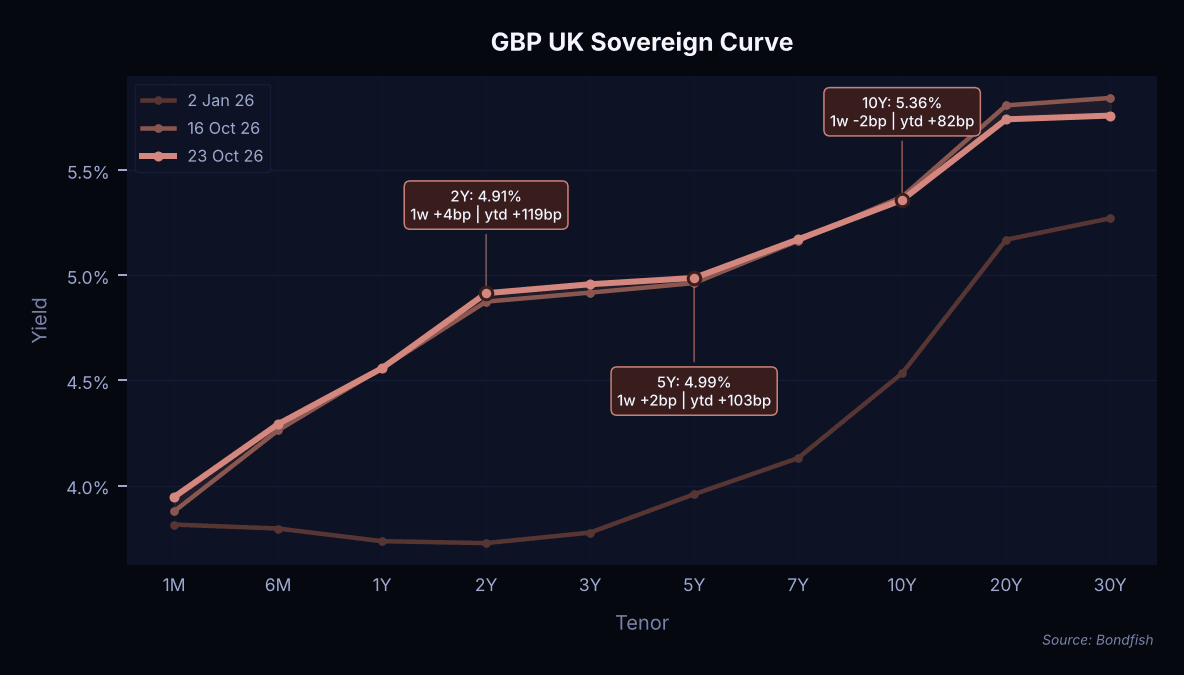
For long-term investors who can accept short-term price swings, medium-term German government bonds and 10-year UK gilts, now yielding about 5.36%, look attractive at today's levels.
Top gainers
Ukraine's 2035 bond led the gainers, up 4.7%, in a week when Russia and Ukraine agreed a local ceasefire and planned new peace talks for November. Paramount Global's 2031 bond rose 4.0%, recovering last week's 3.7% drop. IT services company Atos's 2030 bond gained 3.1%. Its operations generated cash in the third quarter for the first time since its turnaround plan began, and it confirmed its full-year targets. Long-dated bonds also rose as government bond yields fell: Ireland's 2055 bond and Bahrain's 2037 dollar bond each gained 2.1%.
| Name | Cur | Price change 1w (%) |
Yield | Risk Level |
|---|---|---|---|---|
| Ukraine 4.5% Feb 2035 | USD | 4,70% | 14,33% | |
| Paramount Global 4.95% Jan 2031 | USD | 3,97% | 9,73% | |
| Atos 5% Dec 2030 | EUR | 3,07% | 8,61% | |
| Ireland 3.15% Oct 2055 | EUR | 2,14% | 3,80% | |
| Bahrain 7.5% Jul 2037 | USD | 2,11% | 8,34% | |
| Ireland 2% Feb 2045 | EUR | 2,08% | 3,67% | |
| MIT USA 4.678% Jul 2114 | USD | 1,92% | 6,03% | |
| Caltech 3.65% Sep 2119 | USD | 1,84% | 6,06% | |
| EU 3.75% Apr 2042 | EUR | 1,80% | 4,01% | |
| US Treasury 4.625% Nov 2044 | USD | 1,65% | 5,35% |
Top losers
Riskier bonds fell as the extra yield on US junk bonds rose to a 17-month high. UK telecoms group Virgin Media O2 took four of the five biggest drops: its bonds, listed as Virgin Secured and Vmed UK, lost between 4.9% and 6.4%. Its debt has been under pressure since the UK competition regulator raised concerns this month about a deal that was expected to bring in about £1 billion to cut debt. Cable companies were also among the weakest parts of the junk bond market this week. Student lender Navient's 2030 bond fell 5.0% in the wider sell-off.
| Name | Cur | Price change 1w (%) |
Yield | Risk Level |
|---|---|---|---|---|
| Virgin Secured 4.25% Jan 2030 | GBP | -6,39% | 18,47% | |
| Vmed UK 5.625% Apr 2032 | EUR | -5,94% | 15,11% | |
| Virgin Secured 4.125% Aug 2030 | GBP | -5,70% | 16,32% | |
| Navient 9.375% Jul 2030 | USD | -4,99% | 9,93% | |
| Vmed UK 4% Jan 2029 | GBP | -4,93% | 19,77% | |
| Virgin Secured 5.25% May 2029 | GBP | -4,73% | 19,31% | |
| Gabon 6.625% Feb 2031 | USD | -4,17% | 13,81% | |
| Pegasus Hava 8% Sep 2031 | USD | -3,62% | 11,45% | |
| Ecuador 5% Jul 2040 | USD | -3,43% | 10,92% | |
| Community Health Systems 9.75% Jan 2034 | USD | -2,93% | 10,63% |
Rating changes
Note: only long-term senior unsecured ratings were taken into account.
Downgrades outnumbered upgrades this week, 20 to 16. Moody's raised chipmaker TSMC to Aa2, citing its strong market position and finances, and S&P lifted eyewear group EssilorLuxottica to A+. On the downside, S&P cut Australia's Bank of Queensland one notch to BBB+ and french fry maker Lamb Weston to BB, a step deeper into junk. S&P also cut photo agency Getty Images to D, its default grade. The company has been short of cash since its planned merger with Shutterstock collapsed in June. Outside our table, the most awaited decision was on France: on Friday Moody's kept its rating at Aa3 with a negative outlook, instead of the widely expected cut to A1. The agency made that call before last weekend's protests and this week's jump in French bond yields.
| Issuer | Agency | Change |
|---|---|---|
| Albemarle | Fitch | BBB- → BBB |
| Bank of Queensland | S&P | A- → BBB+ |
| Beazer Homes | S&P | B- → B+ |
| Central American Bank for Economic Integration | Fitch | AA (new) |
| Clover Aviation Capital | Moody's | Baa3 → Baa2 |
| Co-operative Bank | Moody's | Baa2 → Baa1 |
| Co-operative Group | S&P | BB- → B+ |
| Companhia Siderurgica Nacional | S&P | B → B- |
| Corporacion Financiera de Desarrollo | Moody's | Baa1 (new) |
| Dream Finders Homes | S&P | BB- → B+ |
| Eagle Broadband Investments | S&P | B → CCC |
| EssilorLuxottica | S&P | A → A+ |
| Formosa Plastics | S&P | BBB → BBB+ |
| ForteLeasing | Fitch | BB → B+ |
| Geon Performance Solutions | S&P | B → B- |
| Getty Images | S&P | CCC → D |
| Golar LNG | S&P | B → B+ |
| HIME (Saur) | Fitch | BB+ → BB |
| Hovnanian Enterprises | S&P | B+ → B |
| Lamb Weston | S&P | BB+ → BB |
| Liberty Communications of Puerto Rico | S&P | CCC+ → CCC |
| Mega Broadband Investments | S&P | B → CCC |
| National Rural Utilities Cooperative Finance | S&P | A- → A |
| NPC Ukrenergo | Fitch | RD → CCC |
| Opmobility | S&P | BB+ → BB |
| PCC Global | S&P | B+ → B |
| Planview | S&P | B- → CCC+ |
| Raizen | Fitch | C → RD |
| South West Water | Fitch | BBB+ → BBB |
| Symplr Software | S&P | CCC+ → CC |
| Syniverse | S&P | D → CCC+ |
| TSMC | Moody's | Aa3 → Aa2 |
| University of Quebec at Montreal | S&P | BBB+ → A- |
| WCG Clinical | S&P | B- → B |
| Zijin Mining | S&P | BBB → BBB+ |
| Zinc-Polymer | S&P | CCC+ → CCC- |
New issues
Bond sales picked up despite the market swings. Euro investment-grade sales rose to about €16 billion, well above the €4–6 billion of each of the previous three weeks. Still, companies postponed more than $5 billion of US and European bond and loan deals this month, the most this year. Bank of America raised $8.5 billion in five parts, including a perpetual bond at 7.2%, and Kimberly-Clark sold $4.9 billion of 2- to 10-year bonds at 5.1% to 5.8%. Walmart borrowed $2.5 billion at 5.1% to 5.6%, and the World Bank (IBRD) sold $5 billion of 5-year bonds at 5.0%. Accounting firm Grant Thornton sold junk bonds for the first time, paying 10.5% on a 5-year dollar bond.
The table shows only bonds sold in small lots, with a minimum investment of 2,000 or less in the bond’s currency. Deals sold only in large blocks, or only to big US institutional investors, are left out.
| Issuer | Size | Term | Yield | Risk Level |
|---|---|---|---|---|
| African Development Bank | USD 2,5bn | 3Y | 4,9% | |
| ISIN (CUSIP)US00828EFQ70 | ||||
| Amwins Group | USD 0,50bn | 7Y | 7,4% | |
| ISIN (CUSIP)USU00217AG12 | ||||
| Bank of America | USD 8,5bn | 3– | 5,4–7,2%; FLOAT, +74bp | |
| ISIN (CUSIP)US06051GNE51…US06055HAN35 | ||||
| Bank of New York Mellon | USD 1,2bn | PERP | 7,1% | |
| ISIN (CUSIP)US064058AZ30 | ||||
| Bayerische Landesbank | EUR 0,50bn | 4Y | 3,6% | |
| ISIN (CUSIP)DE000BYL0R59 | ||||
| Citadel | USD 0,75bn | 5– | 6,3–6,7% | |
| ISIN (CUSIP)US17288XAF15…US17288XAE40 | ||||
| Deutsche Pfandbriefbank | EUR 0,50bn | 3Y | 3,8% | |
| ISIN (CUSIP)DE000A3827F9 | ||||
| European Investment Bank | GBP 0,50bn | 6Y | 5,1% | |
| ISIN (CUSIP)EU000A4E1WF6 | ||||
| Glencore Funding | USD 2,0bn | 3– | 5,5–6,3% | |
| ISIN (CUSIP)USU37818CC01…USU37818CE66 | ||||
| Grant Thornton Advisors | USD 1,7bn | 5Y | 10,5% | |
| ISIN (CUSIP)USU41365AA20 | ||||
| Inter-American Investment Corp | USD 0,50bn | 3Y | FLOAT, +32bp | |
| ISIN (CUSIP)US45825JAB26 | ||||
| Kimberly-Clark | USD 4,9bn | 2– | 5,1–5,8% | |
| ISIN (CUSIP)USU49436AF23…USU49436AK18 | ||||
| Landwirtschaftliche Rentenbank | USD 0,33bn | 6Y | 5,1% | |
| ISIN (CUSIP)XS3276317990 | ||||
| National Rural Utilities Cooperative Finance | USD 1,2bn | 2– | 5,3–5,6% | |
| ISIN (CUSIP)US63743HGJ59…US63743HGL06 | ||||
| Norddeutsche Landesbank (NORD/LB) | EUR 0,75bn | 6Y | 4,2% | |
| ISIN (CUSIP)DE000NLB6TG1 | ||||
| PLS Group | USD 0,70bn | 6Y | 8,0% | |
| ISIN (CUSIP)USQ7539CAB65 | ||||
| PNC Financial Services | USD 1,5bn | 3Y | 5,5%; FLOAT | |
| ISIN (CUSIP)US693475CP80 | ||||
| Queensland Treasury Corp | USD 2,0bn | 10Y | 5,5% | |
| ISIN (CUSIP)US74830XCM83 | ||||
| Radpar Escrow Issuer | USD 0,48bn | 6Y | 10,0% | |
| ISIN (CUSIP)USU7504EAA02 | ||||
| Sparkasse Hannover | EUR 0,50bn | 7Y | 3,8% | |
| ISIN (CUSIP)DE000A5GS7V3 | ||||
| State of Berlin | EUR 1,0bn | 5Y | 3,6% | |
| ISIN (CUSIP)DE000A5H3DL7 | ||||
| State of Hesse | EUR 0,50bn | 2Y | 3,4% | |
| ISIN (CUSIP)DE000A1RQFJ6 | ||||
| Walmart | USD 2,5bn | 3– | 5,1–5,6% | |
| ISIN (CUSIP)US931142GE78…US931142GC13 | ||||
| Workday | USD 2,5bn | 3– | 5,7–6,6% | |
| ISIN (CUSIP)US98138HAK77…US98138HAN17 | ||||
| World Bank (IBRD) | USD 5,0bn | 5Y | 5,0% | |
| ISIN (CUSIP)US459058ME09 | ||||
This article does not constitute investment advice or personal recommendation. Investments in securities and other financial instruments always involve the risk of loss of your capital. Past performance is not a reliable indicator of future results. Bondfish does not recommend using the data and information provided as the only basis for making any investment decision. You should not make any investment decisions without first conducting your own research and considering your own financial situation.