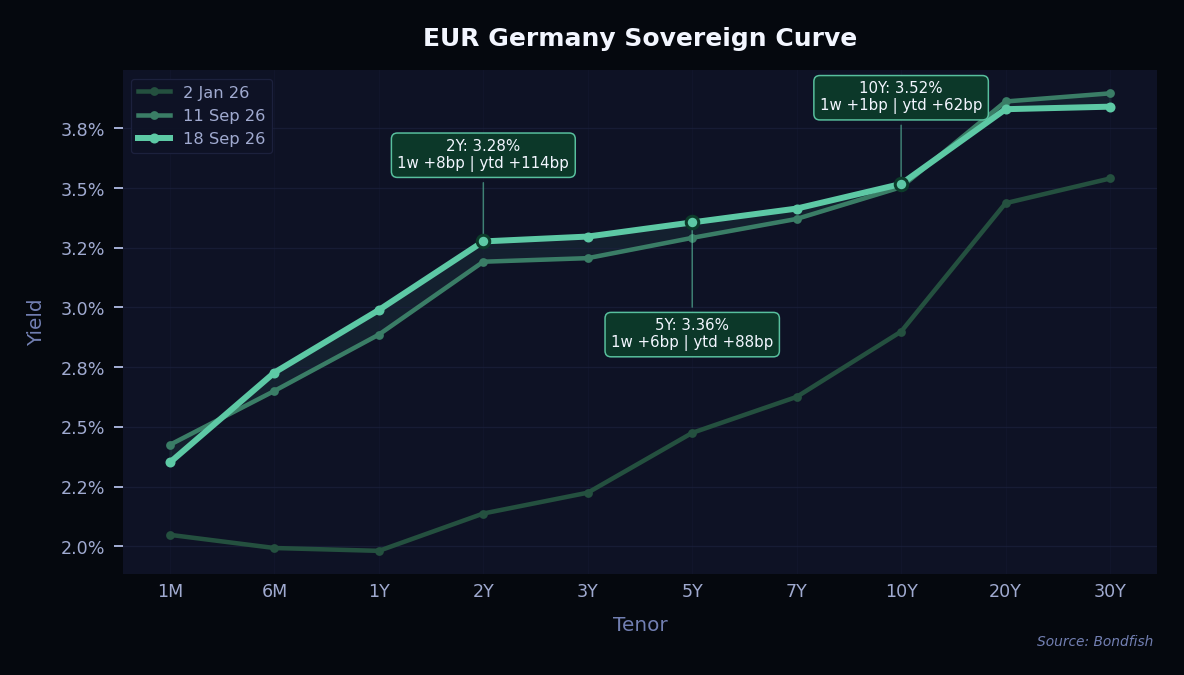
German yields rose again at the short end of the curve last week. The move came as investors bet the European Central Bank is not finished raising rates: after its September 10 hike, markets are now pricing in several more increases over the next year. Higher energy prices and the conflict in the Middle East are keeping inflation worries alive, and that pushes short-dated yields up the most. Longer-dated German yields barely moved, so the curve flattened. Italian and French bonds lagged Germany, and the gap between Italian and German 10-year yields widened to about 91 basis points.
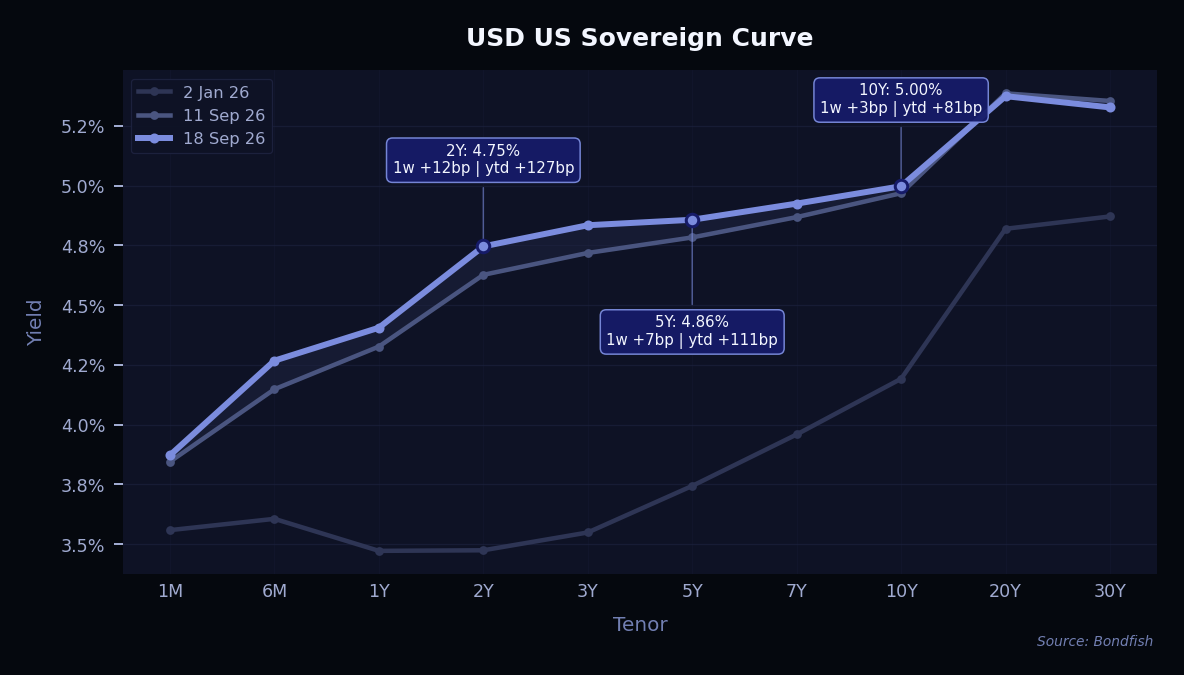
The Federal Reserve raised interest rates by a quarter point, to a range of 3.75 to 4.00 percent. It was the first hike in three years, and the Fed signaled that another increase is likely before year-end. Rising oil prices and the drawn-out Iran war are feeding inflation concerns, which is why policymakers are leaning toward more tightening. Short-dated Treasury yields rose the most on that message, while longer yields moved only a little, flattening the curve.
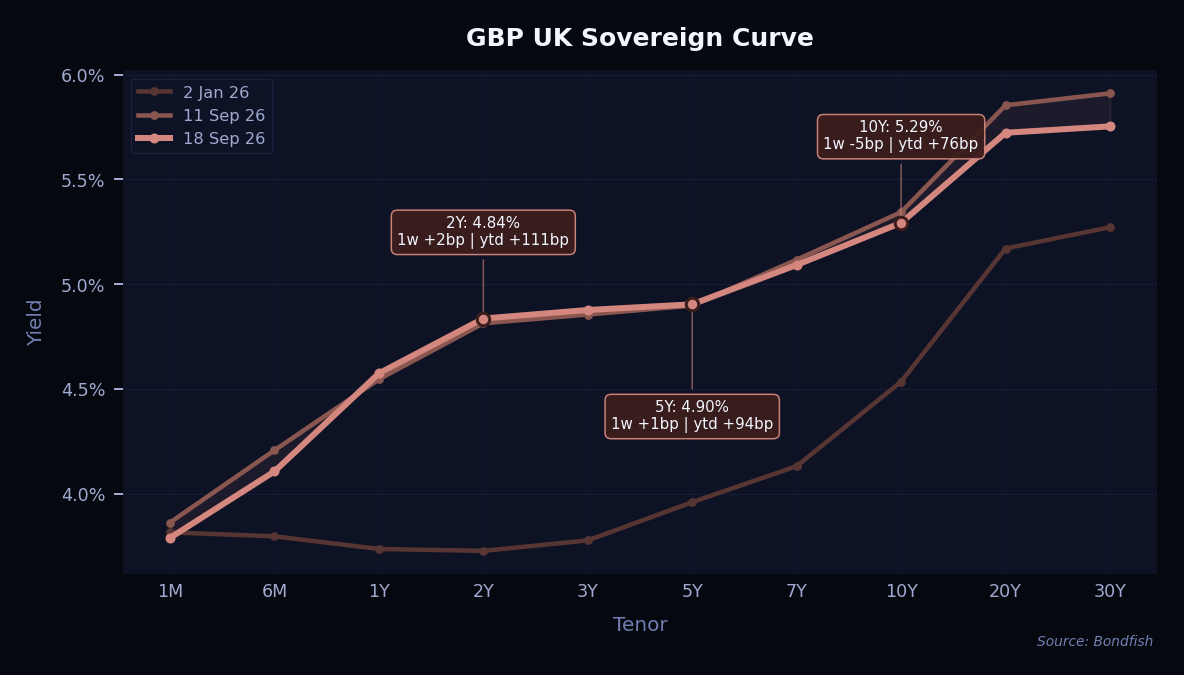
The Bank of England left interest rates unchanged at 3.75 percent. The bigger news was its plan for shrinking the large pile of bonds it bought in past years: it gave clearer, multi-year guidance on how that will work. That reassured investors, and long-dated UK government bonds rallied, pushing their yields down by around five basis points at the ten-year point. Short-dated yields were roughly steady, so the gilt curve flattened. That rally in long gilts is the main reason UK government bonds fill much of this week's list of top risers.
For now, the preferred approach is to favor shorter and medium maturities, roughly up to five years, and to stay cautious about locking in the longest maturities while central banks keep hinting at further rate rises.
Long-dated UK government bonds led the gainers, as gilt yields fell at the long end after the Bank of England clarified its bond-selling plans. Several long gilts, from the 2050 maturity out to 2068, rose more than 3 percent on the week. Outside the UK, US hospital landlord MPT Opt Partner topped the list with a 7 percent gain, and higher-yielding names such as Gabon and Transport for London also advanced.
| Name | Cur | Price change 1w(%) |
Yield | Risk Level |
| MPT Opt Partner 3.5% Mar 2031 | USD | 7,00% | 15,50% | Very High |
| United Kingdom 3.5% Jul 2068 | GBP | 4,85% | 5,52% | Very Low |
| United Kingdom 1.25% Nov 2055 | GBP | 4,30% | 2,36% | Very Low |
| United Kingdom 1.25% Nov 2054 | GBP | 4,21% | 2,37% | Very Low |
| United Kingdom 0.5% Mar 2050 | GBP | 3,88% | 2,40% | Very Low |
| United Kingdom 4% Oct 2063 | GBP | 3,68% | 5,65% | Very Low |
| United Kingdom 0.125% Aug 2048 | GBP | 3,66% | 2,40% | Very Low |
| TfL 4% Apr 2064 | GBP | 3,36% | 6,19% | Very Low |
| Gabon 7% Nov 2031 | USD | 3,33% | 9,58% | Very High |
| United Kingdom 4% Jan 2060 | GBP | 3,30% | 5,68% | Very Low |
US high-yield bonds dominated the fallers. Airline JetBlue, paper producer Domtar, chemicals maker Tronox, and telecom operator Windstream all dropped between roughly 3 and 5 percent. Retailer Bath & Body Works and Ukraine's dollar bonds also slipped. A long-dated, high-grade bond from Duke University Health System (DUHS) led the decliners.
| Name | Cur | Price change 1w(%) |
Yield | Risk Level |
| DUHS 3.162% Jun 2042 | USD | -5,39% | 6,09% | Very Low |
| JETBLUE AIRWAYS 9.875% Sep 2031 | USD | -5,25% | 15,77% | Very High |
| Domtar 6.75% Oct 2028 | USD | -4,25% | 19,82% | Very High |
| Tronox 4.625% Mar 2029 | USD | -3,90% | 25,95% | Very High |
| Ukraine 4.5% Feb 2034 | USD | -3,10% | 5,75% | Very High |
| FMC 6.375% May 2053 | USD | -2,95% | 8,64% | High |
| Windstream Serv 8.625% Jun 2032 | USD | -2,94% | 8,75% | Very High |
| Ukraine 4.5% Feb 2034 | USD | -2,75% | 12,93% | Very High |
| Bath & Body Works 7.6% Jul 2037 | USD | -2,58% | 8,16% | Very High |
| Ukraine 4.5% Feb 2036 | USD | -2,50% | 4,90% | Very High |
Note: only long-term senior unsecured ratings were taken into account.
Upgrades outnumbered downgrades. Jet-engine maker Safran, planemaker Embraer, packaging group Packaging Corp of America, and medical-equipment firm STERIS each moved up a notch, and property-services company Newmark climbed back into investment grade. On the downside, Poland lost a notch of its single-A rating, US agriculture group Corteva slipped out of the A range into the top of the triple-B tier, and bakery group Flowers Foods dropped out of investment grade into high yield. Two UK lenders, The Co-operative Bank and Coventry Building Society, were each trimmed by one notch, while Mozambique fell deeper into distressed territory.
| Issuer | Agency | Change |
| Aethon United BR | Fitch | B → B+ |
| AHF Parent | S&P | B- → CCC |
| alstria | S&P | BB → BB- |
| Aventiv Technologies | S&P | D → B- |
| Azorra Aviation | S&P | BB- → BB |
| Bank of Communications | S&P | A- → A |
| Belize | Moody's | Caa1 → B3 |
| Borgo | Moody's | Baa2 → Baa3 |
| China Longyuan Power | S&P | A- → A |
| China Minsheng Bank | S&P | BBB- → BBB |
| Co-Operative Bank | Fitch | A+ → A |
| Corteva | S&P | A- → BBB+ |
| Coventry Building Society | Fitch | A+ → A |
| Embraer | Moody's | Baa3 → Baa2 |
| Endo Finance | Fitch | B+ → BB- |
| Flowers Foods | Fitch | BBB- → BB+ |
| GF Securities | S&P | BBB → BBB+ |
| Hero Asia Investment | S&P | BBB+ → A- |
| Huaxia Bank | S&P | BBB- → BBB |
| Joint-Stock Co Anor Bank | Fitch | B- → CCC+ |
| Keenova Therapeutics | Fitch | B+ → BB- |
| McGraw Hill | S&P | B+ → BB- |
| Mozambique | Moody's | Caa2u → Caa3u |
| Naked Juice | S&P | CCC → CCC+ |
| Newmark | S&P | BB+ → BBB- |
| Packaging Corp of America | S&P | BBB → BBB+ |
| Plano HoldCo | S&P | B → B- |
| PM General Purchaser | S&P | B- → CCC |
| Poland | Moody's | A2 → A3 |
| Safran | S&P | A- → A |
| Sasa Polyester Sanayi | Fitch | CCC → B- |
| Securus | S&P | D → B- |
| Shanghai Pudong Development Bank | S&P | BBB → BBB+ |
| STERIS | Moody's | Baa2 → Baa1 |
| Thiess | S&P | BB+ → BBB- |
| Tri Pointe Homes | S&P | BB → BB+ |
| Uzum | Fitch | B → B+ |
| Velocity Vehicle | S&P | B- → B |
| Vistance Networks | S&P | B- → B+ |
| Wildfire Intermediate | S&P | B → BB- |
It was a busy week for new bond sales, with US high-grade companies alone raising about 54 billion dollars. One pattern stood out: investors are hungry for long-dated bonds, but companies are reluctant to sell them, because high long-term yields make decades of interest payments expensive. So most borrowers stuck to shorter maturities, around five to seven years or less. The week's largest deals included an 11-billion-euro, two-part sale from the European Union and Citigroup's biggest-ever bond offering, a four-part deal that raised about 12 billion dollars.
| Issuer | Size | Term | Yield | Risk Level |
| Accru Partners Group | EUR 0,55bn |
4Y | FLOAT, +475bp | Very High |
|
ISIN (CUSIP)
SE0030285896
|
||||
| Achmea Bank | EUR 0,50bn |
5Y | 3,7% | Very High |
|
ISIN (CUSIP)
XS3512792659
|
||||
| Agree | USD 0,40bn |
10Y | 5,8% | Medium |
|
ISIN (CUSIP)
008513AG8
|
||||
| Alpha Bank | EUR 0,70bn |
4Y | 4,4% | Medium |
|
ISIN (CUSIP)
XS3518480655
|
||||
| American International Group | EUR 0,50bn |
10Y | 4,8% | Medium |
|
ISIN (CUSIP)
XS3512902340
|
||||
| Amsted Industries | USD 0,25bn |
7Y | 6,7% | High |
|
ISIN (CUSIP)
USU0018PAH48
|
||||
| Analog Devices | USD 3,0bn |
3–10Y | 5,1–5,8% | Low |
|
ISIN (CUSIP)
US032654BG94…US032654BK07
|
||||
| Aon North America | USD 8,8bn |
3–20Y | 5,4–6,5% | Medium |
|
ISIN (CUSIP)
US036940AA21…US036940AF18
|
||||
| ASN Bank | EUR 0,50bn |
4Y | 3,7% | Very High |
|
ISIN (CUSIP)
XS3512738017
|
||||
| Assemblin Caverion Group | EUR 1,5bn |
7Y | FLOAT, +300bp | Very High |
|
ISIN (CUSIP)
XS3489941826
|
||||
| Australia and New Zealand Banking Group | EUR 0,75bn |
10Y | 4,7% | Low |
|
ISIN (CUSIP)
XS3507647983
|
||||
| AXA Logistics Europe Master | EUR 0,30bn |
6Y | 4,7% | Low |
|
ISIN (CUSIP)
XS3506252678
|
||||
| Bank of Ireland Group | EUR 0,75bn |
10Y | 4,8% | Medium |
|
ISIN (CUSIP)
XS3513205594
|
||||
| Banque Federative du Credit Mutuel | EUR 2,2bn |
4–8Y | 4,3–4,7% | Low |
|
ISIN (CUSIP)
FR001401B4Q9…FR001401B4S5
|
||||
| BPCE | EUR 1,5bn |
6Y | 4,6% | Low |
|
ISIN (CUSIP)
FR001401B5J1
|
||||
| Bremen | EUR 0,50bn |
7Y | FLOAT, +10bp | Very Low |
|
ISIN (CUSIP)
DE000A5ENMU5
|
||||
| Brown-Forman | USD 0,50bn |
5Y | 5,4% | Low |
|
ISIN (CUSIP)
115637AV2
|
||||
| Burford Capital Global Finance | USD 0,30bn |
3Y | 8,0% | Medium |
|
ISIN (CUSIP)
USU1056LAG69
|
||||
| Carrefour | EUR 0,50bn |
6Y | 4,4% | Very High |
|
ISIN (CUSIP)
FR001401B544
|
||||
| CDW | USD 1,5bn |
2–7Y | 5,7–6,4% | Medium |
|
ISIN (CUSIP)
US12513GBM06…US12513GBP37
|
||||
| Citigroup | USD 12,0bn |
3–11Y | 5,3–5,9%; FLOAT | Low |
|
ISIN (CUSIP)
US172967QN45…US172967QR58
|
||||
| Commerzbank | EUR 0,75bn |
4Y | 4,2% | Medium |
|
ISIN (CUSIP)
DE000CZ46C68
|
||||
| Corporacion Andina de Fomento | USD 2,0bn |
5Y | 4,8% | Very Low |
|
ISIN (CUSIP)
US219868CS37
|
||||
| CPPIB Capital | GBP 0,75bn |
4Y | 5,1% | Very Low |
|
ISIN (CUSIP)
XS3509679828
|
||||
| Credit Agricole | EUR 0,75bn |
PERP | 6,4% | Medium |
|
ISIN (CUSIP)
FR001401B072
|
||||
| CSDC Finance I | USD 2,3bn |
5Y | 8,2% | Very High |
|
ISIN (CUSIP)
126315AA8
|
||||
| Danske Bank A/S | EUR 0,75bn |
5Y | 4,1% | Low |
|
ISIN (CUSIP)
XS3517355387
|
||||
| Energia Group | EUR 0,85bn |
6Y | 5,5% | Medium |
|
ISIN (CUSIP)
XS3511194386
|
||||
| European Union | EUR 11,0bn |
4–30Y | 3,5–4,5% | Very Low |
|
ISIN (CUSIP)
EU000A4E0858…EU000A4E0866
|
||||
| Evergy Missouri West | USD 0,30bn |
10Y | 6,0% | Medium |
|
ISIN (CUSIP)
USU3000EAD23
|
||||
| Expand Energy | USD 0,50bn |
5Y | 5,7% | Medium |
|
ISIN (CUSIP)
US165167DJ30
|
||||
| Grunenthal | EUR 0,85bn |
6Y | 5,4%; FLOAT, +275bp | High |
|
ISIN (CUSIP)
XS3479614268
|
||||
| Henkel US Finance | EUR 1,0bn |
3–7Y | 3,9–4,3% | Low |
|
ISIN (CUSIP)
DE000A4E0VR6…DE000A4E0VS4
|
||||
| Hoffman Schroff Holdings | USD 0,80bn |
10Y | 6,2% | Very High |
|
ISIN (CUSIP)
US434541AA62
|
||||
| HSBC Holdings | EUR 3,8bn |
4–11Y | 4,4–4,8%; FLOAT, +75bp | Low |
|
ISIN (CUSIP)
XS3504856868…XS3504857080
|
||||
| Hyundai Capital America | USD 1,5bn |
3–5Y | 5,4–5,6% | Low |
|
ISIN (CUSIP)
US44891CER07…US44891CES89
|
||||
| International Development Association | USD 3,0bn |
5Y | 4,9% | Very Low |
|
ISIN (CUSIP)
US45939FAC14
|
||||
| KODIT Global | USD 0,30bn |
3Y | FLOAT, +73bp | Very Low |
|
ISIN (CUSIP)
XS3504667976
|
||||
| Kookmin Bank | EUR 0,65bn |
4Y | 3,8% | Very Low |
|
ISIN (CUSIP)
XS3512877997
|
||||
| Landesbank Saar | EUR 0,50bn |
5Y | 4,1% | Very Low |
|
ISIN (CUSIP)
DE000SLB9310
|
||||
| Landwirtschaftliche Rentenbank | USD 1,0bn |
10Y | 5,1% | Very Low |
|
ISIN (CUSIP)
US515110CL64
|
||||
| Mecklenburg-Vorpommern | EUR 0,50bn |
6Y | 3,6% | Very Low |
|
ISIN (CUSIP)
DE000A5GS6X1
|
||||
| Mitsubishi Estate | USD 0,30bn |
5Y | 5,5% | Low |
|
ISIN (CUSIP)
XS3501326782
|
||||
| MMS Holdings USA | EUR 0,50bn |
4Y | 4,2% | Medium |
|
ISIN (CUSIP)
FR001401B2N0
|
||||
| MOL | EUR 0,50bn |
5Y | 4,9% | Medium |
|
ISIN (CUSIP)
XS3515070046
|
||||
| Mutual of Omaha Companies Global Funding | USD 0,60bn |
3Y | 5,5% | Low |
|
ISIN (CUSIP)
62829E2K3
|
||||
| Natixis Pfandbriefbank | EUR 0,25bn |
3Y | 3,7% | Very Low |
|
ISIN (CUSIP)
DE000A5KW3K3
|
||||
| Nordic Investment Bank | GBP 0,30bn |
3Y | FLOAT, +25bp | Very Low |
|
ISIN (CUSIP)
XS3518483675
|
||||
| Nykredit Realkredit A/S | EUR 0,50bn |
2Y | FLOAT, +45bp | Low |
|
ISIN (CUSIP)
DK0030567086
|
||||
| Playtech | EUR 0,35bn |
5Y | 5,5% | High |
|
ISIN (CUSIP)
XS3498851669
|
||||
| RCI Banque | EUR 1,2bn |
4–7Y | 4,7–5,1% | Medium |
|
ISIN (CUSIP)
FR001401AXB7…FR001401AXC5
|
||||
| RWE Finance US | USD 1,5bn |
5–10Y | 5,6–6,0% | Medium |
|
ISIN (CUSIP)
USU77796AF44…USU77796AG27
|
||||
| Saab | EUR 0,30bn |
7Y | 4,3% | Very High |
|
ISIN (CUSIP)
XS3515071101
|
||||
| Sandoz Finance | EUR 0,50bn |
12Y | 4,8% | Medium |
|
ISIN (CUSIP)
XS3506241630
|
||||
| Sony Life Insurance | USD 0,70bn |
30Y | 7,1% | Very High |
|
ISIN (CUSIP)
XS3504150767
|
||||
| Southwestern Electric Power | USD 0,75bn |
10Y | 6,1% | Medium |
|
ISIN (CUSIP)
845437BX9
|
||||
| Tornator | EUR 0,30bn |
6Y | 4,6% | Medium |
|
ISIN (CUSIP)
FI4000609631
|
||||
| Toyota Motor Credit | EUR 0,75bn |
6Y | 4,3% | Low |
|
ISIN (CUSIP)
XS3511196753
|
||||
| Transdigm | USD 3,0bn |
8Y | 6,8% | High |
|
ISIN (CUSIP)
USU8936PBM42
|
||||
| UniCredit | EUR 0,75bn |
PERP | 6,3% | High |
|
ISIN (CUSIP)
IT0005732620
|
||||
| UniCredit | USD 0,13bn |
6Y | FLOAT, +90bp | Very High |
|
ISIN (CUSIP)
IT0005730913
|
||||
| Var Energi | USD 2,5bn |
3–10Y | 5,6–6,2% | Medium |
|
ISIN (CUSIP)
USR9576ZAN89…USR9576ZAQ11
|
||||
| Volkswagen Bank | EUR 2,5bn |
2–8Y | 4,2–4,9% | Low |
|
ISIN (CUSIP)
XS3508755496…XS3508768390
|
||||
| Wells Fargo | USD 3,5bn |
11Y | 5,8% | Low |
|
ISIN (CUSIP)
95000U4M2
|
||||
| Xylem | USD 1,5bn |
3–10Y | 5,3–5,9% | Medium |
|
ISIN (CUSIP)
US98419MAQ33…98419MAS9
|
||||